Figure 1From “The European failure number nobody quotes”
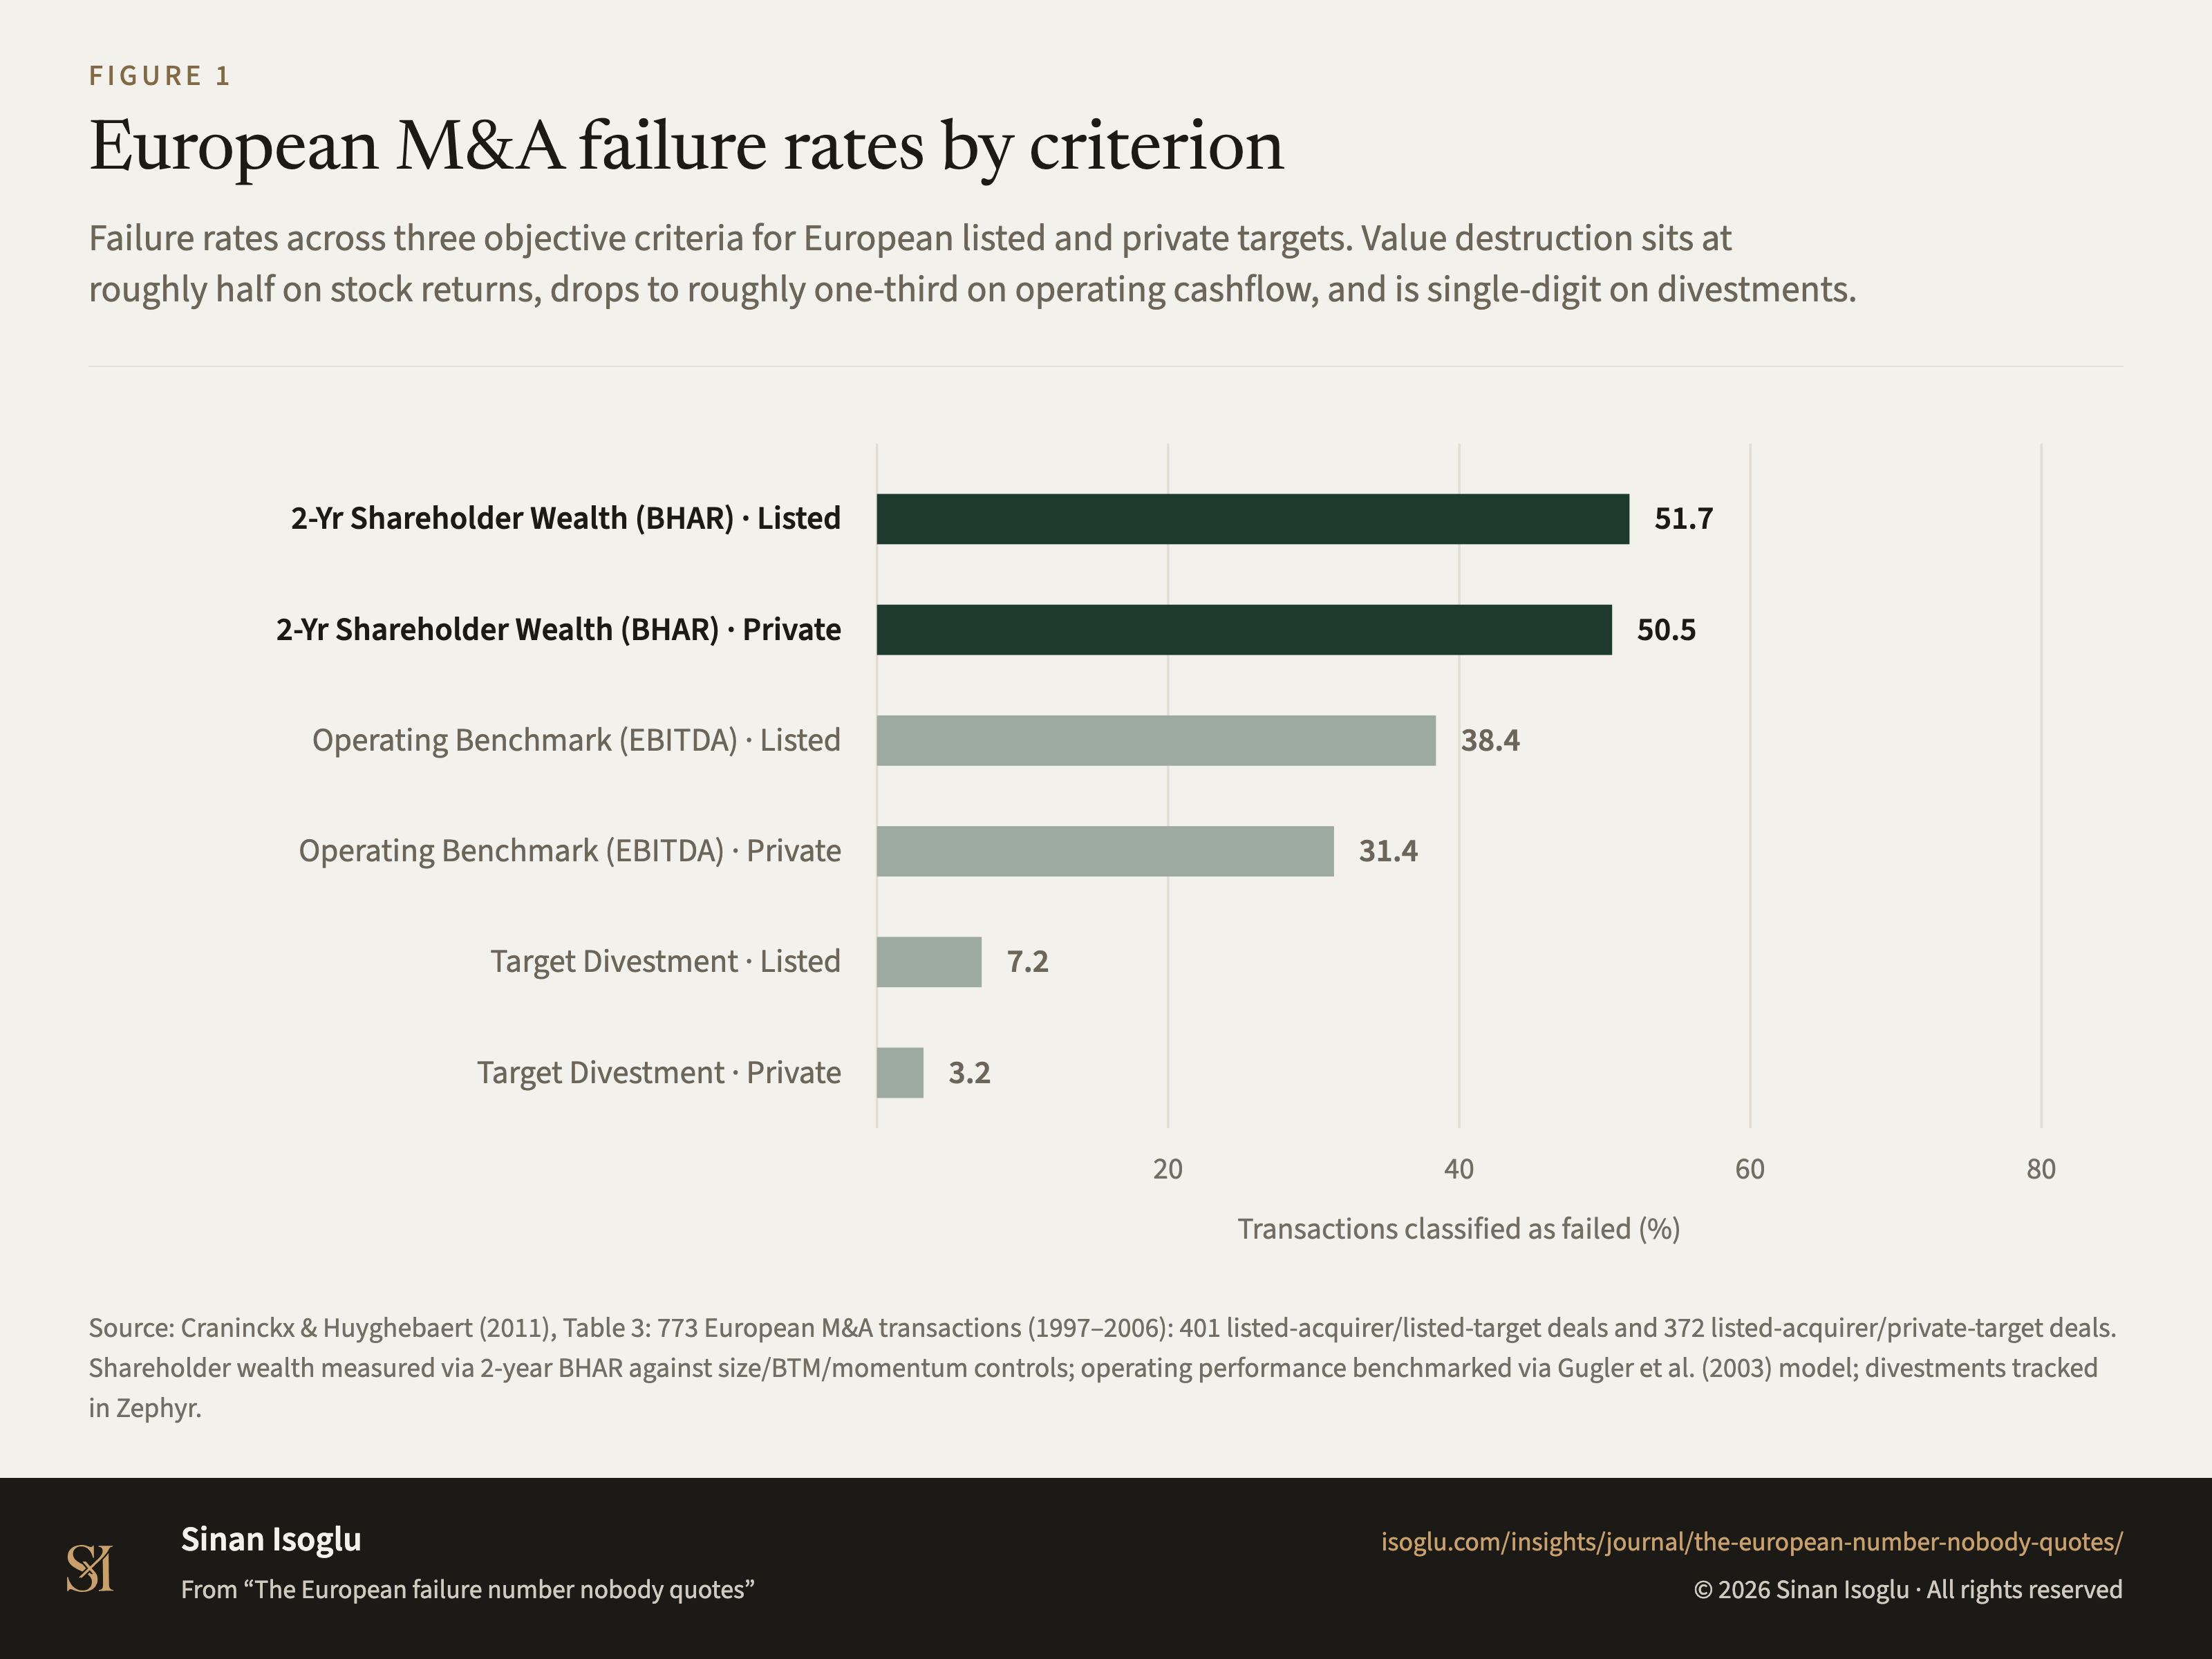
European M&A failure rates by criterion
Failure rates across three objective criteria for European listed and private targets. Value destruction sits at roughly half on stock returns, drops to roughly one-third on operating cashflow, and is single-digit on divestments.
Figure 1European M&A failure rates by criterion
Source: Craninckx & Huyghebaert (2011), Table 3: 773 European M&A transactions (1997–2006): 401 listed-acquirer/listed-target deals and 372 listed-acquirer/private-target deals. Shareholder wealth measured via 2-year BHAR against size/BTM/momentum controls; operating performance benchmarked via Gugler et al. (2003) model; divestments tracked in Zephyr.
Source and evidence
Each line names a claim related to this exhibit, its source, and how it was checked.
- A CH11-C1 Sample A and Sample B, verbatim: "more than half (51.7%) of the transactions in Sample A destroyed shareholder value up to two years following deal completion", and in Sample B "50.5% of acquirers exhibit inferior stock performance"Craninckx & Huyghebaert (2011), Table 3
- A CH11-C2 "approximately 38.4% of these M&As resulted in an abnormal operating performance decrease during that window" for listed targets; "31.4% of firms realize inferior operating performance" for private onesCraninckx & Huyghebaert (2011), Table 3
- A CH11-C3 The divestment rate is the small one: "in only about 7.2% of the cases, the acquiring management decided to sell off a majority stake in the target after the deal was closed", against "about 3.2%" in the private-target sampleCraninckx & Huyghebaert (2011), Table 3
- A CH11-C4 Across criteria, European M&A failure rates run "roughly between 38% and 53%" for listed targetsCraninckx & Huyghebaert (2011), section 5
Grades: A, verified against the printed page of the primary source · B, primary source, text layer only · C, authoritative secondary · D, reported.
From the essay
Growth that compounds
The European failure number nobody quotes
Every European boardroom repeats that 70% to 90% of mergers fail. The peer-reviewed European record measures value destruction at roughly half.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Related exhibits
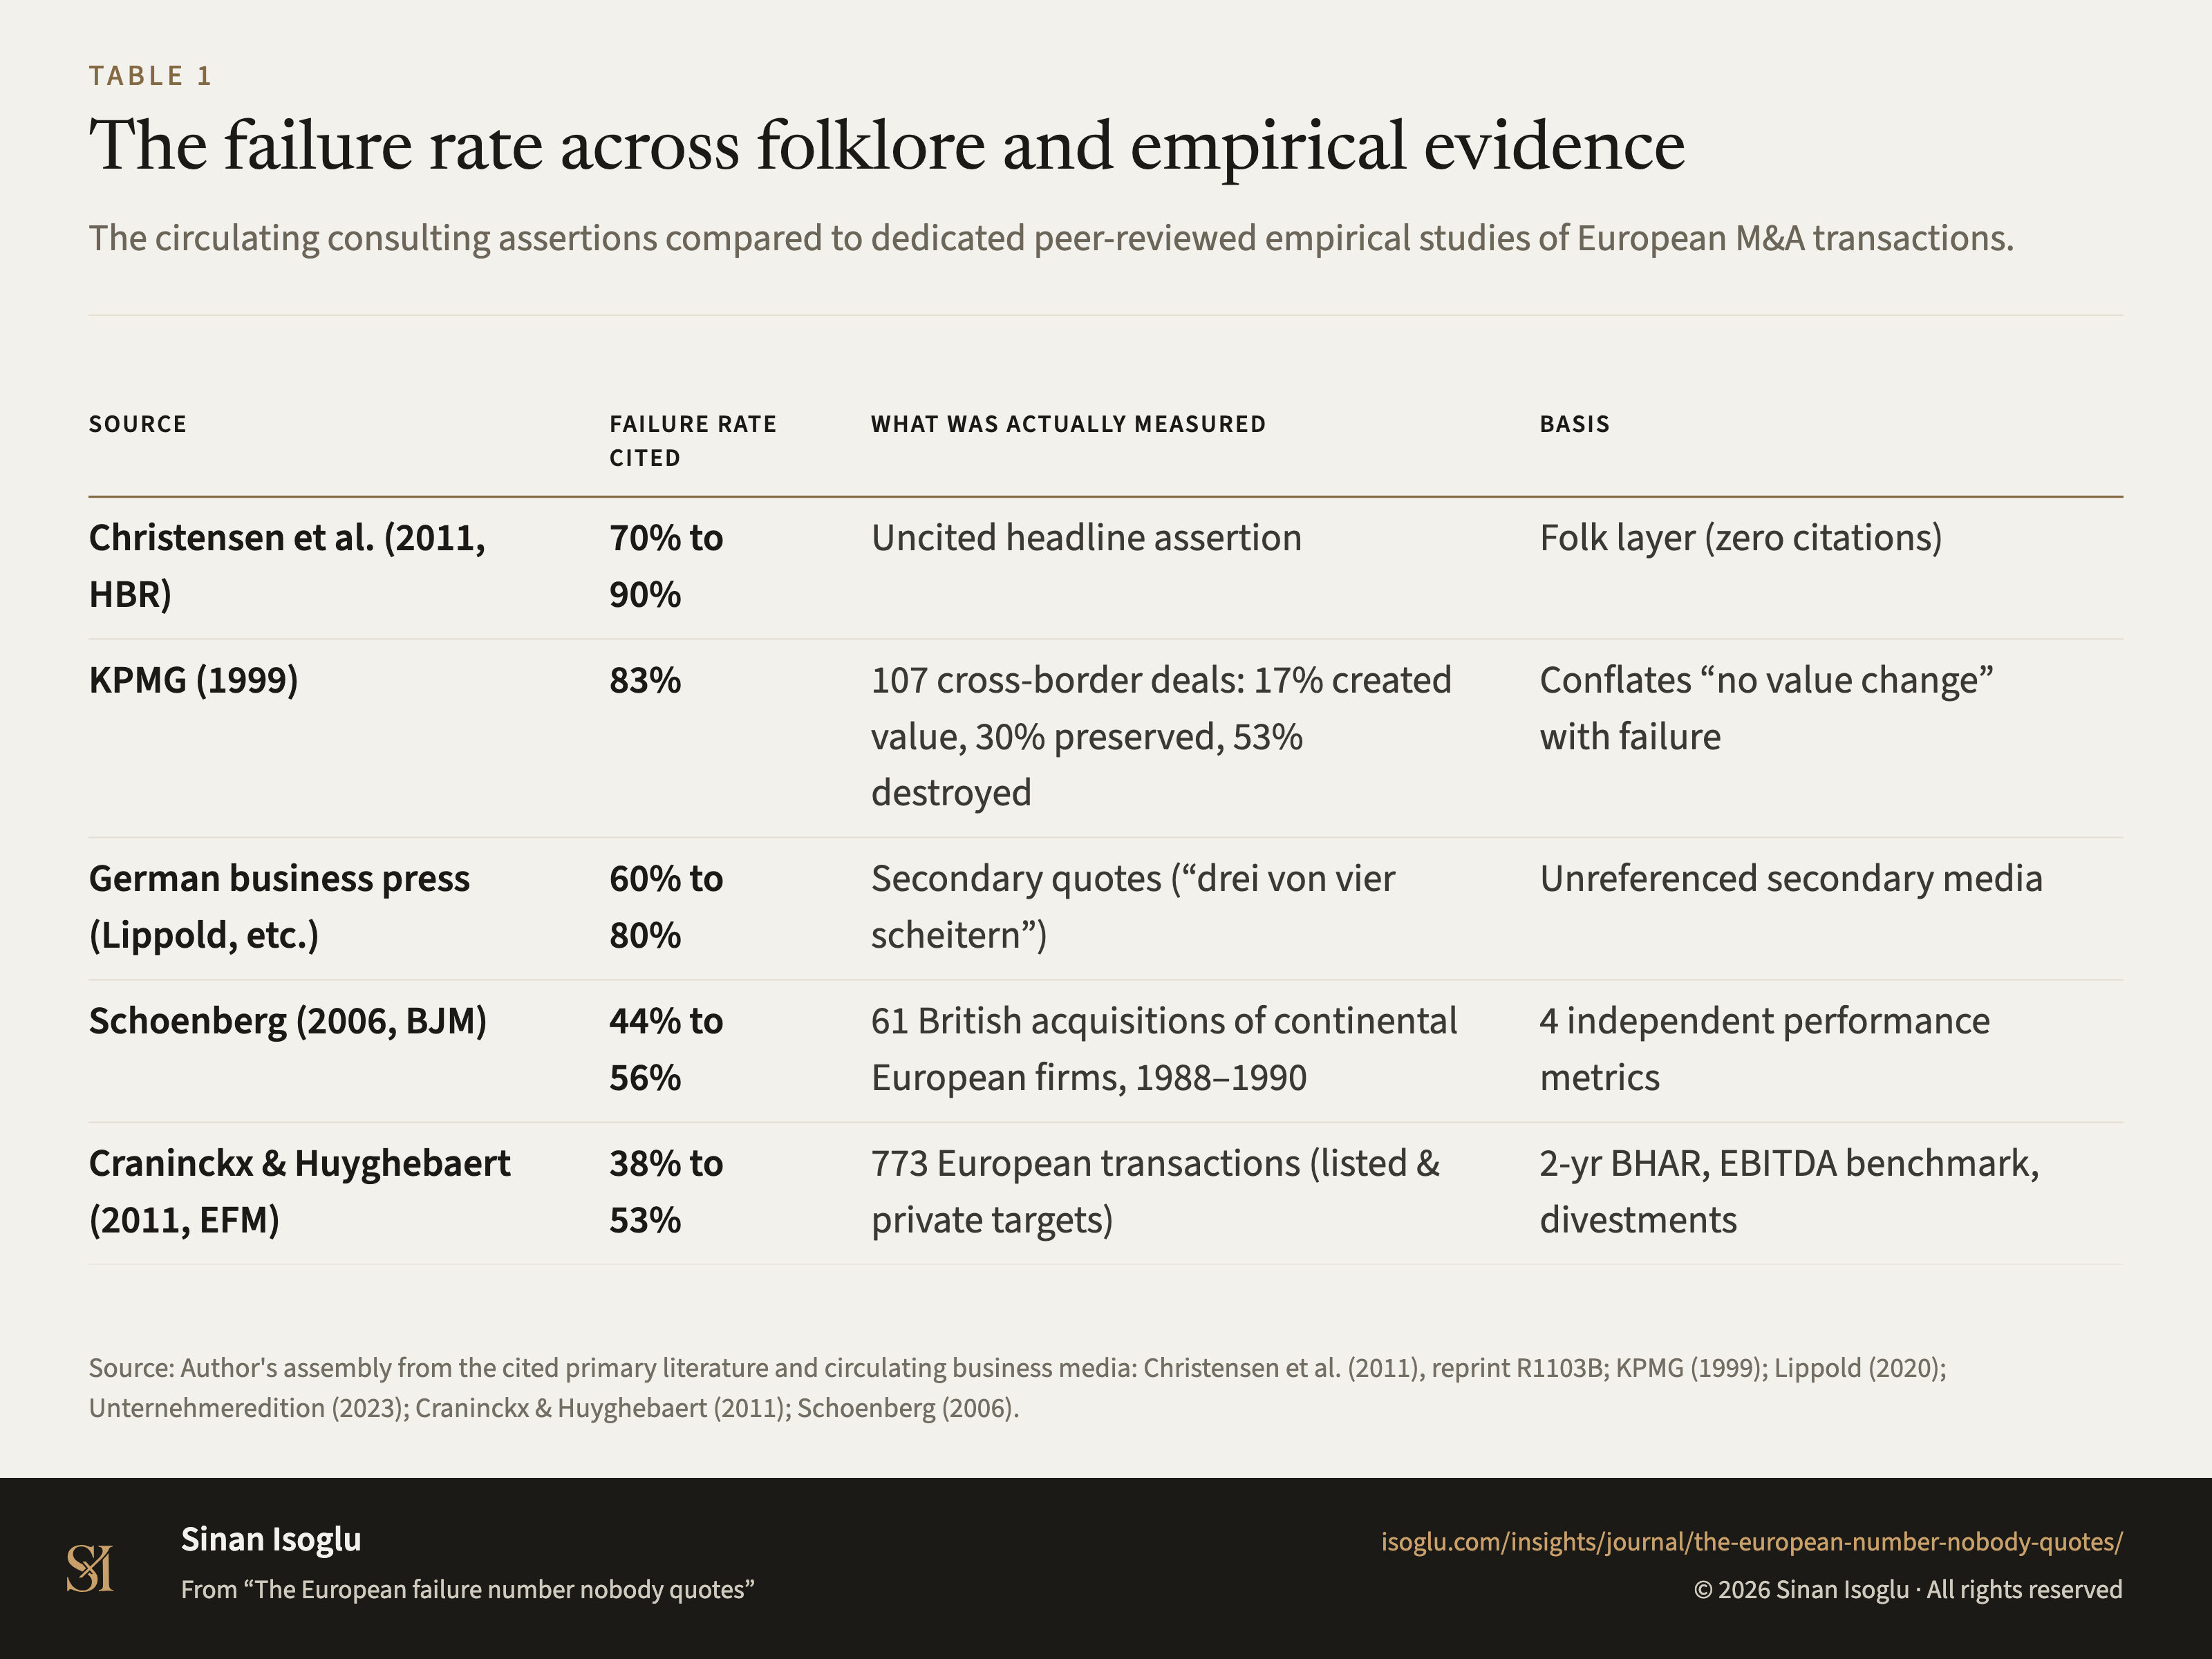
Table 1Table
The failure rate across folklore and empirical evidence
The European failure number nobody quotes
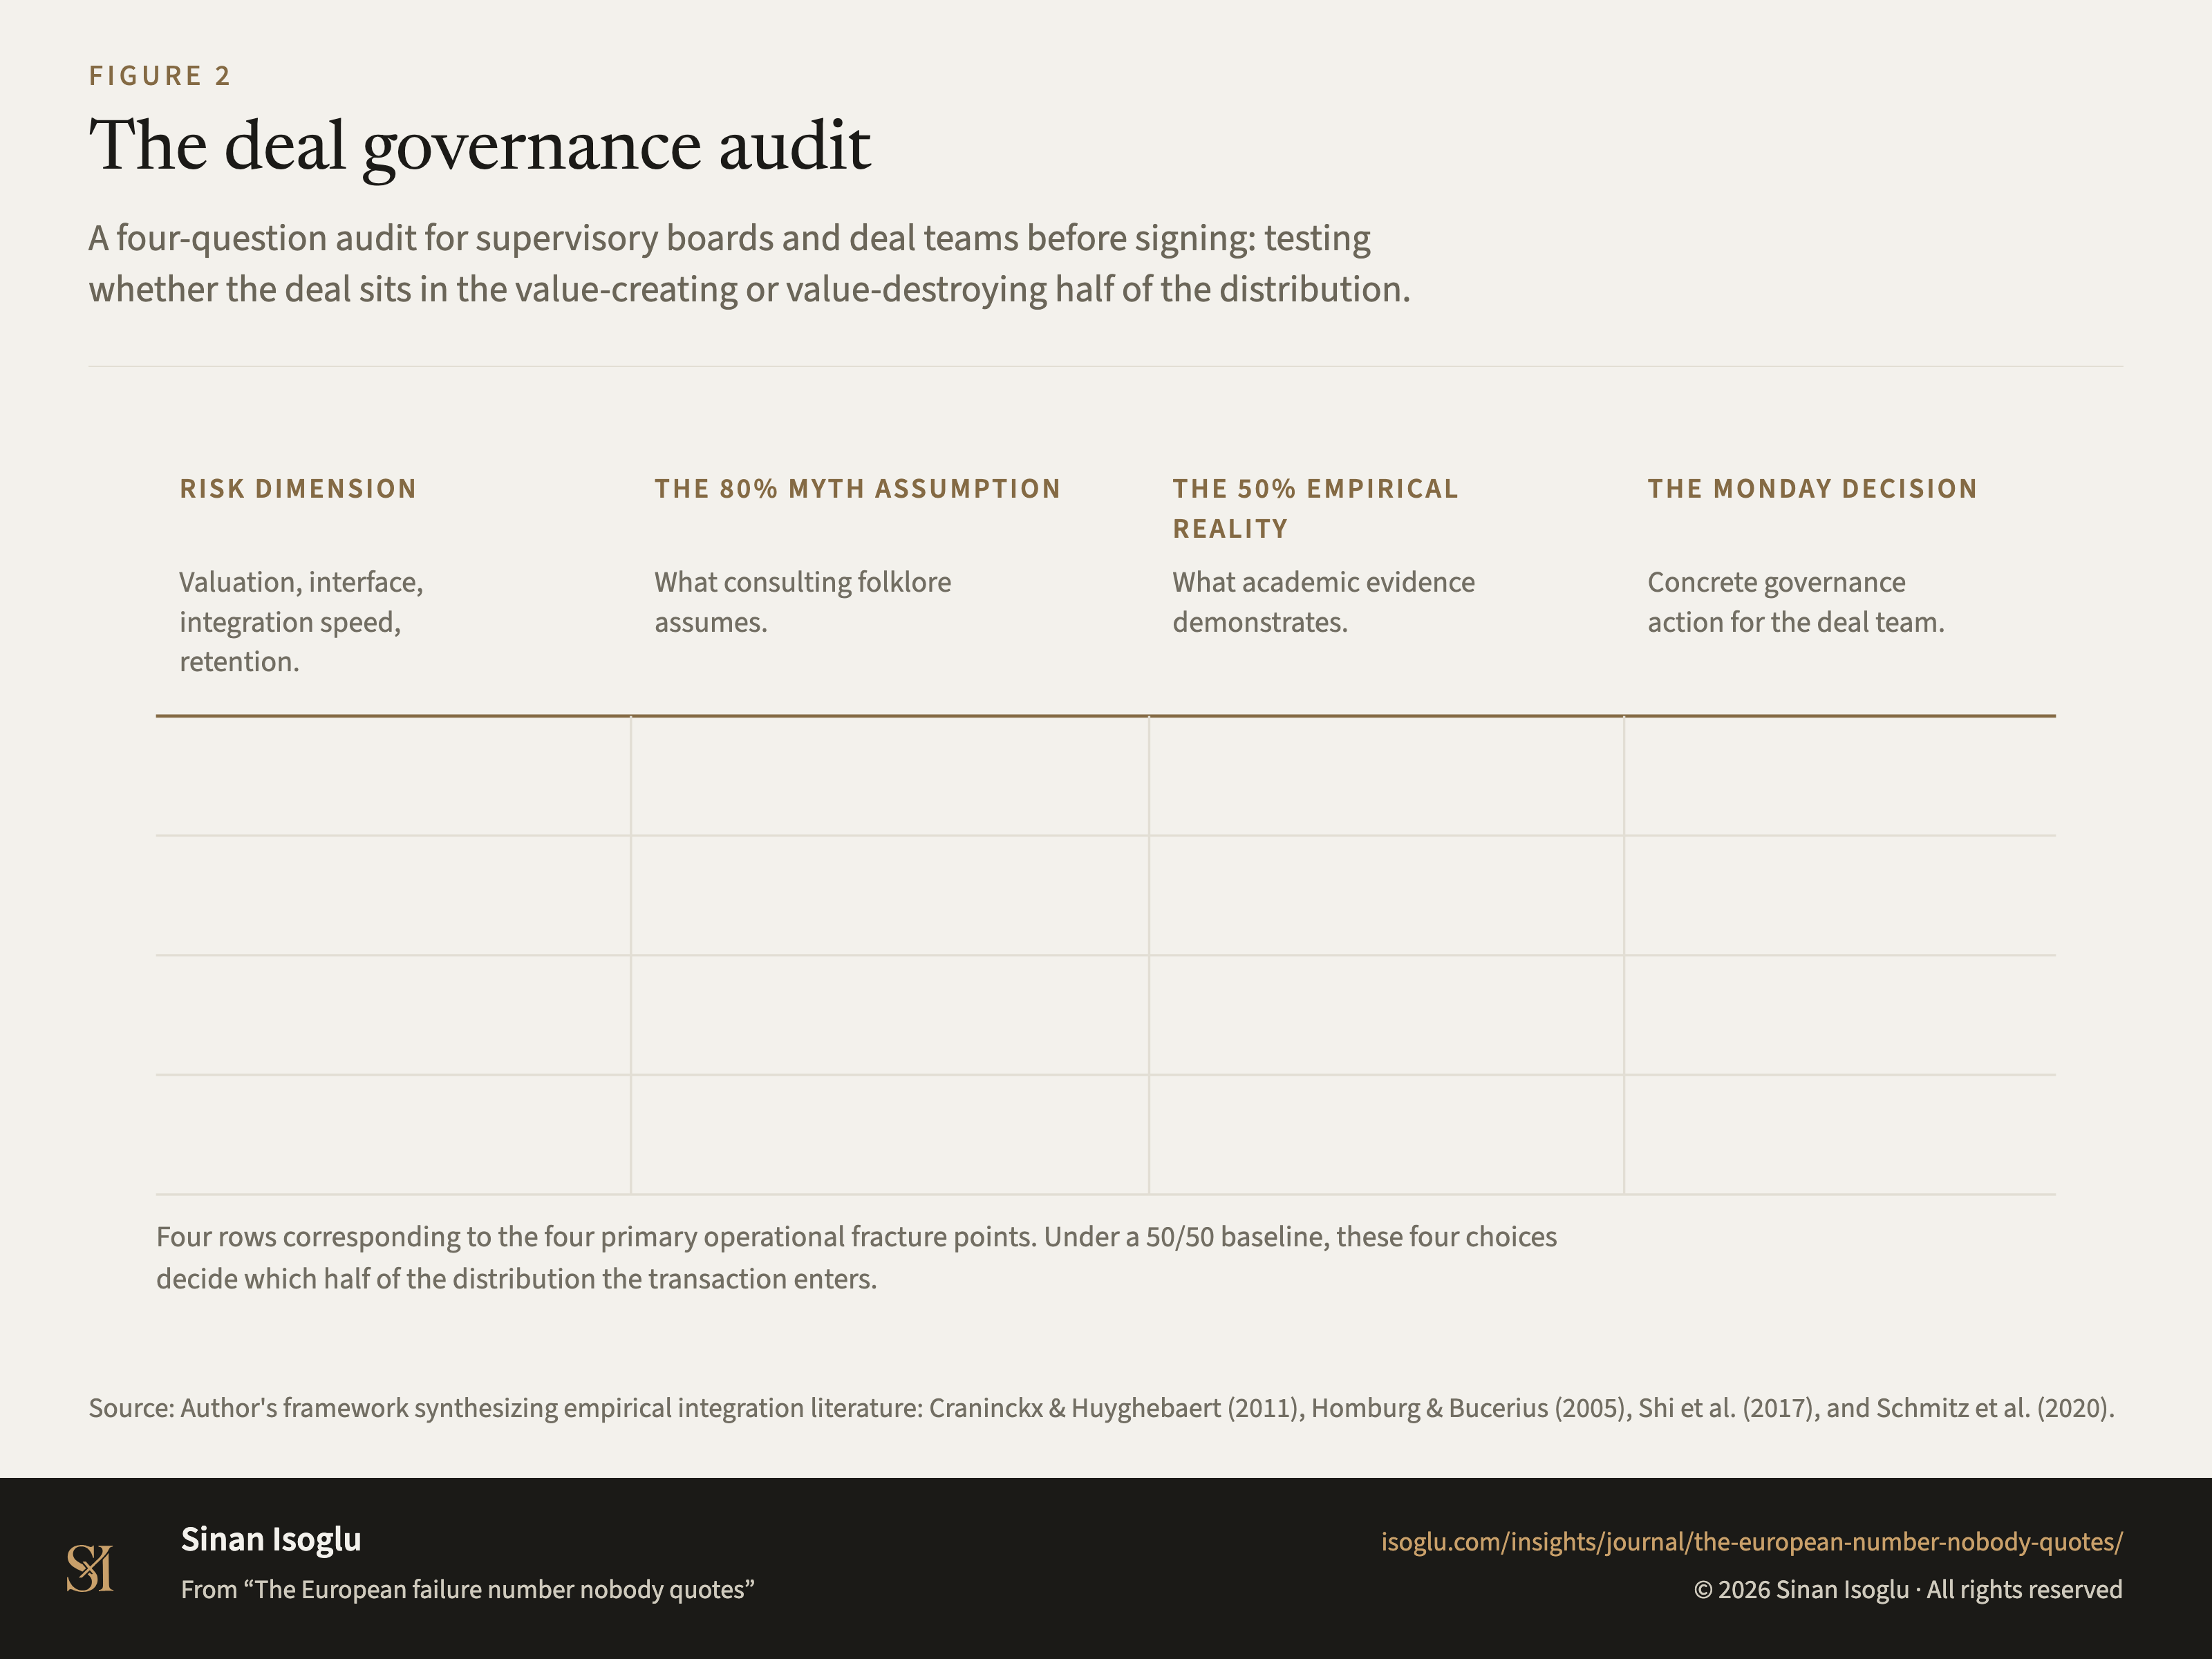
Figure 2Figure
The deal governance audit
The European failure number nobody quotes
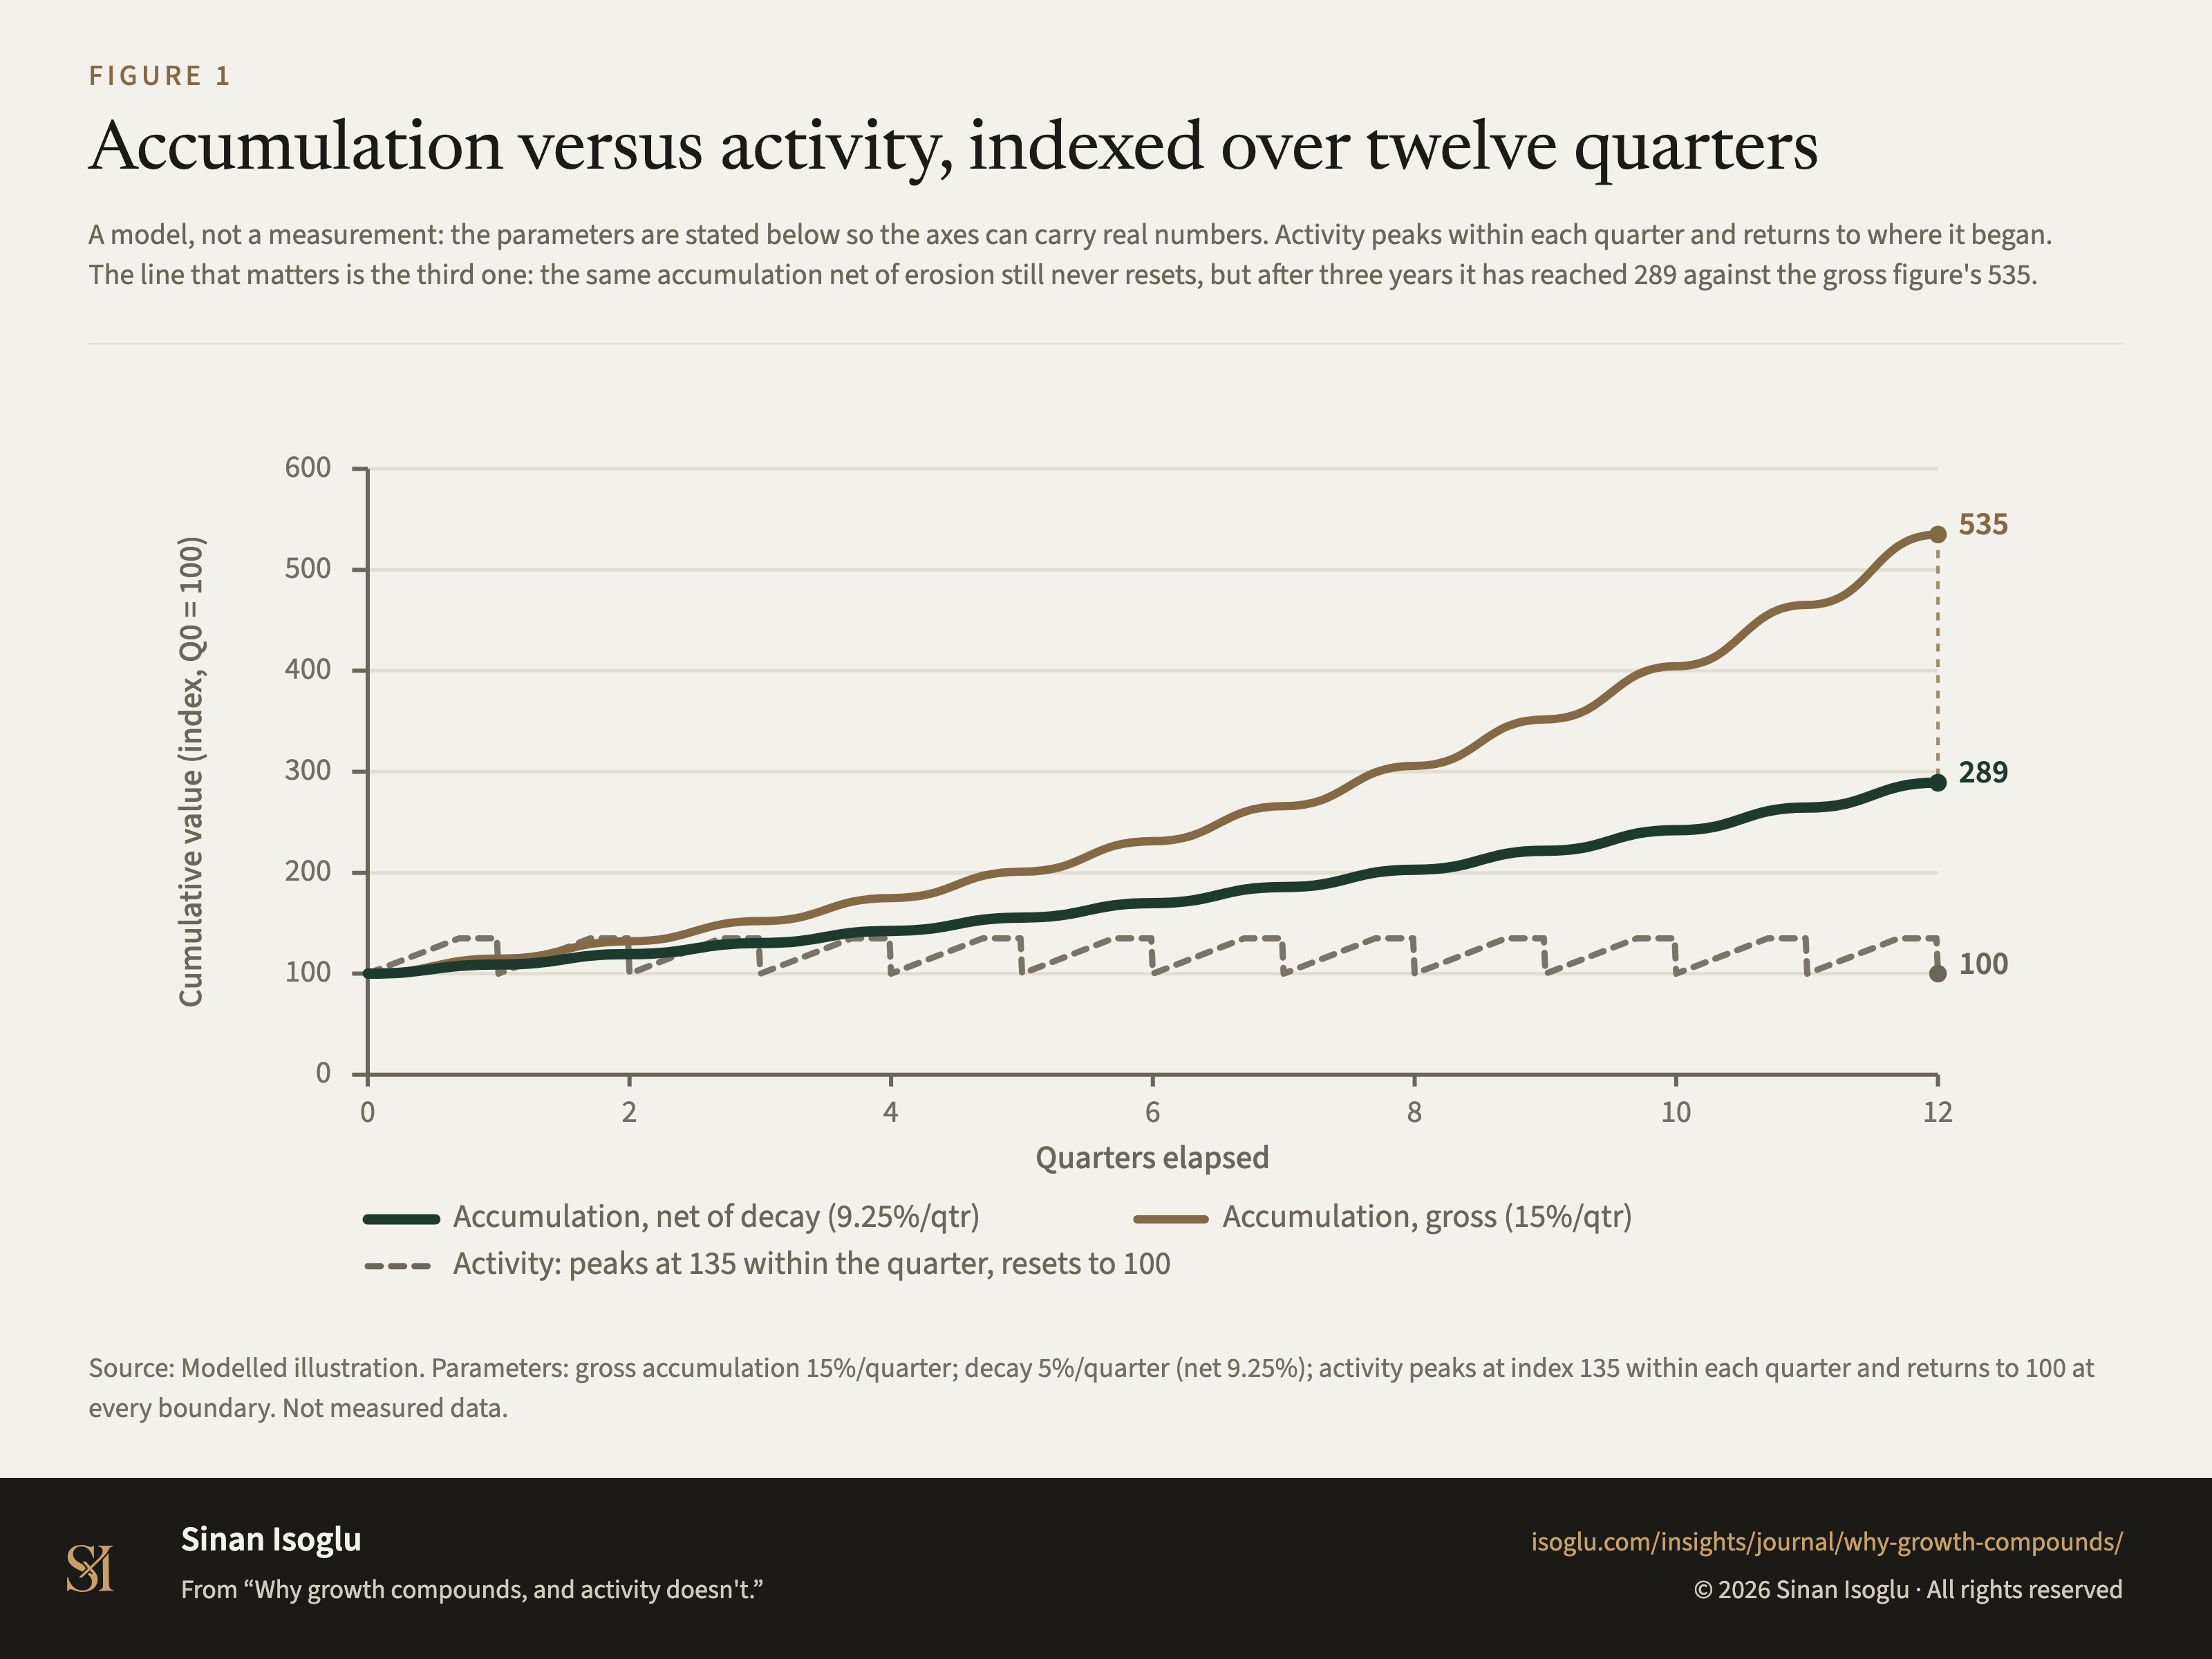
Figure 1Figure
Accumulation versus activity, indexed over twelve quarters
Why growth compounds, and activity doesn't.
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.