Figure 1From “What is price realization? List price is not the cash collected”
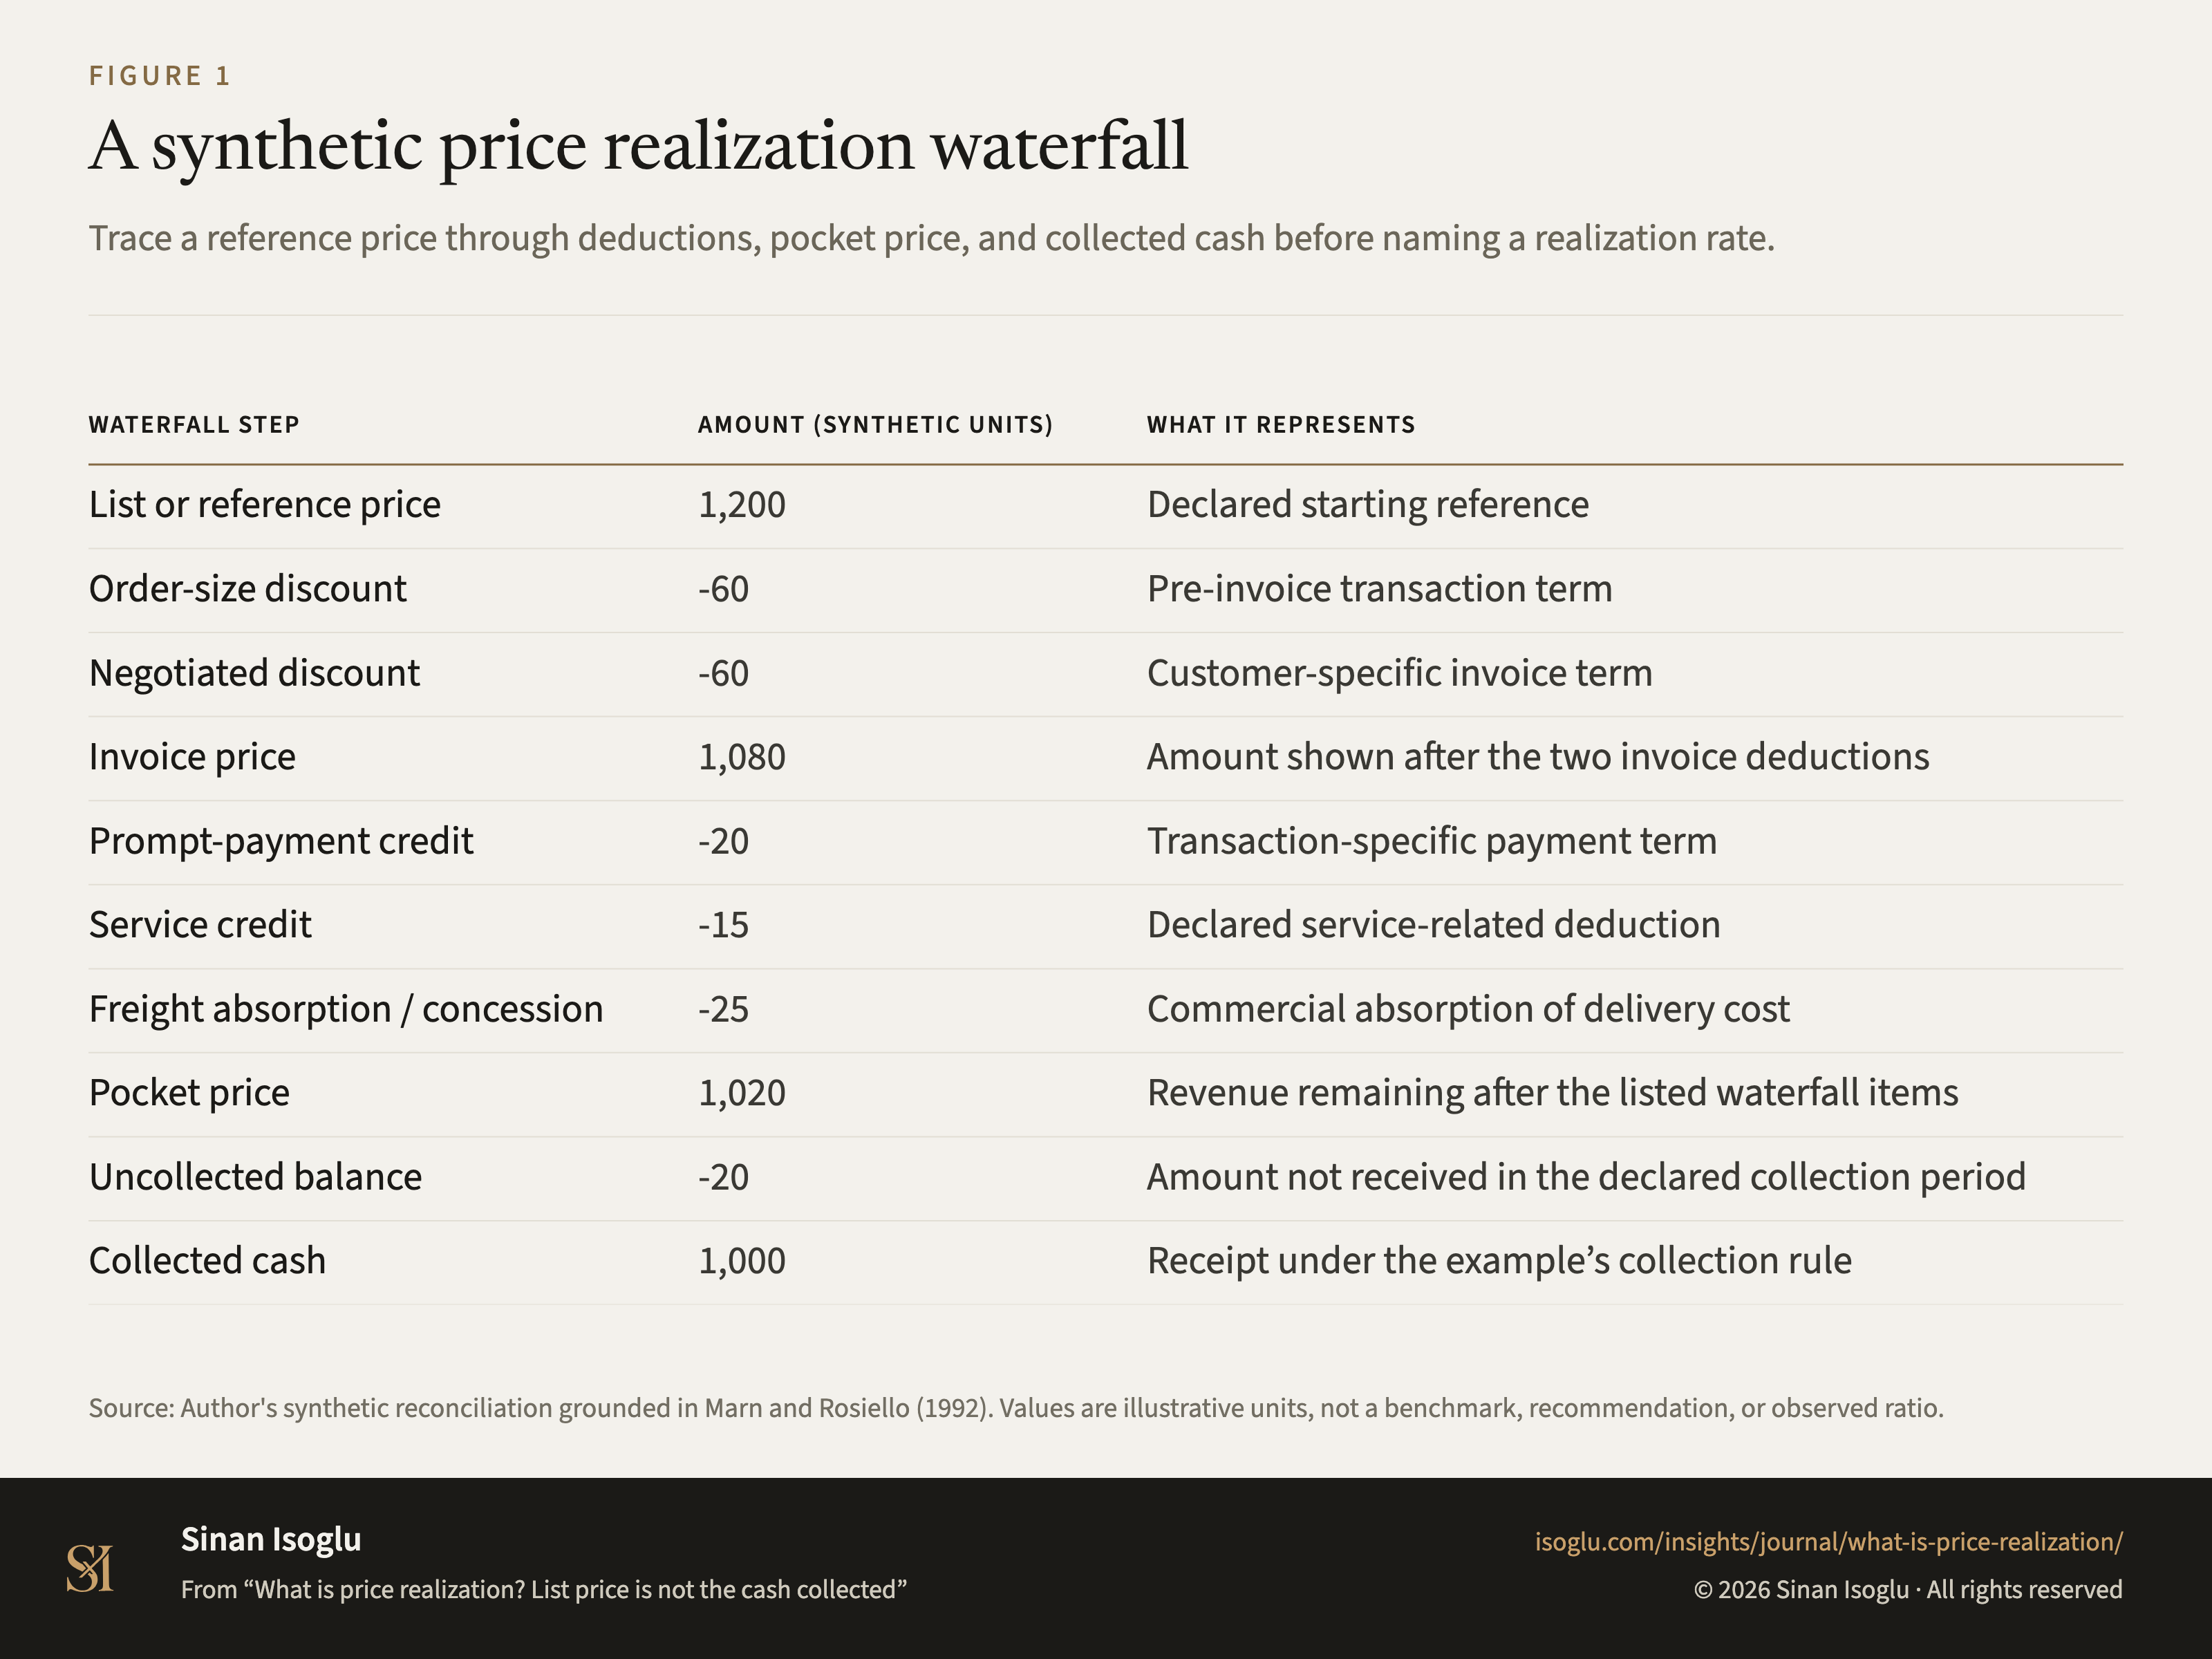
A synthetic price realization waterfall
Trace a reference price through deductions, pocket price, and collected cash before naming a realization rate.
Figure 1A synthetic price realization waterfall
| Waterfall step | Amount (synthetic units) | What it represents |
|---|---|---|
| List or reference price | 1,200 | Declared starting reference |
| Order-size discount | -60 | Pre-invoice transaction term |
| Negotiated discount | -60 | Customer-specific invoice term |
| Invoice price | 1,080 | Amount shown after the two invoice deductions |
| Prompt-payment credit | -20 | Transaction-specific payment term |
| Service credit | -15 | Declared service-related deduction |
| Freight absorption / concession | -25 | Commercial absorption of delivery cost |
| Pocket price | 1,020 | Revenue remaining after the listed waterfall items |
| Uncollected balance | -20 | Amount not received in the declared collection period |
| Collected cash | 1,000 | Receipt under the example's collection rule |
Swipe or scroll horizontally if the table is wider than your screen.
Source: Author's synthetic reconciliation grounded in Marn and Rosiello (1992). Values are illustrative units, not a benchmark, recommendation, or observed ratio.
Source and evidence
Each line names a claim related to this exhibit, its source, and how it was checked.
- A T01-MR92-C1 Marn and Rosiello make net realized price for each order or transaction the object of transaction price managementMarn and Rosiello (1992), full-text receipt
- A T01-MR92-C2 Their pocket-price waterfall moves from list price through invoice price and transaction-specific deductions to pocket priceMarn and Rosiello (1992), full-text receipt
- A T01-MR92-C3 Prompt-payment discounts, annual or retroactive volume rebates, cooperative advertising or marketing allowances, freight, and other items can sit after invoice price in the waterfallMarn and Rosiello (1992), full-text receipt
- B T01-OWN-C2 List or reference price, invoice price, pocket price, and collected cash answer different questionsAuthor taxonomy
- B T01-OWN-C4 The synthetic example produces 90.0% invoice-to-list, 85.0% pocket-price-to-list, 94.4% pocket-to-invoice, and 98.0% cash-to-pocket ratesAuthor synthetic arithmetic
Grades: A, verified against the printed page of the primary source · B, primary source, text layer only · C, authoritative secondary · D, reported.
From the essay
Pricing & revenue architecture
What is price realization? List price is not the cash collected
Price realization shows what remains after transaction terms and deductions, but only a named denominator makes the rate interpretable.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Related exhibits
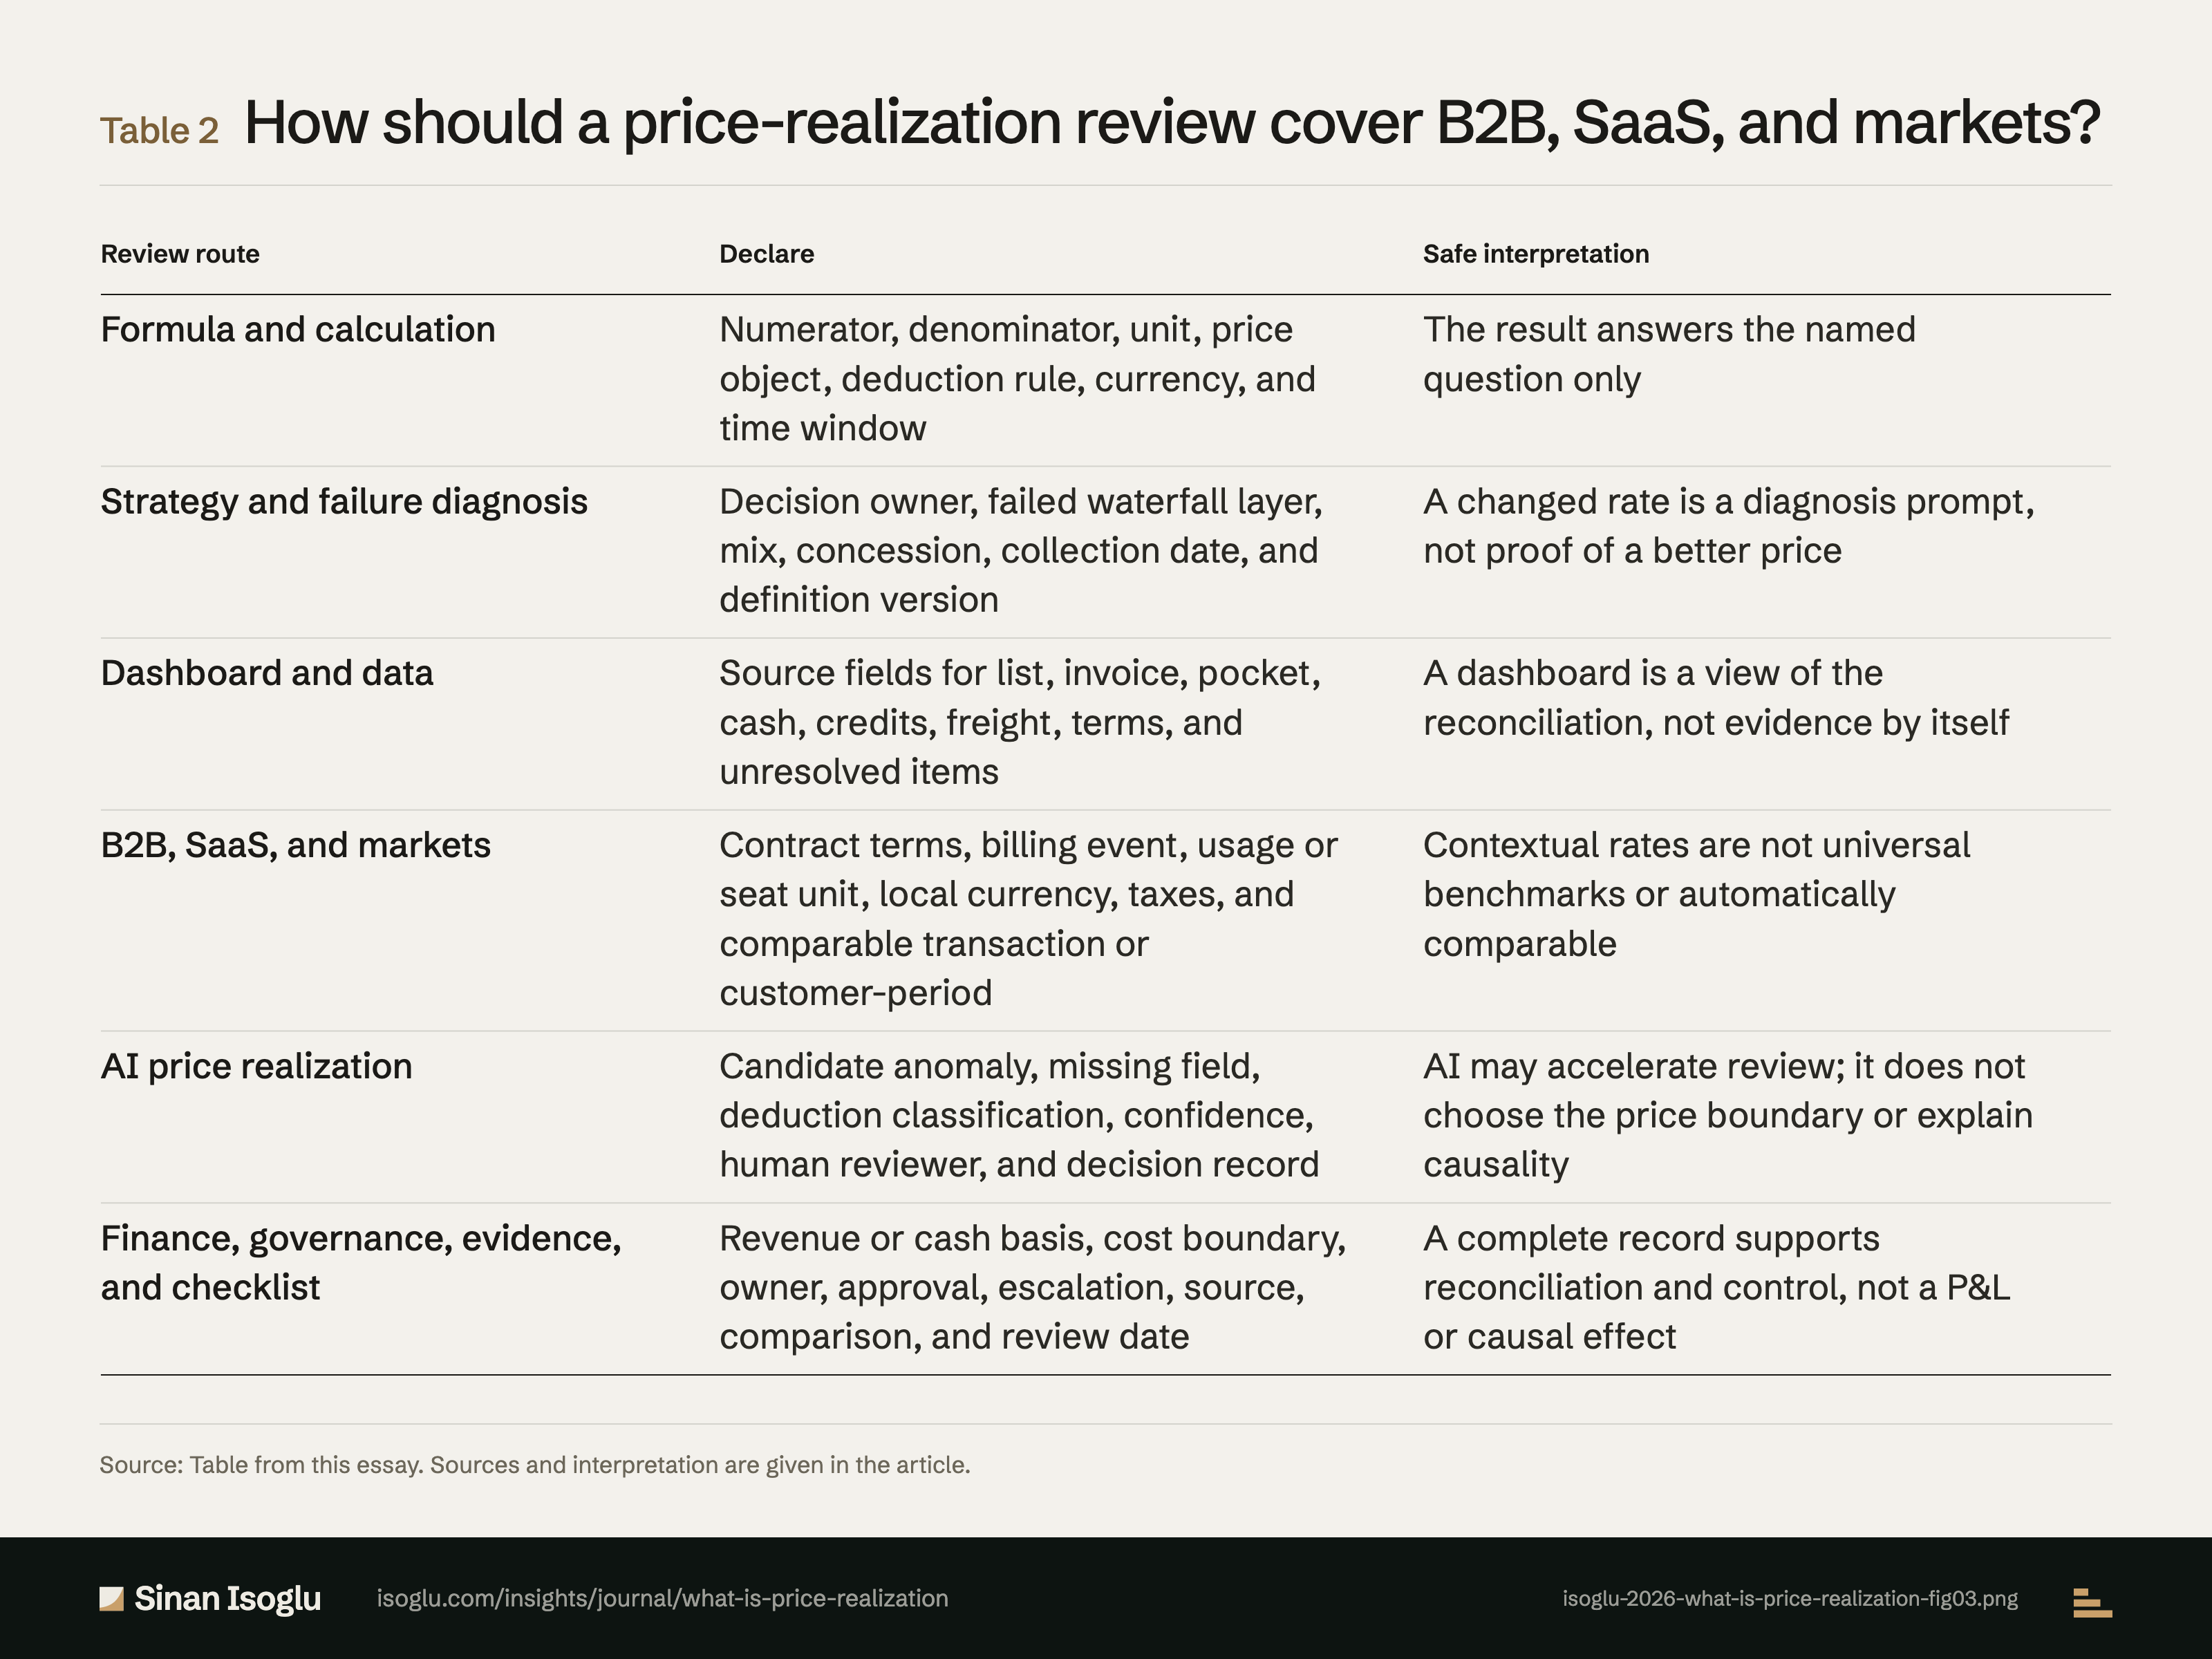
Table 2Table
How should a price-realization review cover B2B, SaaS, and markets?
What is price realization? List price is not the cash collected
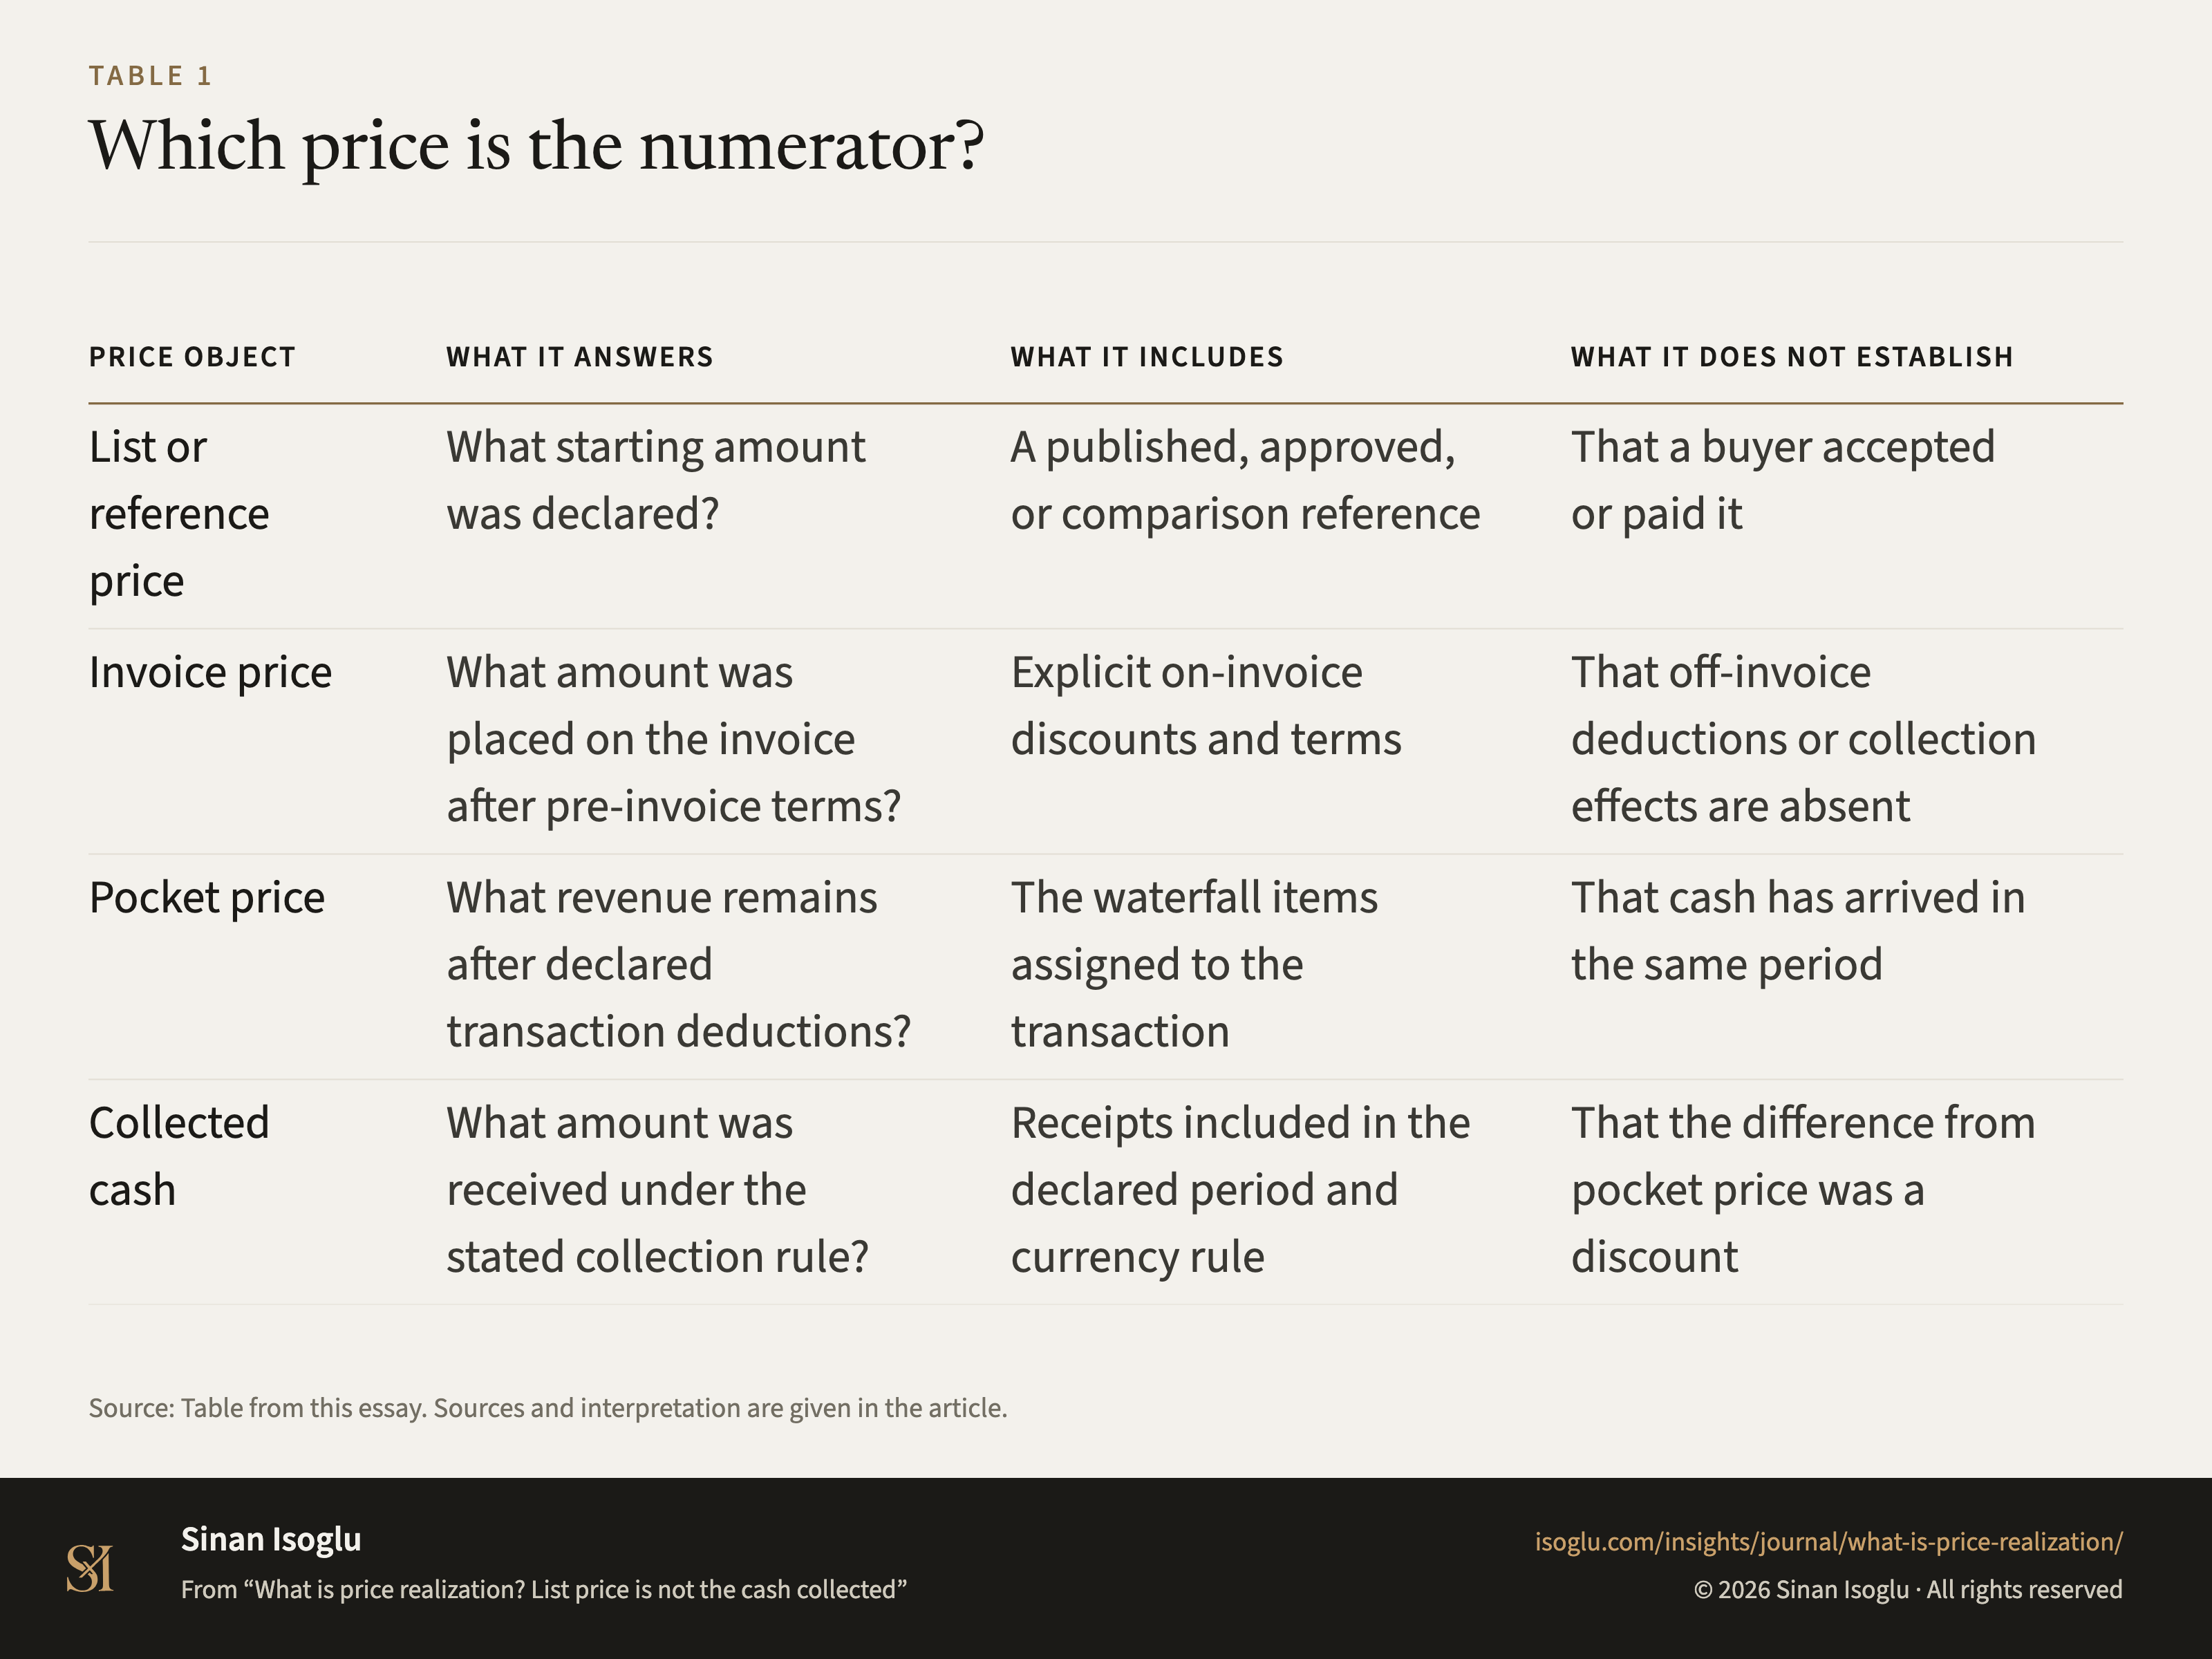
Table 1Table
Which price is the numerator?
What is price realization? List price is not the cash collected
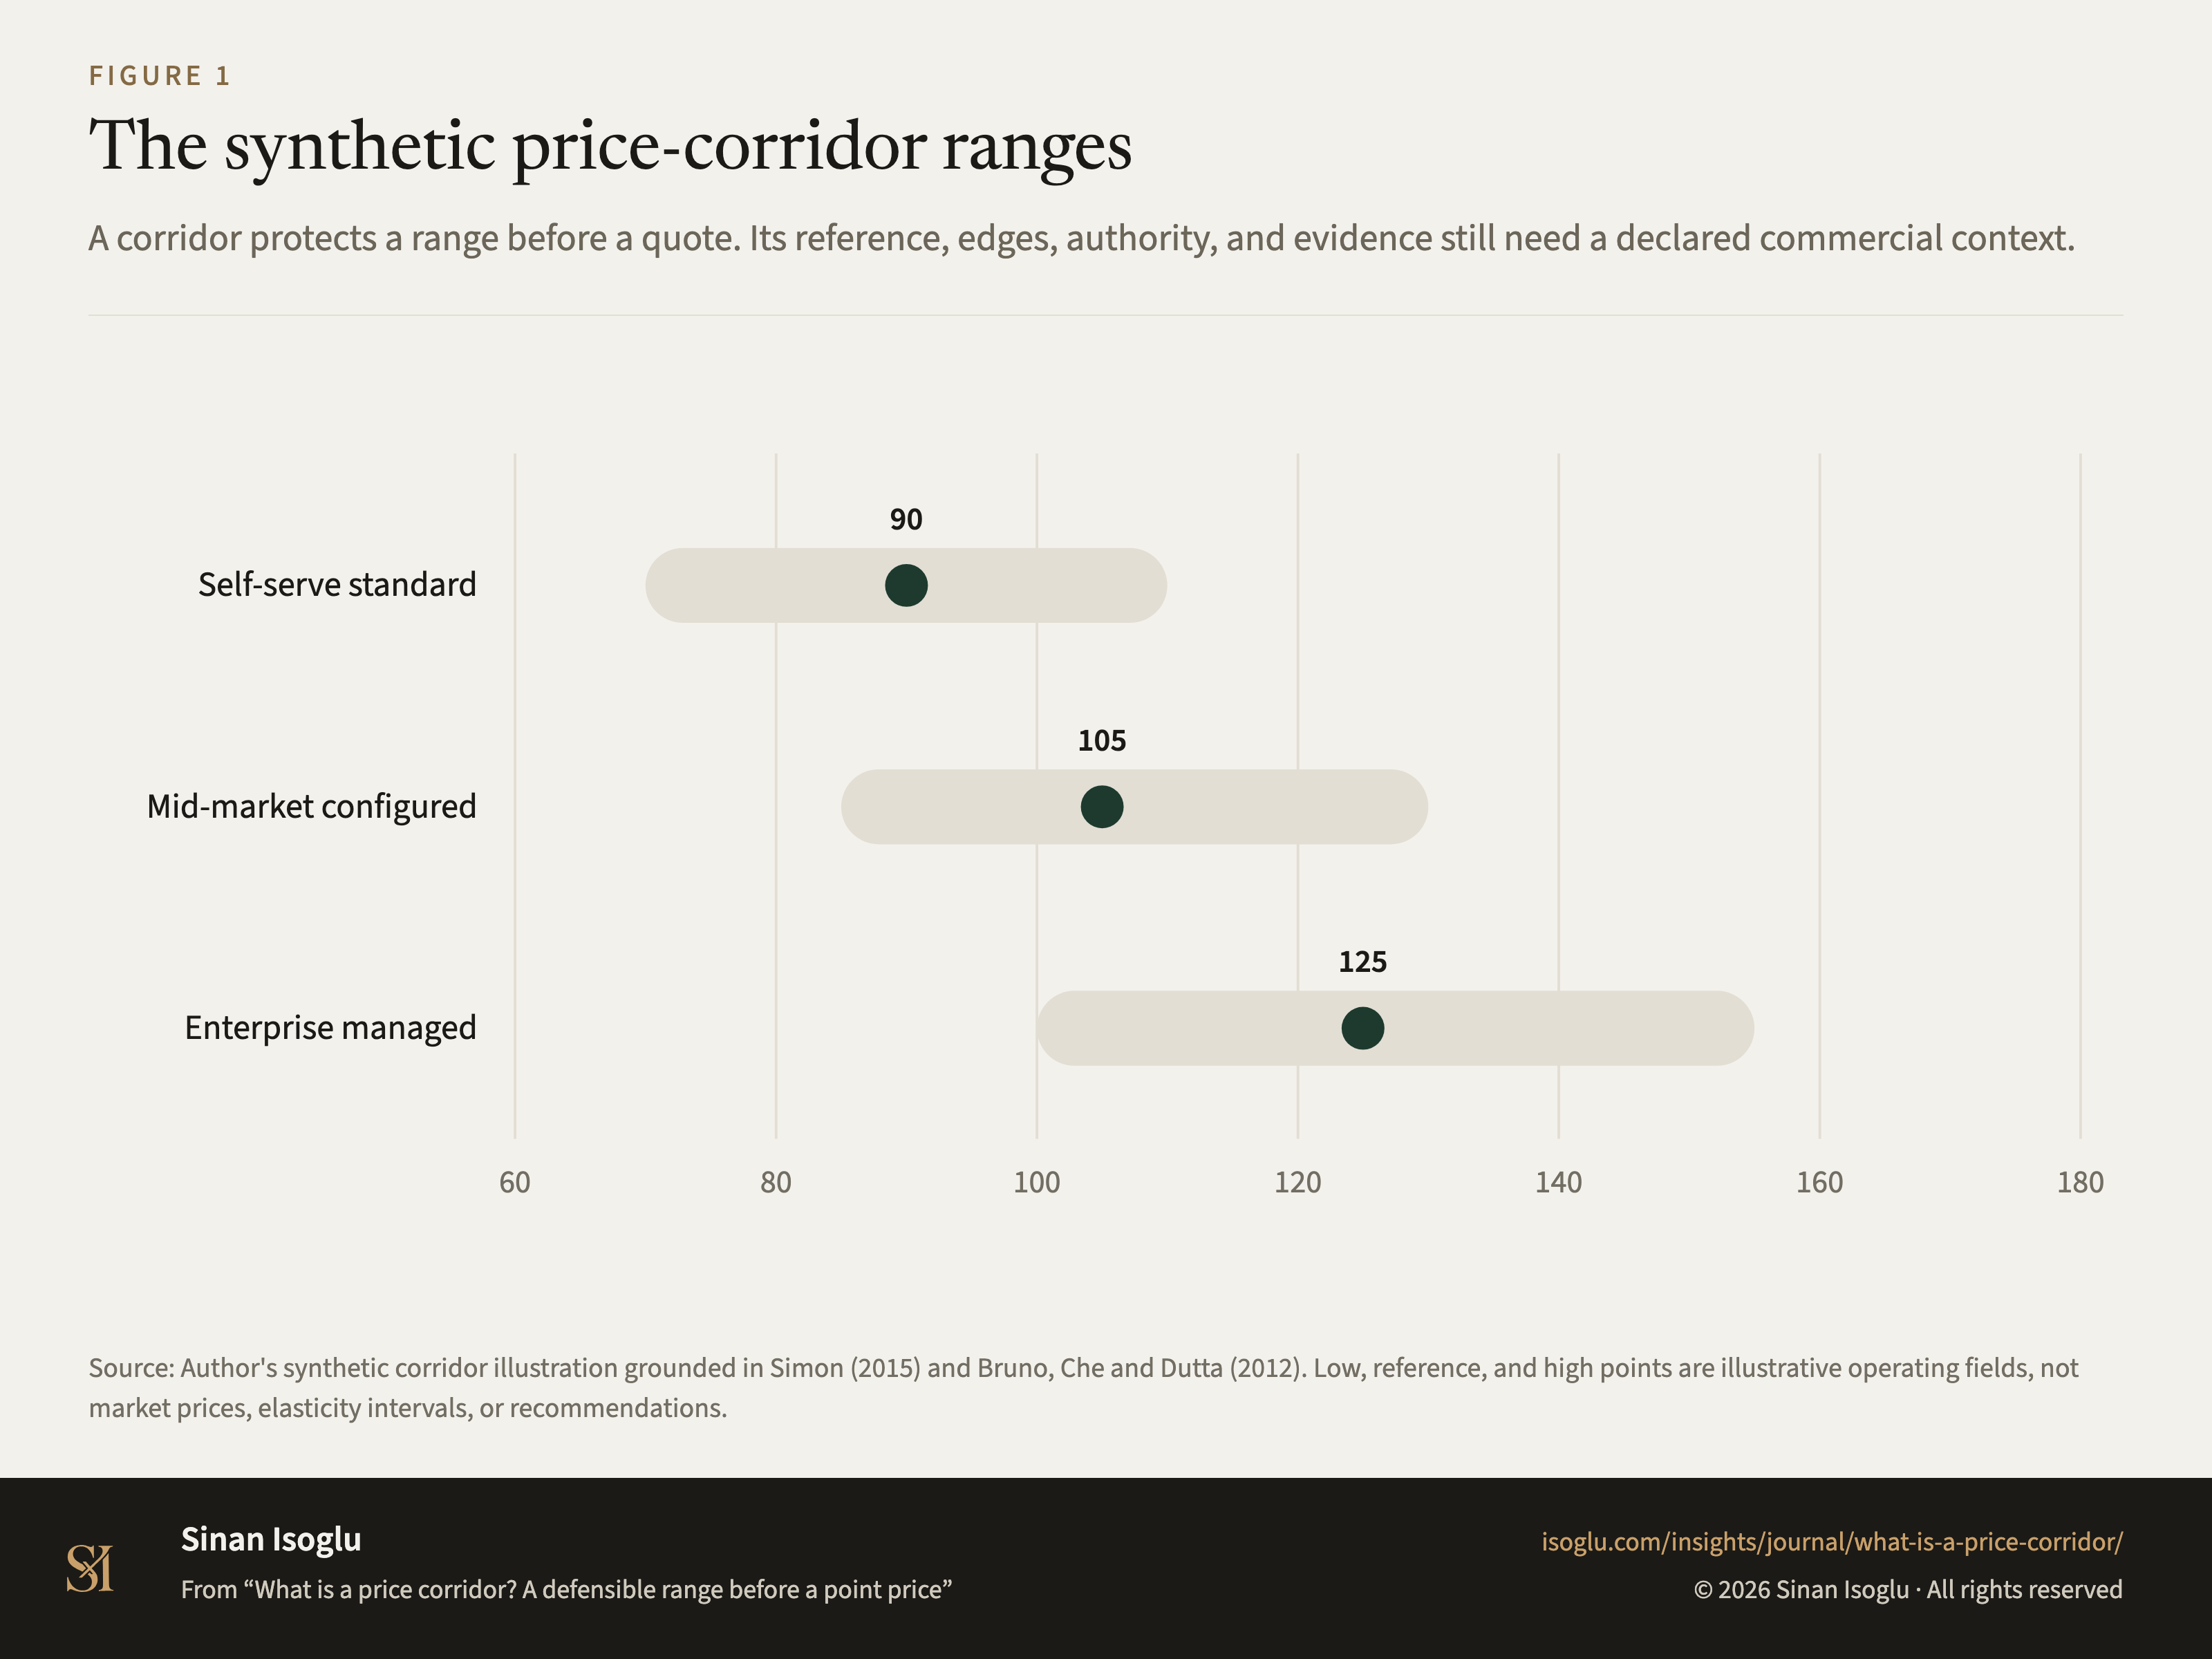
Figure 1Figure
The synthetic price-corridor ranges
What is a price corridor? A defensible range before a point price
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.