← Every exhibit
Table 1From “CAC payback is a cash calendar”
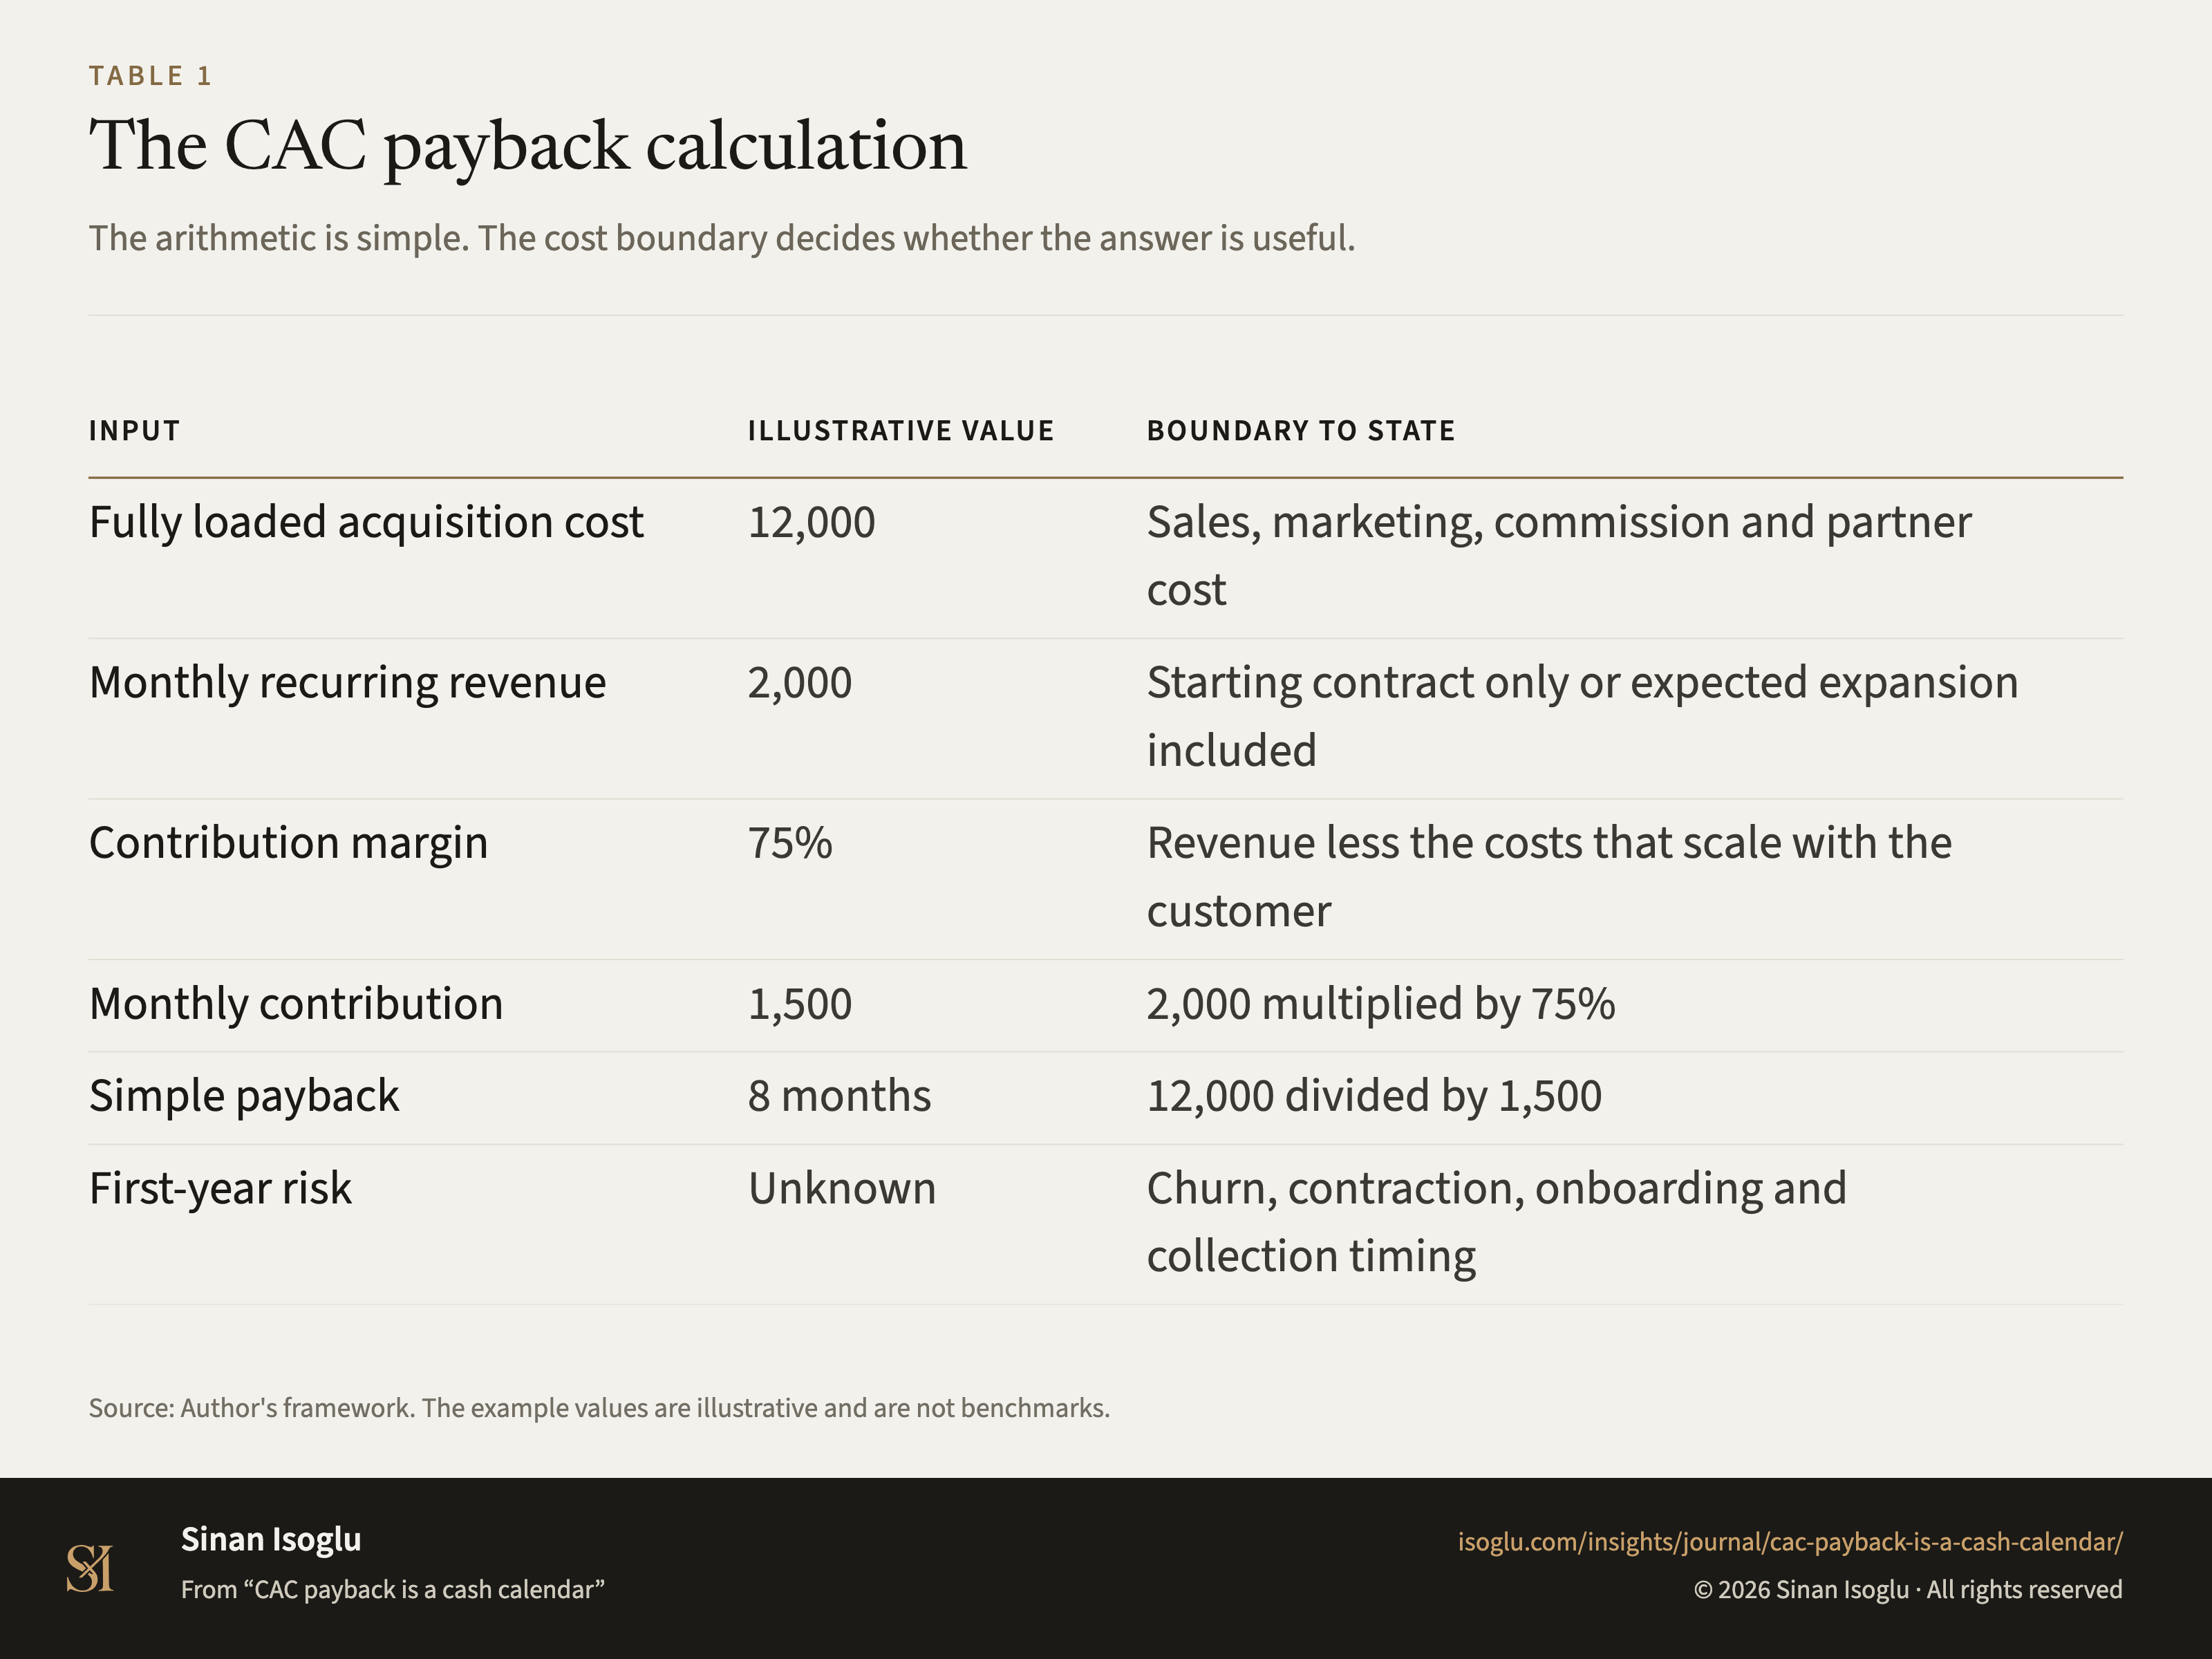
The CAC payback calculation
The arithmetic is simple. The cost boundary decides whether the answer is useful.
Table 1The CAC payback calculation
| Input | Illustrative value | Boundary to state |
|---|---|---|
| Fully loaded acquisition cost | 12,000 | Sales, marketing, commission and partner cost |
| Monthly recurring revenue | 2,000 | Starting contract only or expected expansion included |
| Contribution margin | 75% | Revenue less the costs that scale with the customer |
| Monthly contribution | 1,500 | 2,000 multiplied by 75% |
| Simple payback | 8 months | 12,000 divided by 1,500 |
| First-year risk | Unknown | Churn, contraction, onboarding and collection timing |
Swipe or scroll horizontally if the table is wider than your screen.
Source: Author's framework. The example values are illustrative and are not benchmarks.
PNG4:3, 1600 × 1200, with the title, the source line and the attribution set in the image isoglu-2026-cac-payback-is-a-cash-calendar-fig01.png
From the essay
Revenue operations & AI
CAC payback is a cash calendar
CAC payback period is the time needed to recover acquisition cost from contribution margin. Make the margin, cohort and cash boundary explicit.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.