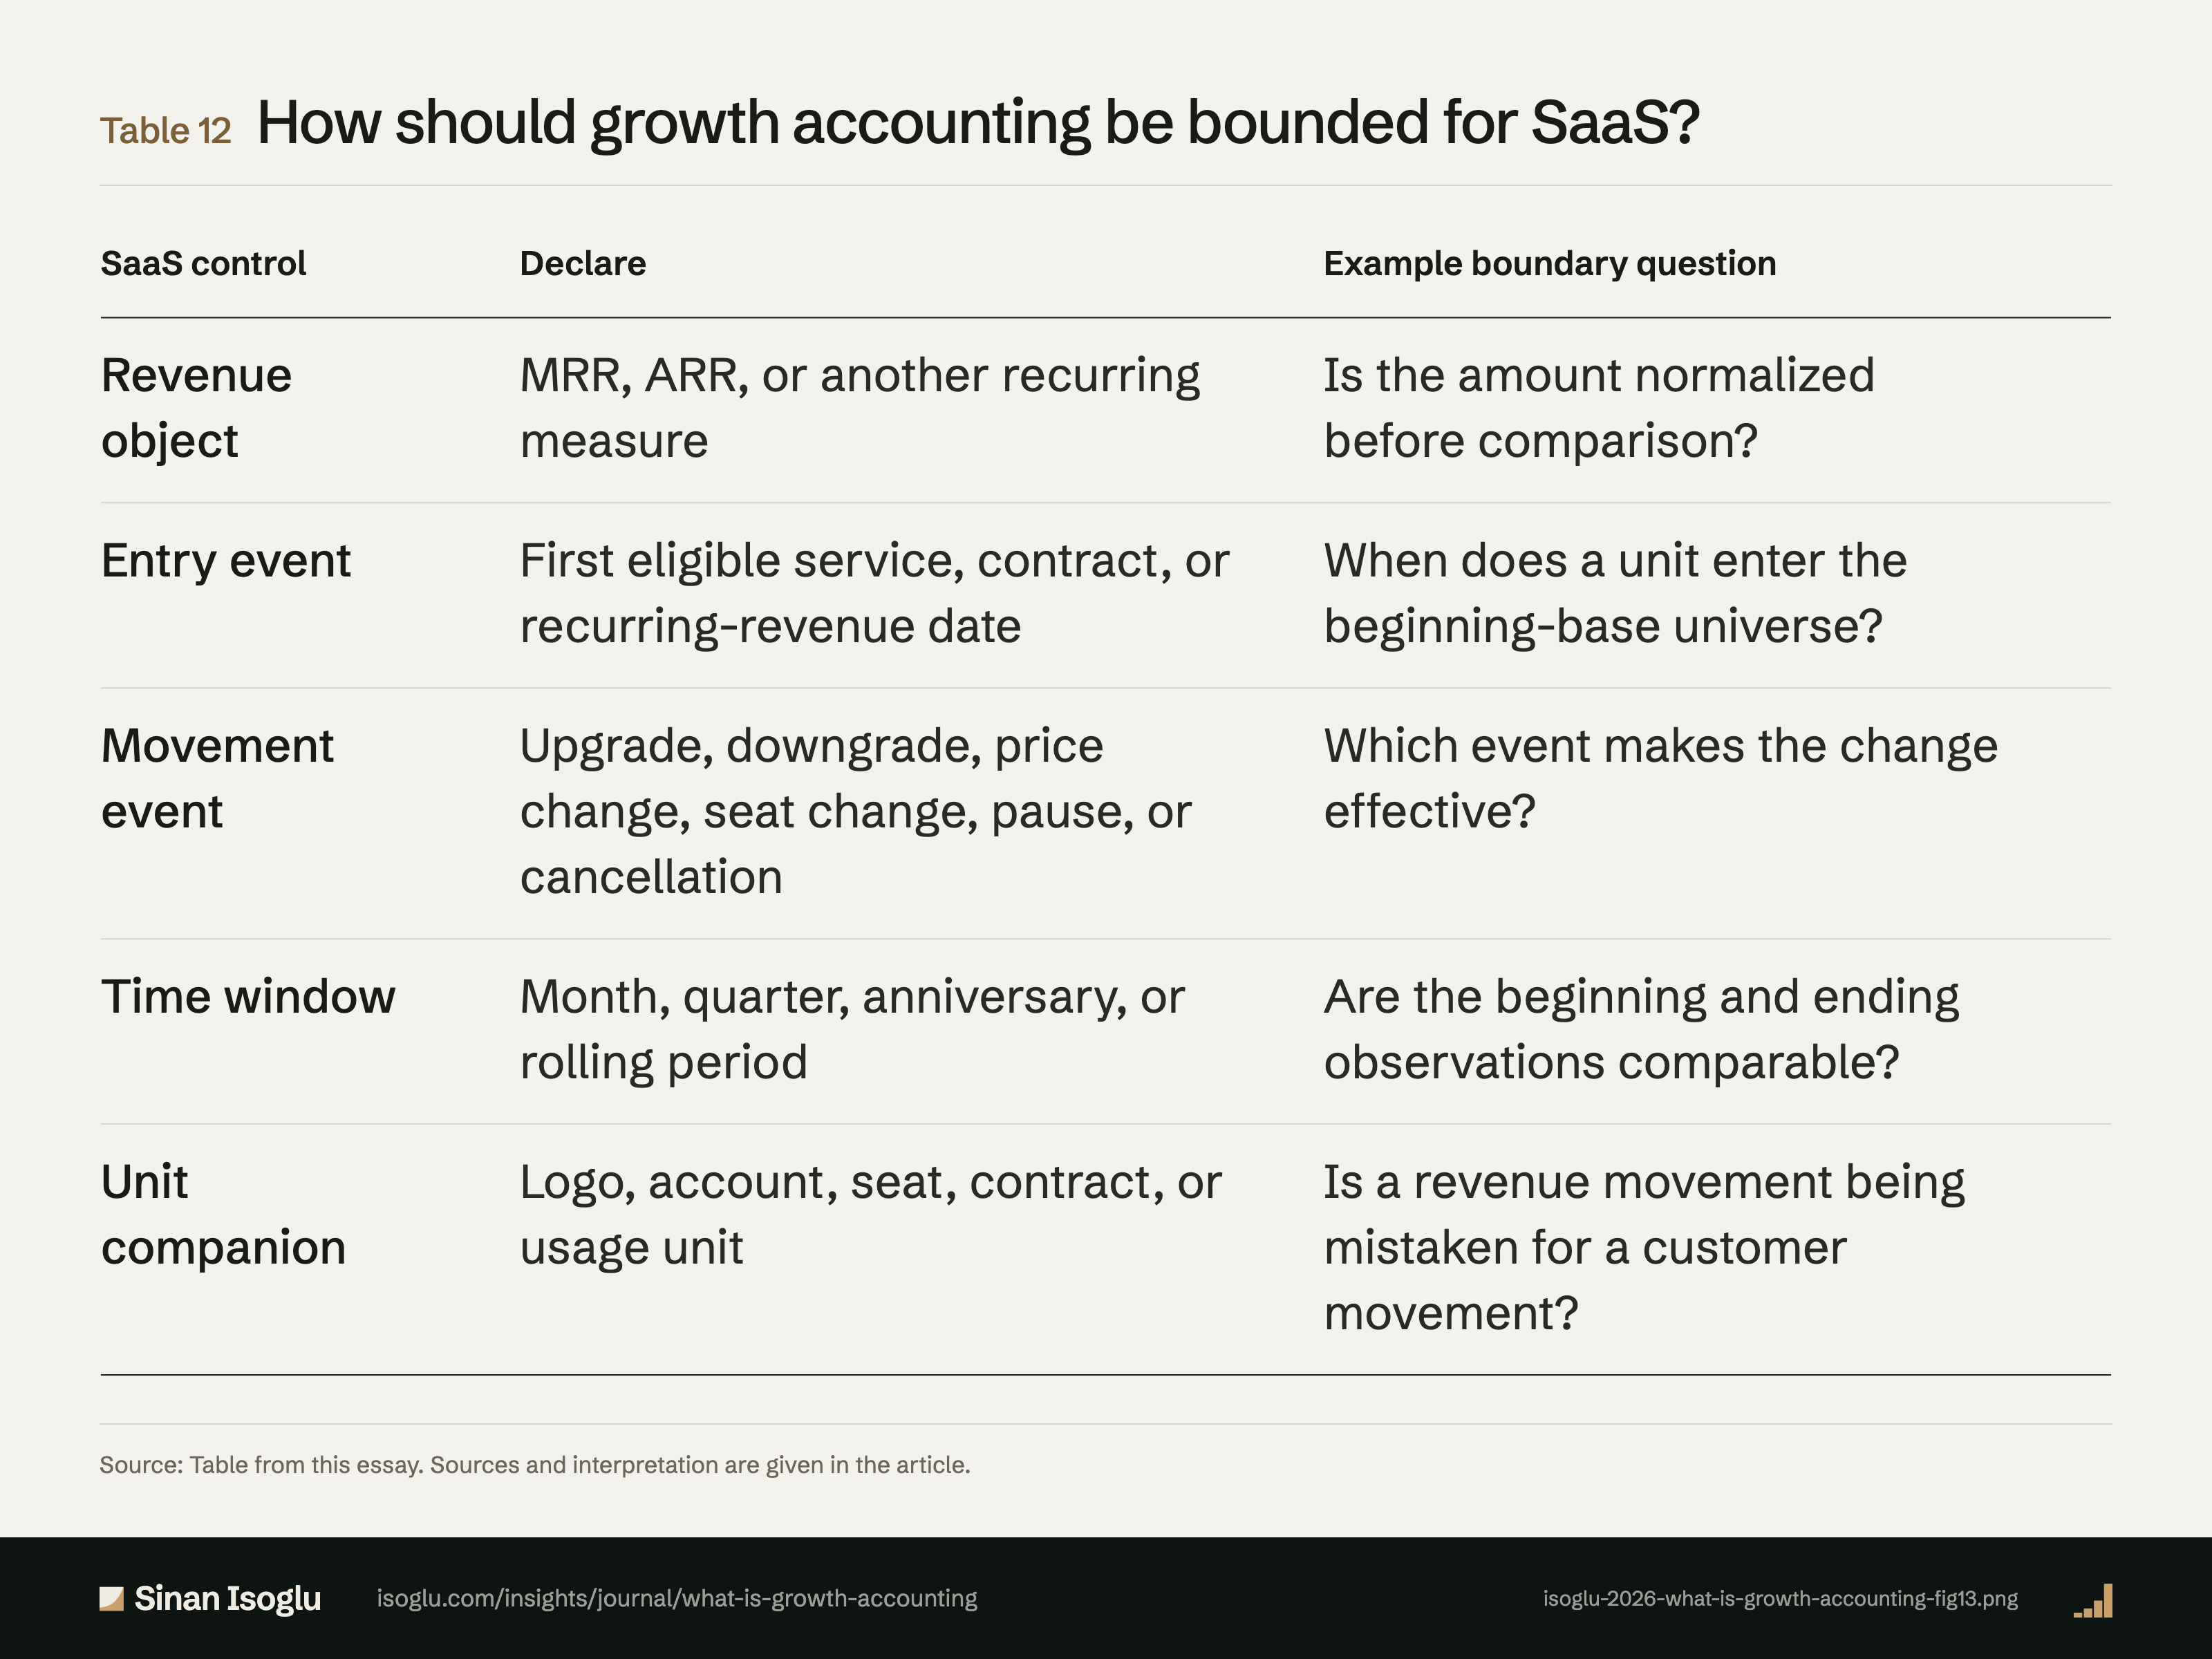
Table 12From “What is growth accounting? Separate new, retained, expanded, and lost revenue”
How should growth accounting be bounded for SaaS?
Table 12How should growth accounting be bounded for SaaS?
| SaaS control | Declare | Example boundary question |
|---|---|---|
| Revenue object | MRR, ARR, or another recurring measure | Is the amount normalized before comparison? |
| Entry event | First eligible service, contract, or recurring-revenue date | When does a unit enter the beginning-base universe? |
| Movement event | Upgrade, downgrade, price change, seat change, pause, or cancellation | Which event makes the change effective? |
| Time window | Month, quarter, anniversary, or rolling period | Are the beginning and ending observations comparable? |
| Unit companion | Logo, account, seat, contract, or usage unit | Is a revenue movement being mistaken for a customer movement? |
Swipe or scroll horizontally if the table is wider than your screen.
Source: Table from this essay. Sources and interpretation are given in the article.
From the essay
Growth that compounds
What is growth accounting? Separate new, retained, expanded, and lost revenue
Growth accounting reconciles recurring revenue through new, expanded, contracted, and lost components. Keep revenue and customer counts separate.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Related exhibits
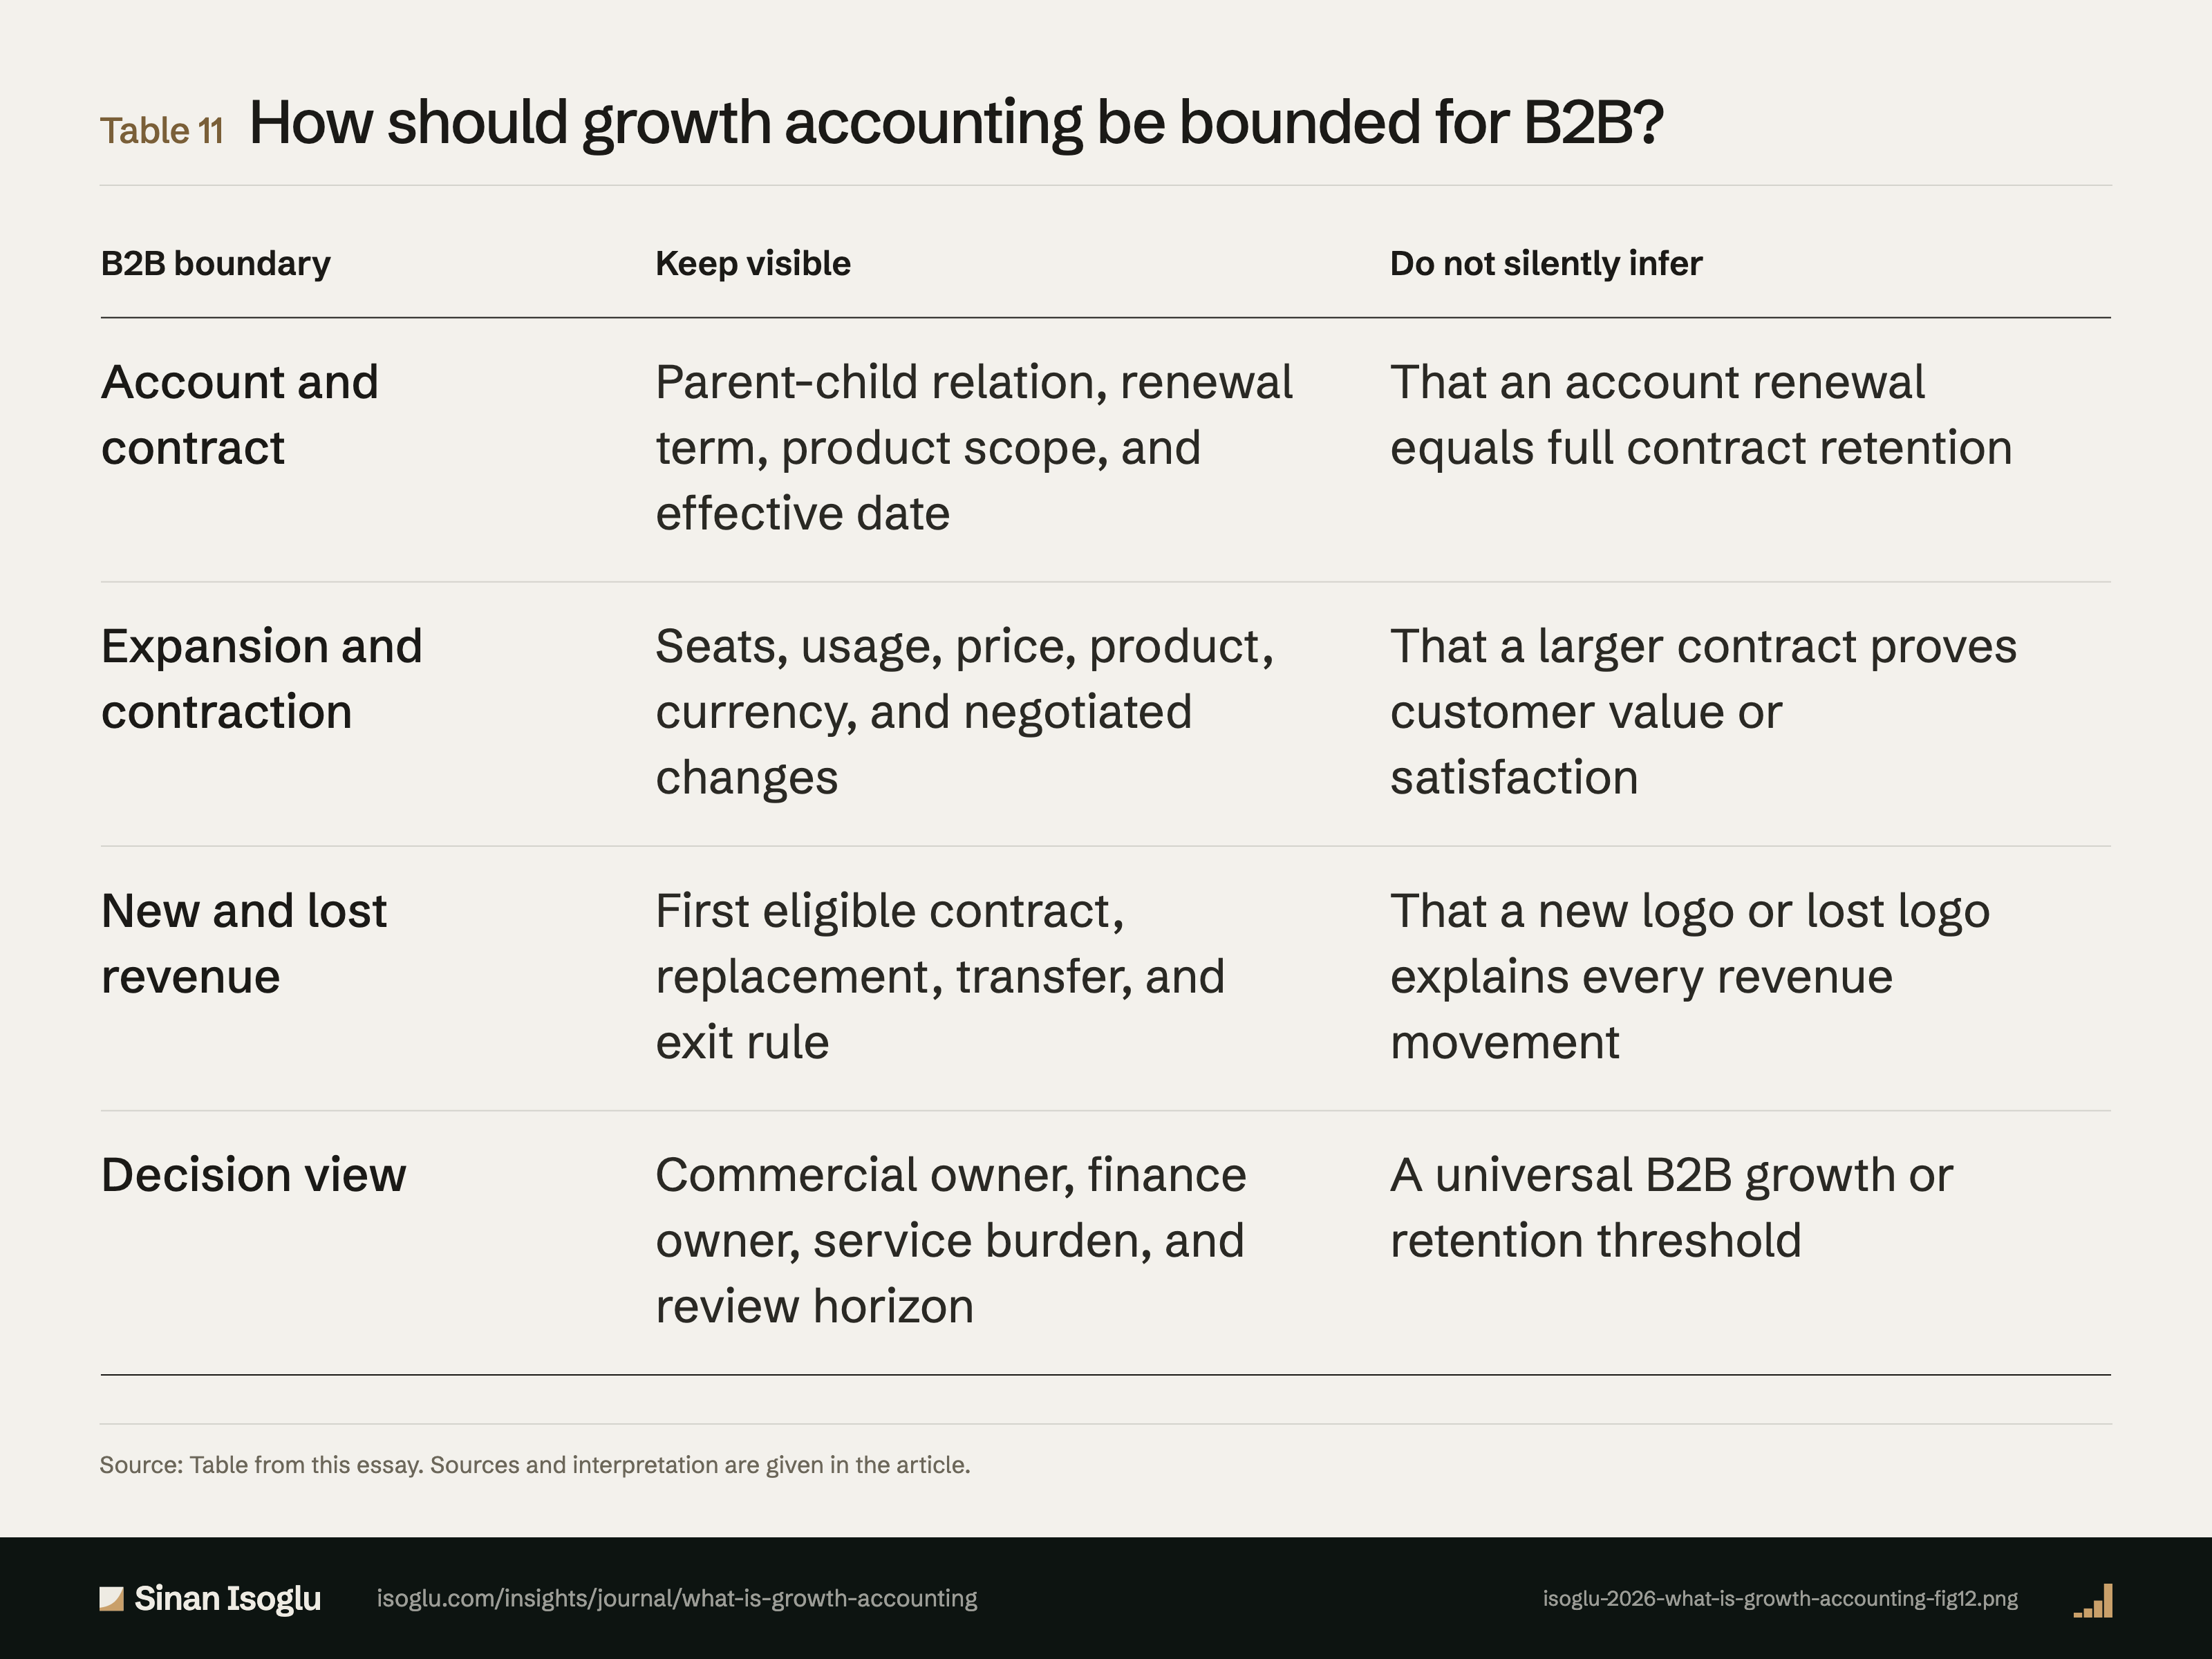
Table 11Table
How should growth accounting be bounded for B2B?
What is growth accounting? Separate new, retained, expanded, and lost revenue
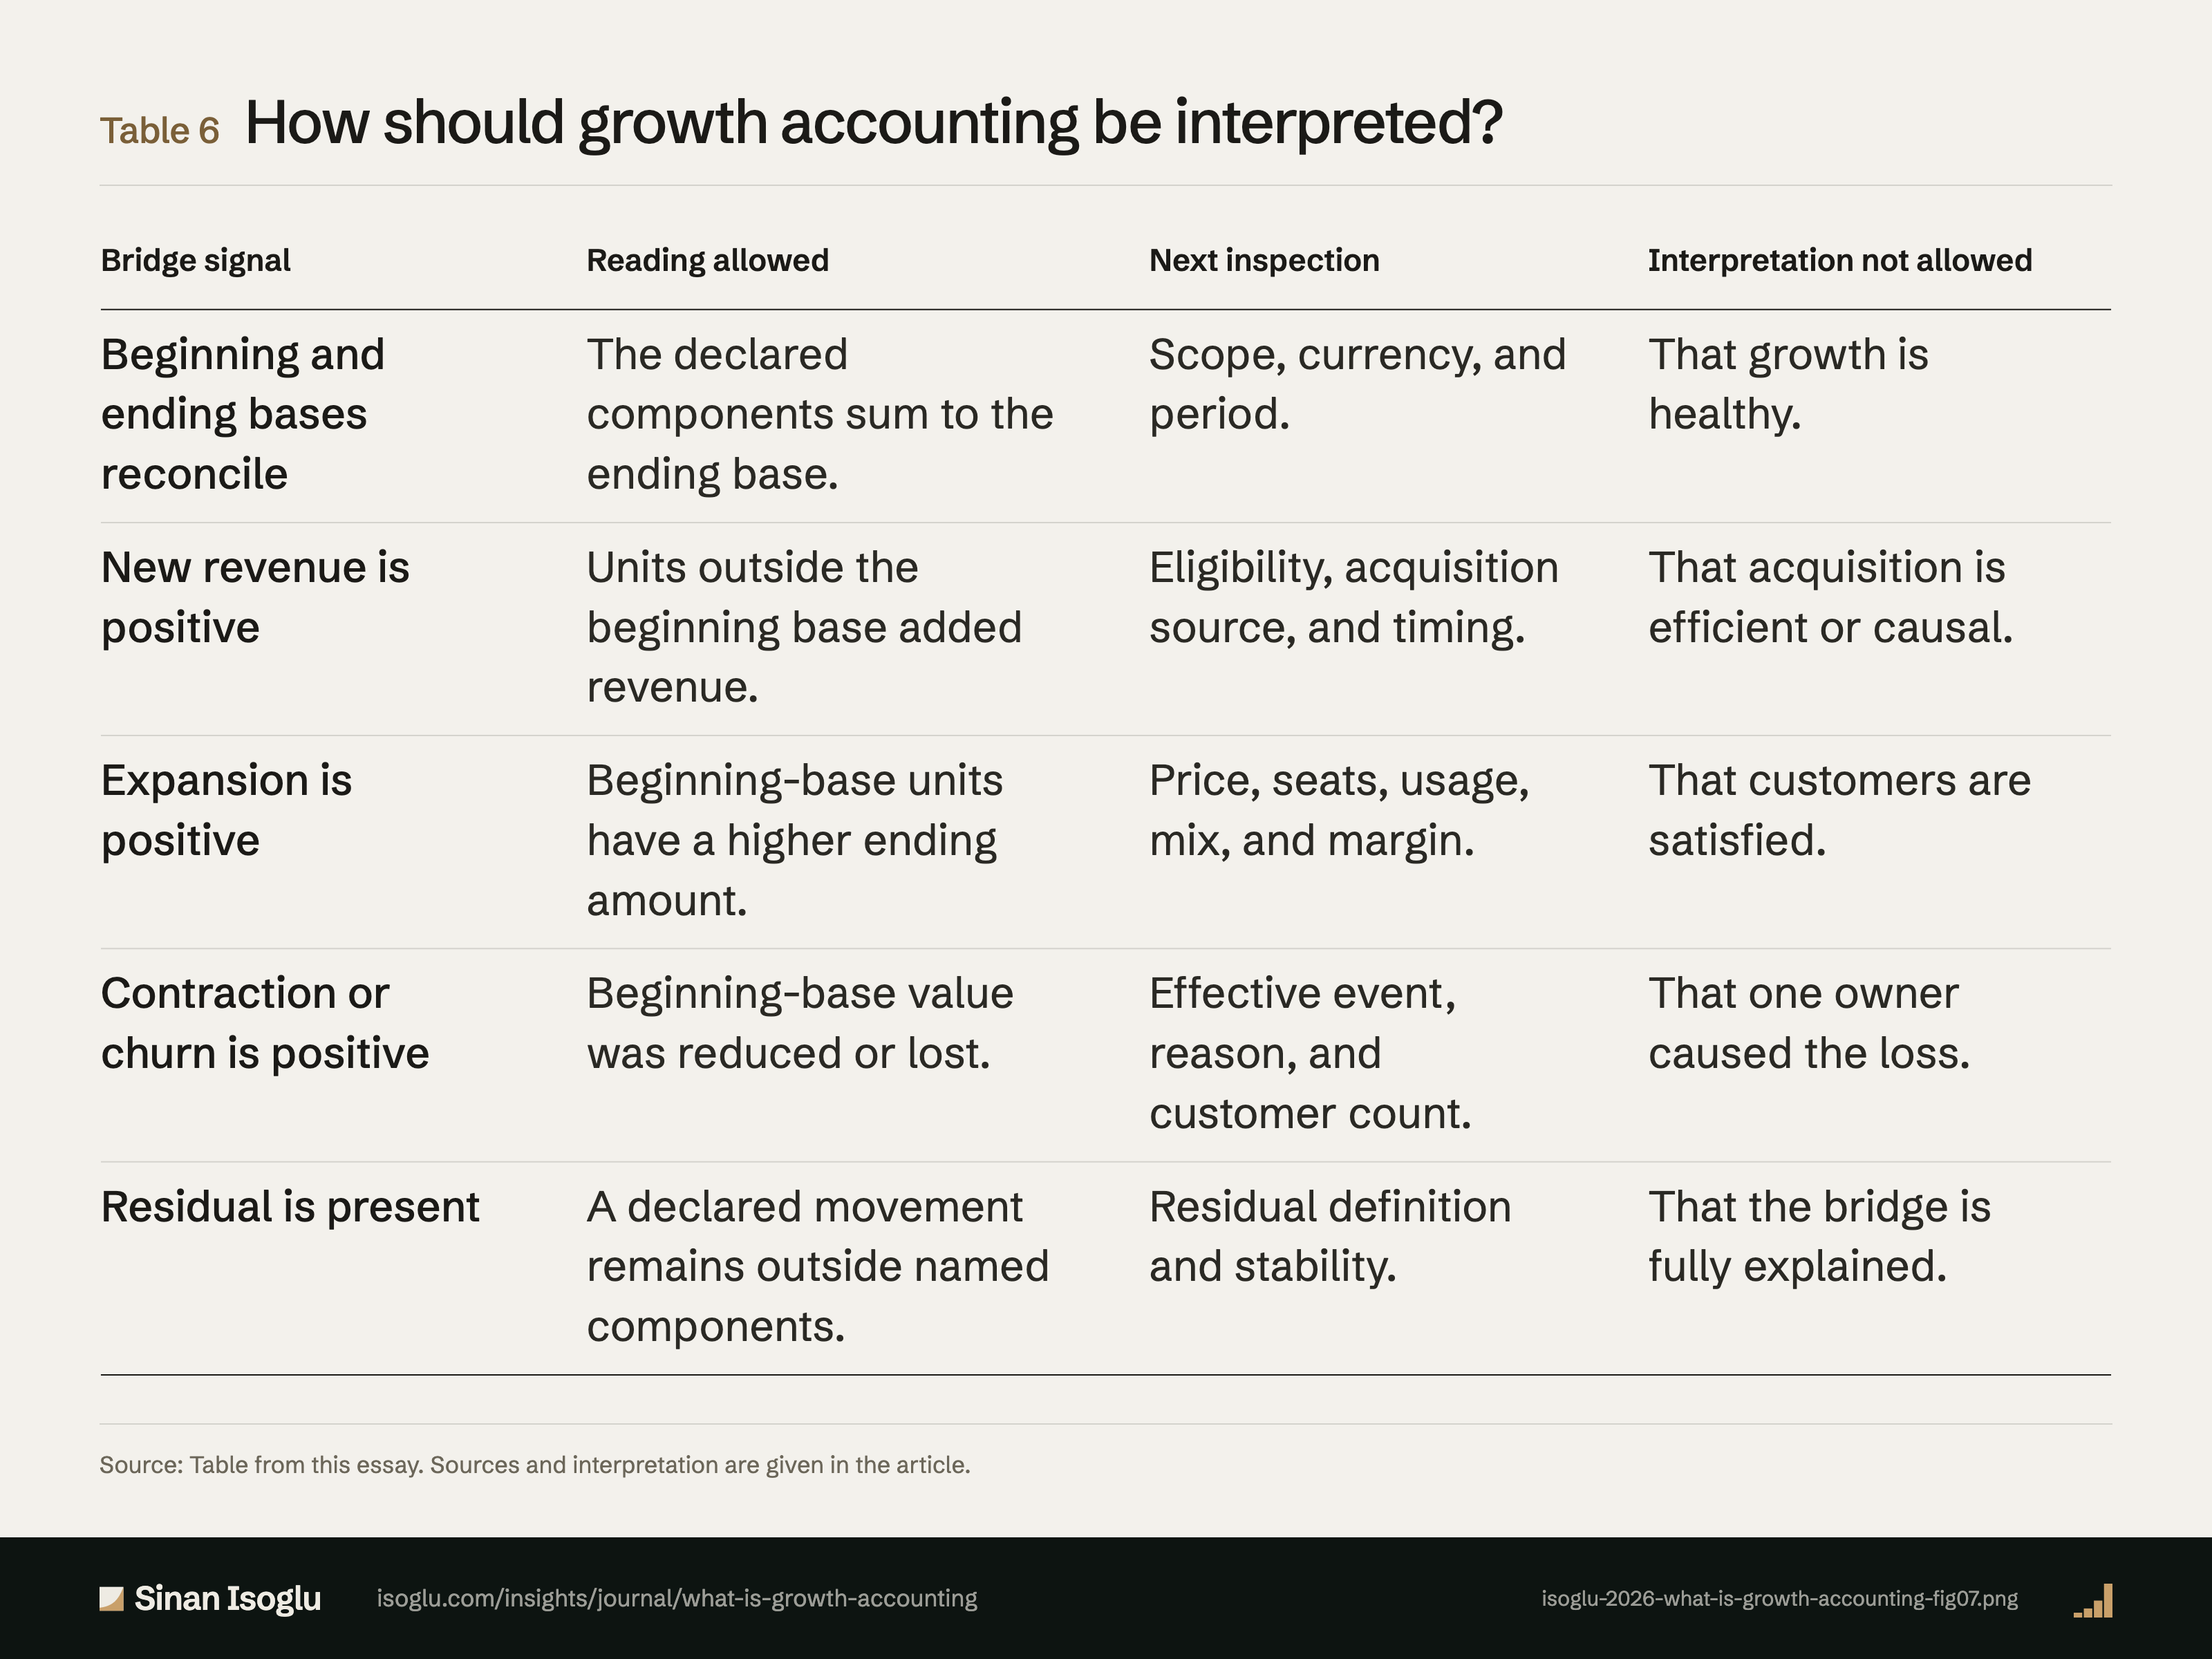
Table 6Table
How should growth accounting be interpreted?
What is growth accounting? Separate new, retained, expanded, and lost revenue
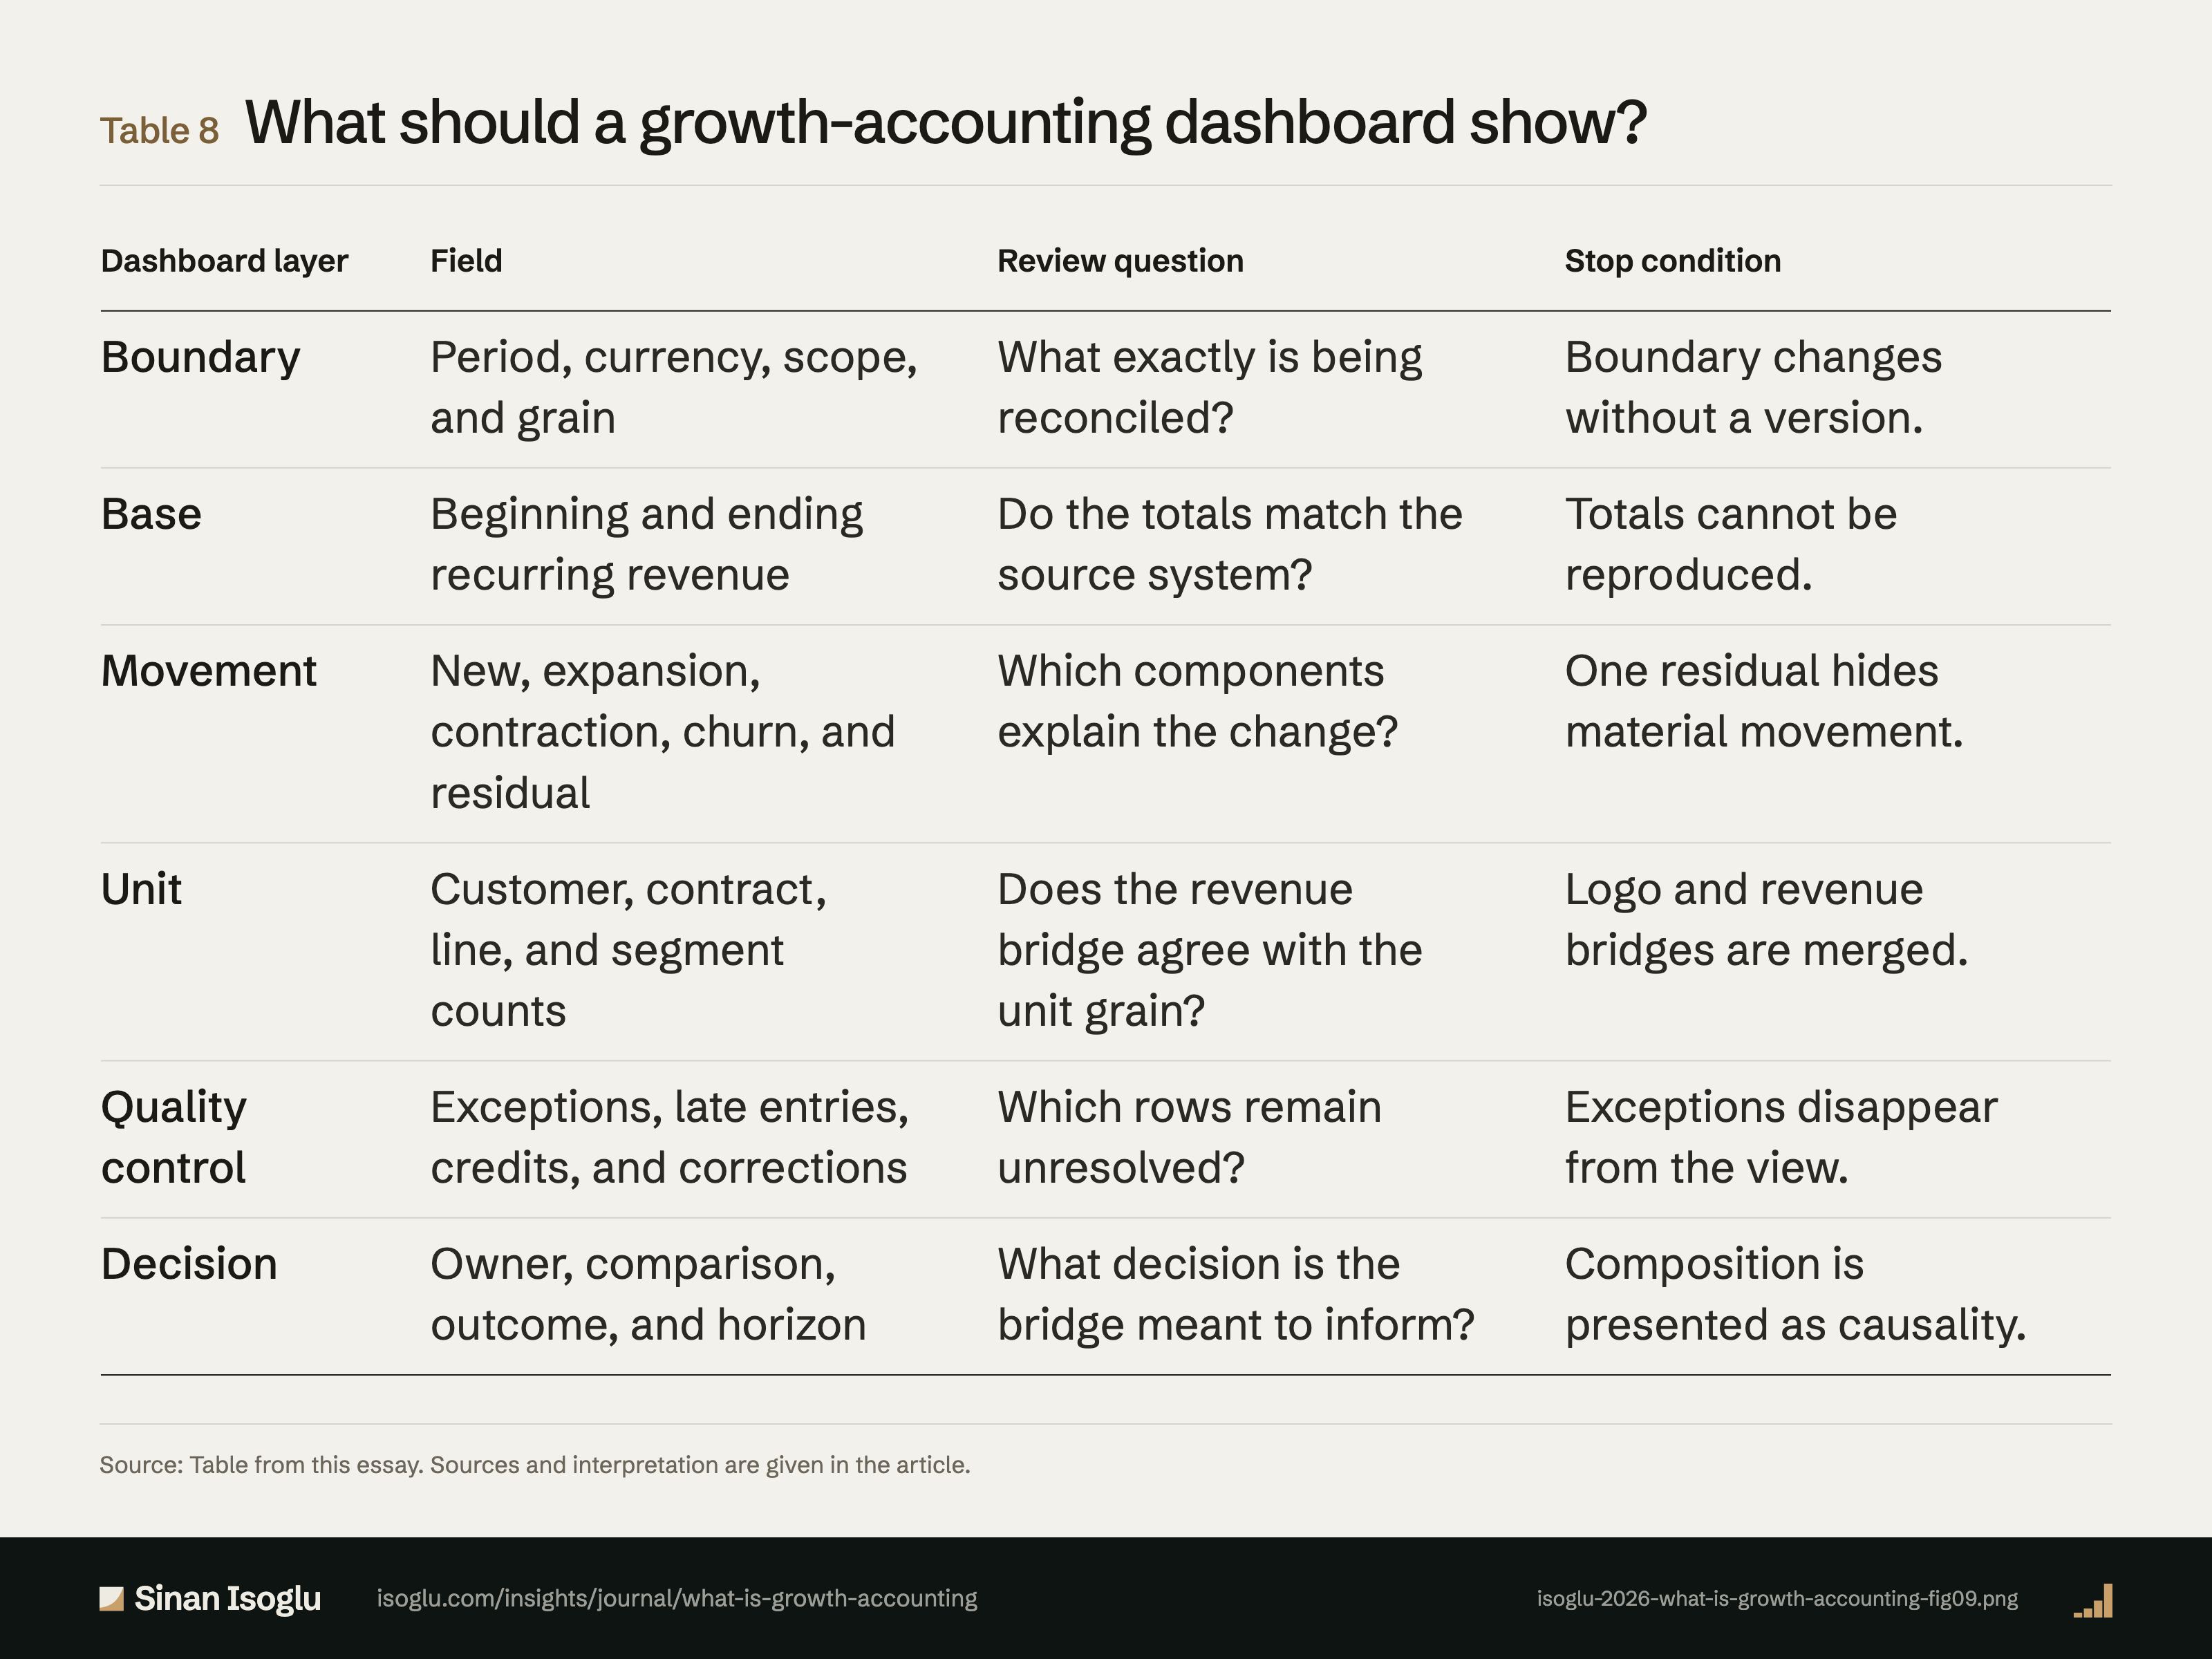
Table 8Table
What should a growth-accounting dashboard show?
What is growth accounting? Separate new, retained, expanded, and lost revenue
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.