← Every exhibit
Table 1From “What is contribution margin?”
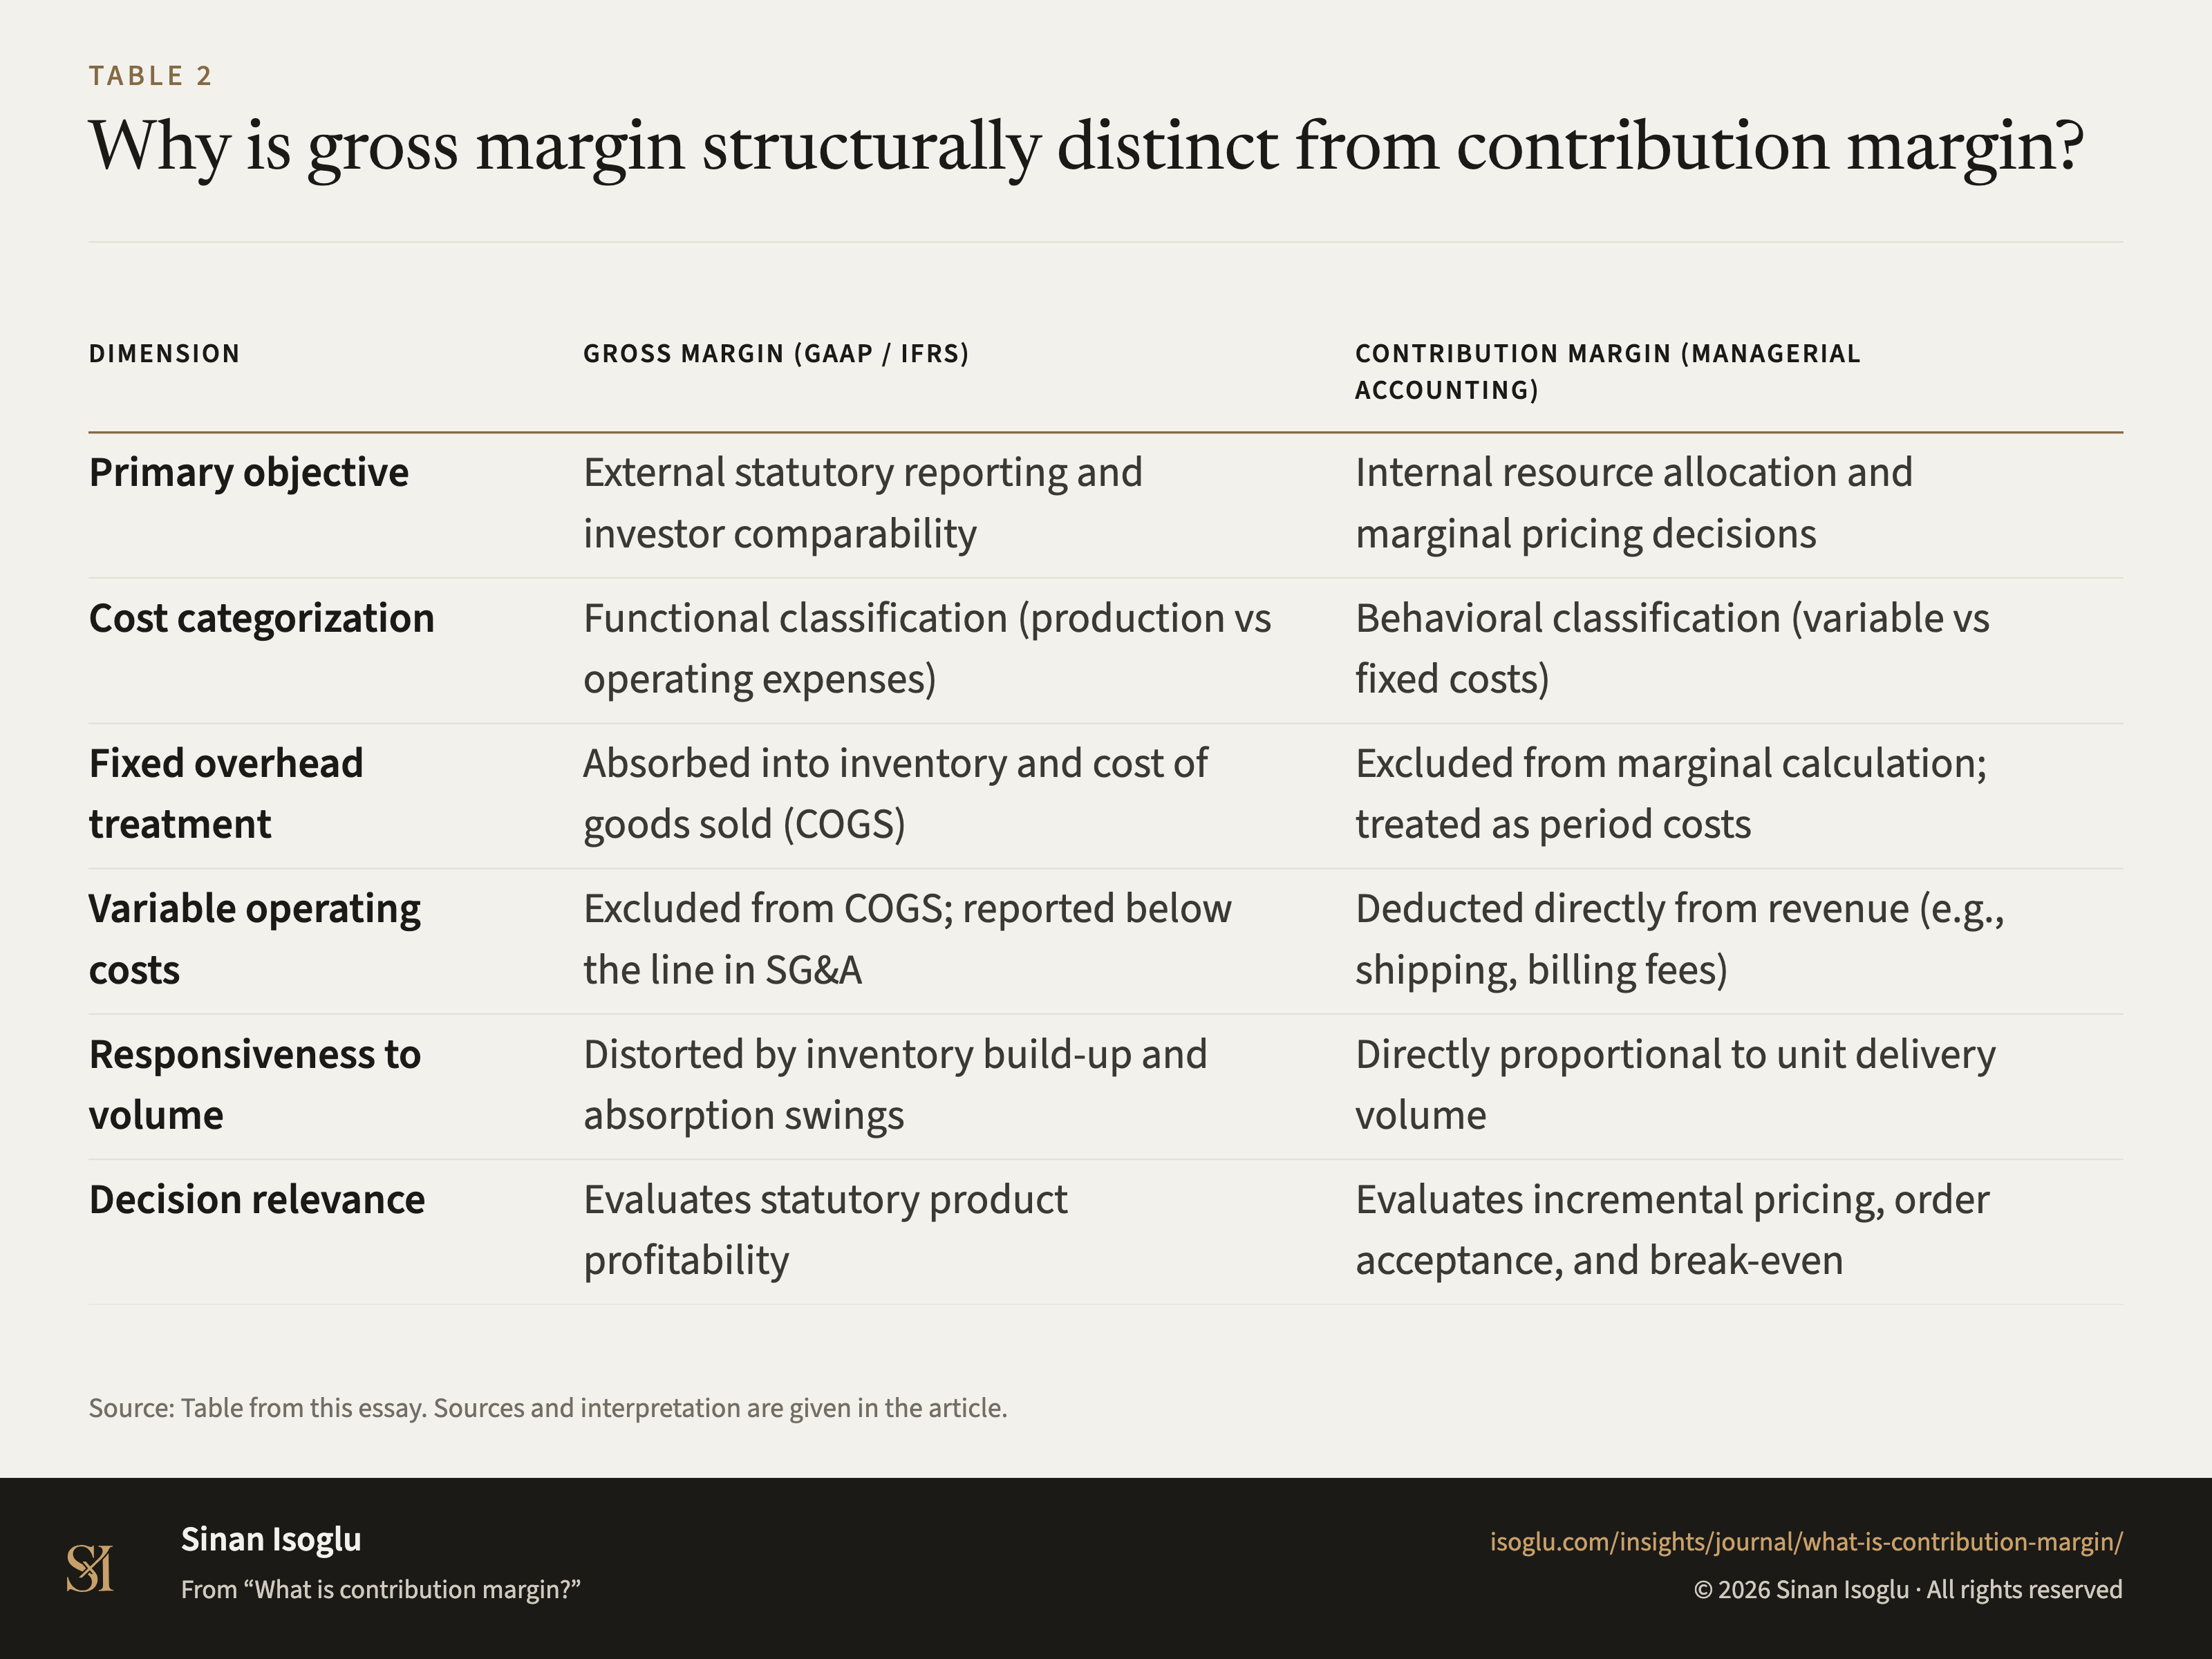
Why is gross margin structurally distinct from contribution margin?
Table 1Why is gross margin structurally distinct from contribution margin?
| Dimension | Gross margin (GAAP / IFRS) | Contribution margin (Managerial accounting) |
|---|---|---|
| Primary objective | External statutory reporting and investor comparability | Internal resource allocation and marginal pricing decisions |
| Cost categorization | Functional classification (production vs operating expenses) | Behavioral classification (variable vs fixed costs) |
| Fixed overhead treatment | Absorbed into inventory and cost of goods sold (COGS) | Excluded from marginal calculation; treated as period costs |
| Variable operating costs | Excluded from COGS; reported below the line in SG&A | Deducted directly from revenue (e.g., shipping, billing fees) |
| Responsiveness to volume | Distorted by inventory build-up and absorption swings | Directly proportional to unit delivery volume |
| Decision relevance | Evaluates statutory product profitability | Evaluates incremental pricing, order acceptance, and break-even |
Swipe or scroll horizontally if the table is wider than your screen.
Source: Table from this essay. Sources and interpretation are given in the article.
PNG4:3, 1600 × 1200, with the title, the source line and the attribution set in the image isoglu-2026-what-is-contribution-margin-fig02.png
From the essay
Revenue operations & AI
What is contribution margin?
Contribution margin isolates revenue minus variable costs to determine how incremental volume covers fixed overhead and generates operating profit.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Related exhibits
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.