Table 1From “Variable pay is a risk design when effort is hard to observe”
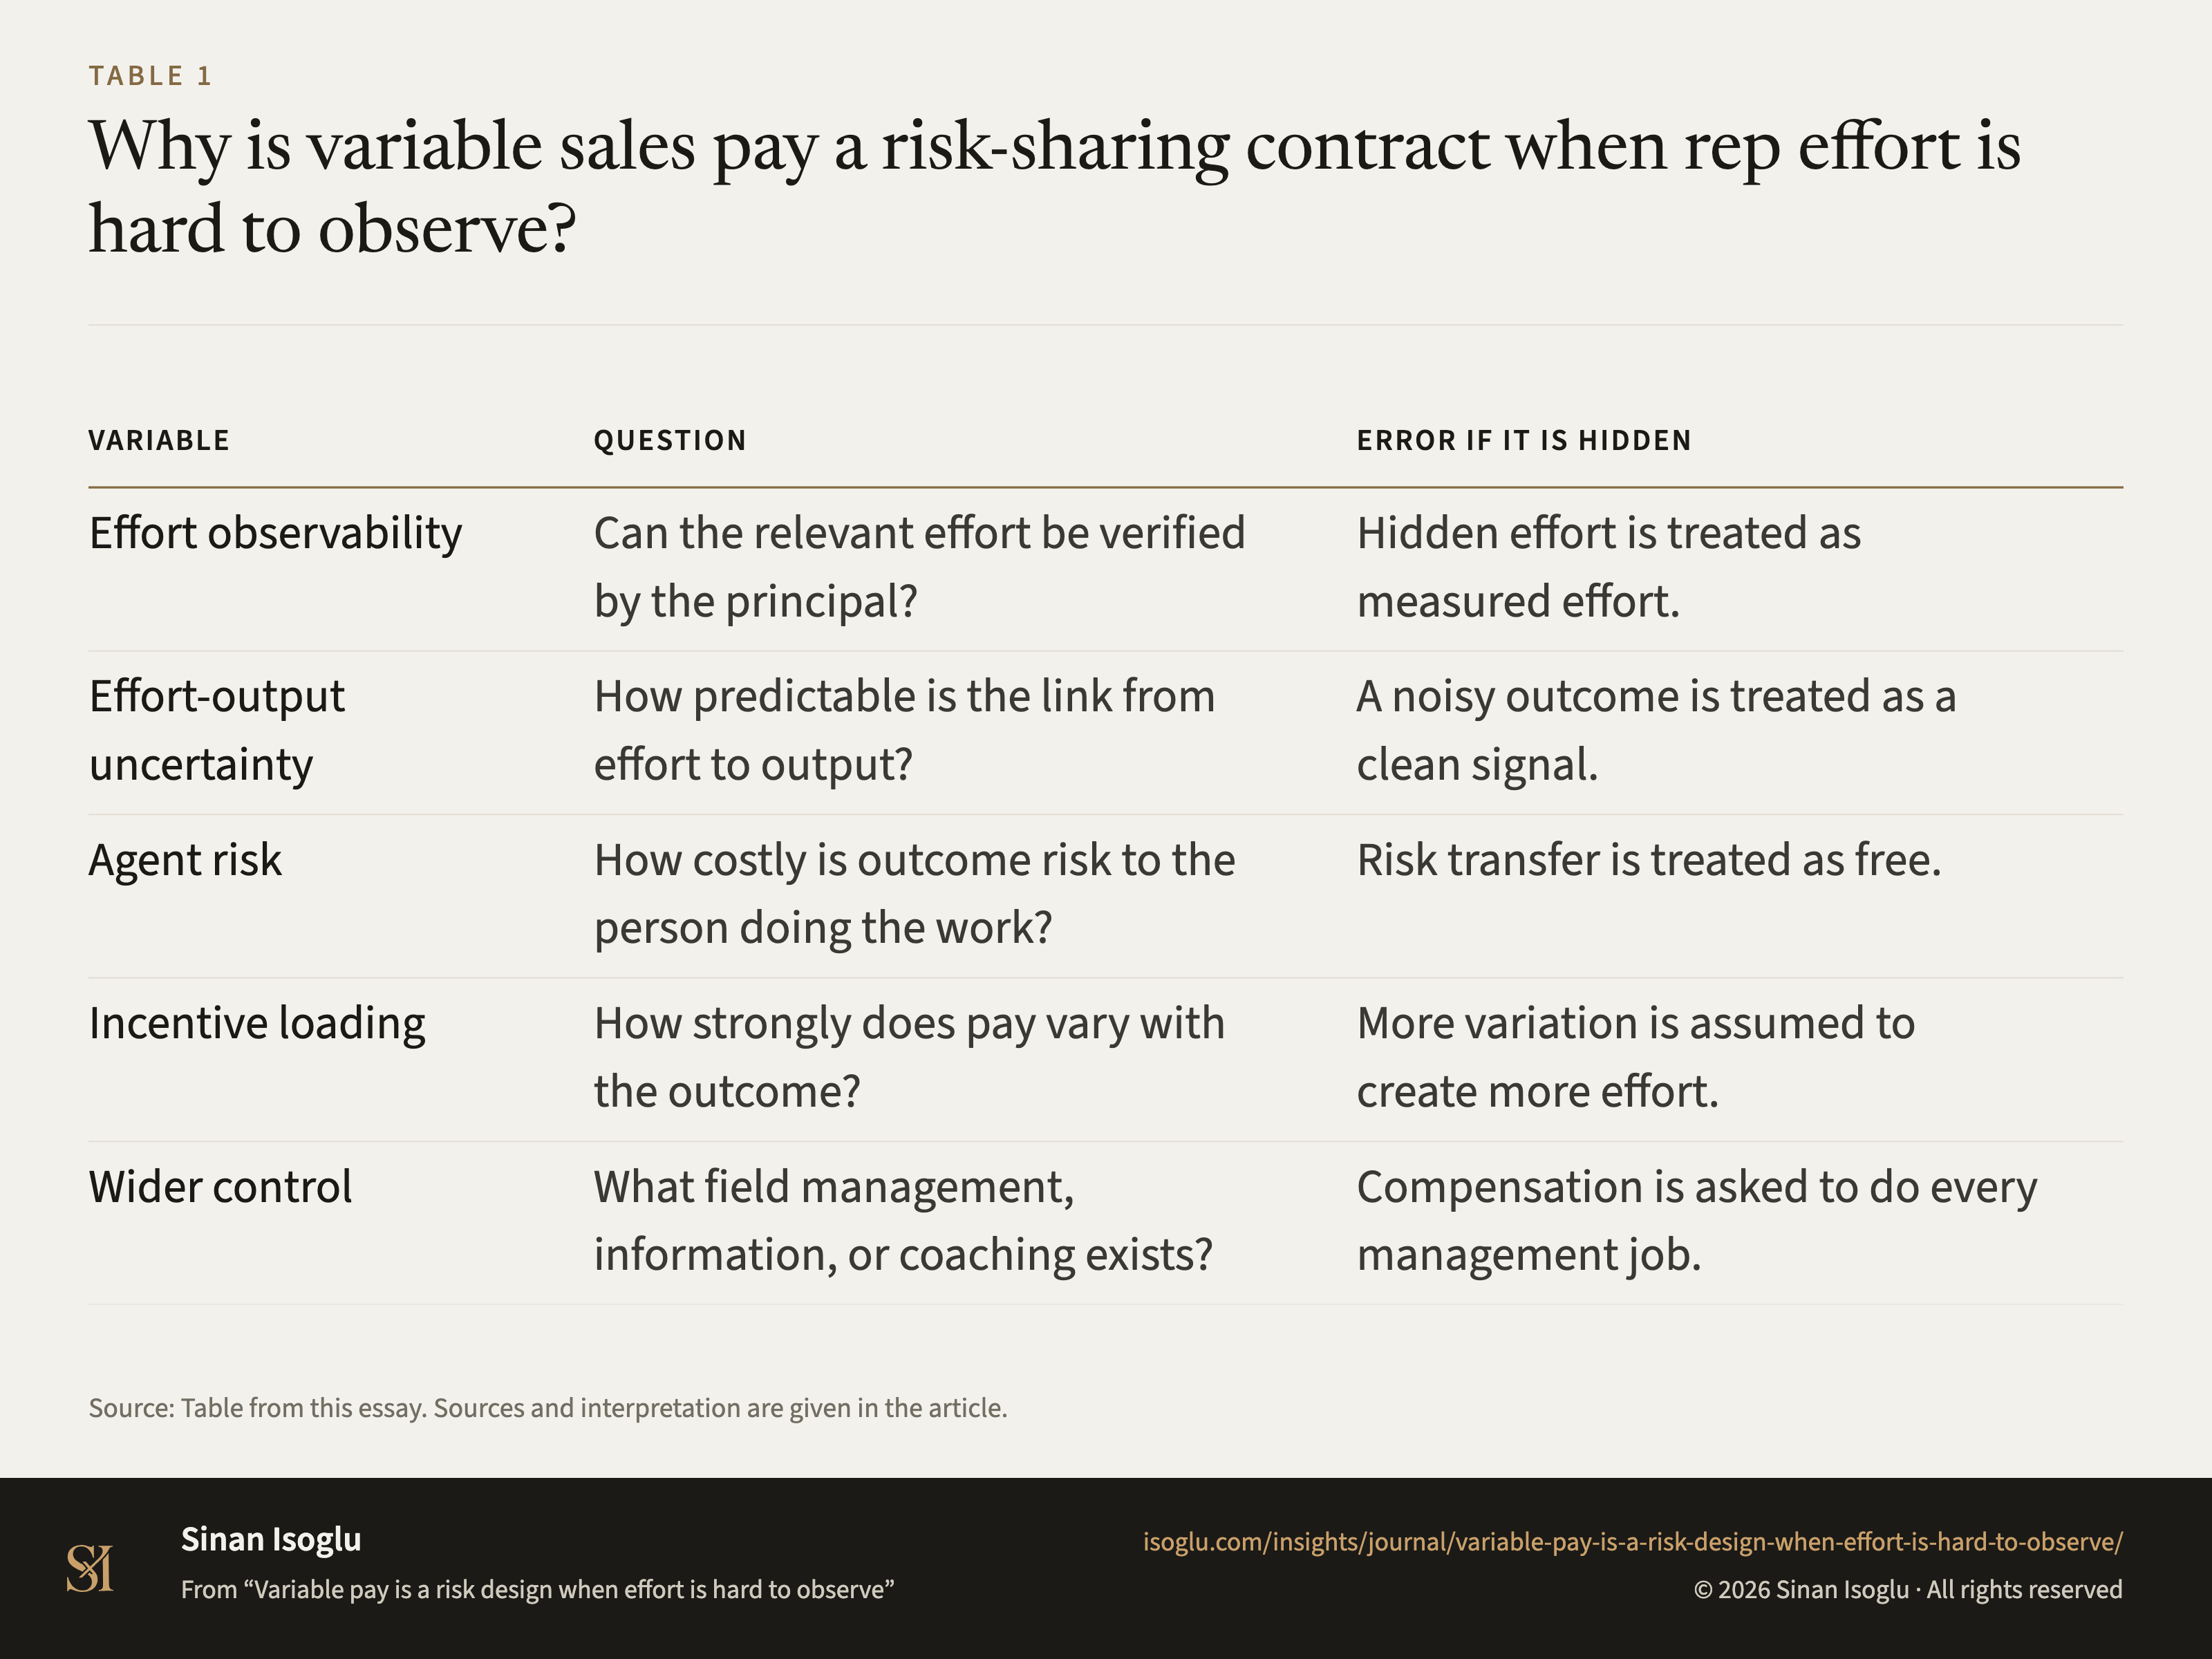
Why is variable sales pay a risk-sharing contract when rep effort is hard to observe?
Table 1Why is variable sales pay a risk-sharing contract when rep effort is hard to observe?
| Variable | Question | Error if it is hidden |
|---|---|---|
| Effort observability | Can the relevant effort be verified by the principal? | Hidden effort is treated as measured effort. |
| Effort-output uncertainty | How predictable is the link from effort to output? | A noisy outcome is treated as a clean signal. |
| Agent risk | How costly is outcome risk to the person doing the work? | Risk transfer is treated as free. |
| Incentive loading | How strongly does pay vary with the outcome? | More variation is assumed to create more effort. |
| Wider control | What field management, information, or coaching exists? | Compensation is asked to do every management job. |
Swipe or scroll horizontally if the table is wider than your screen.
Source: Table from this essay. Sources and interpretation are given in the article.
From the essay
Revenue operations & AI
Variable pay is a risk design when effort is hard to observe
When effort is hidden and output is uncertain, incentive intensity is conditional: separate observability, risk, uncertainty, and wider control.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Related exhibits
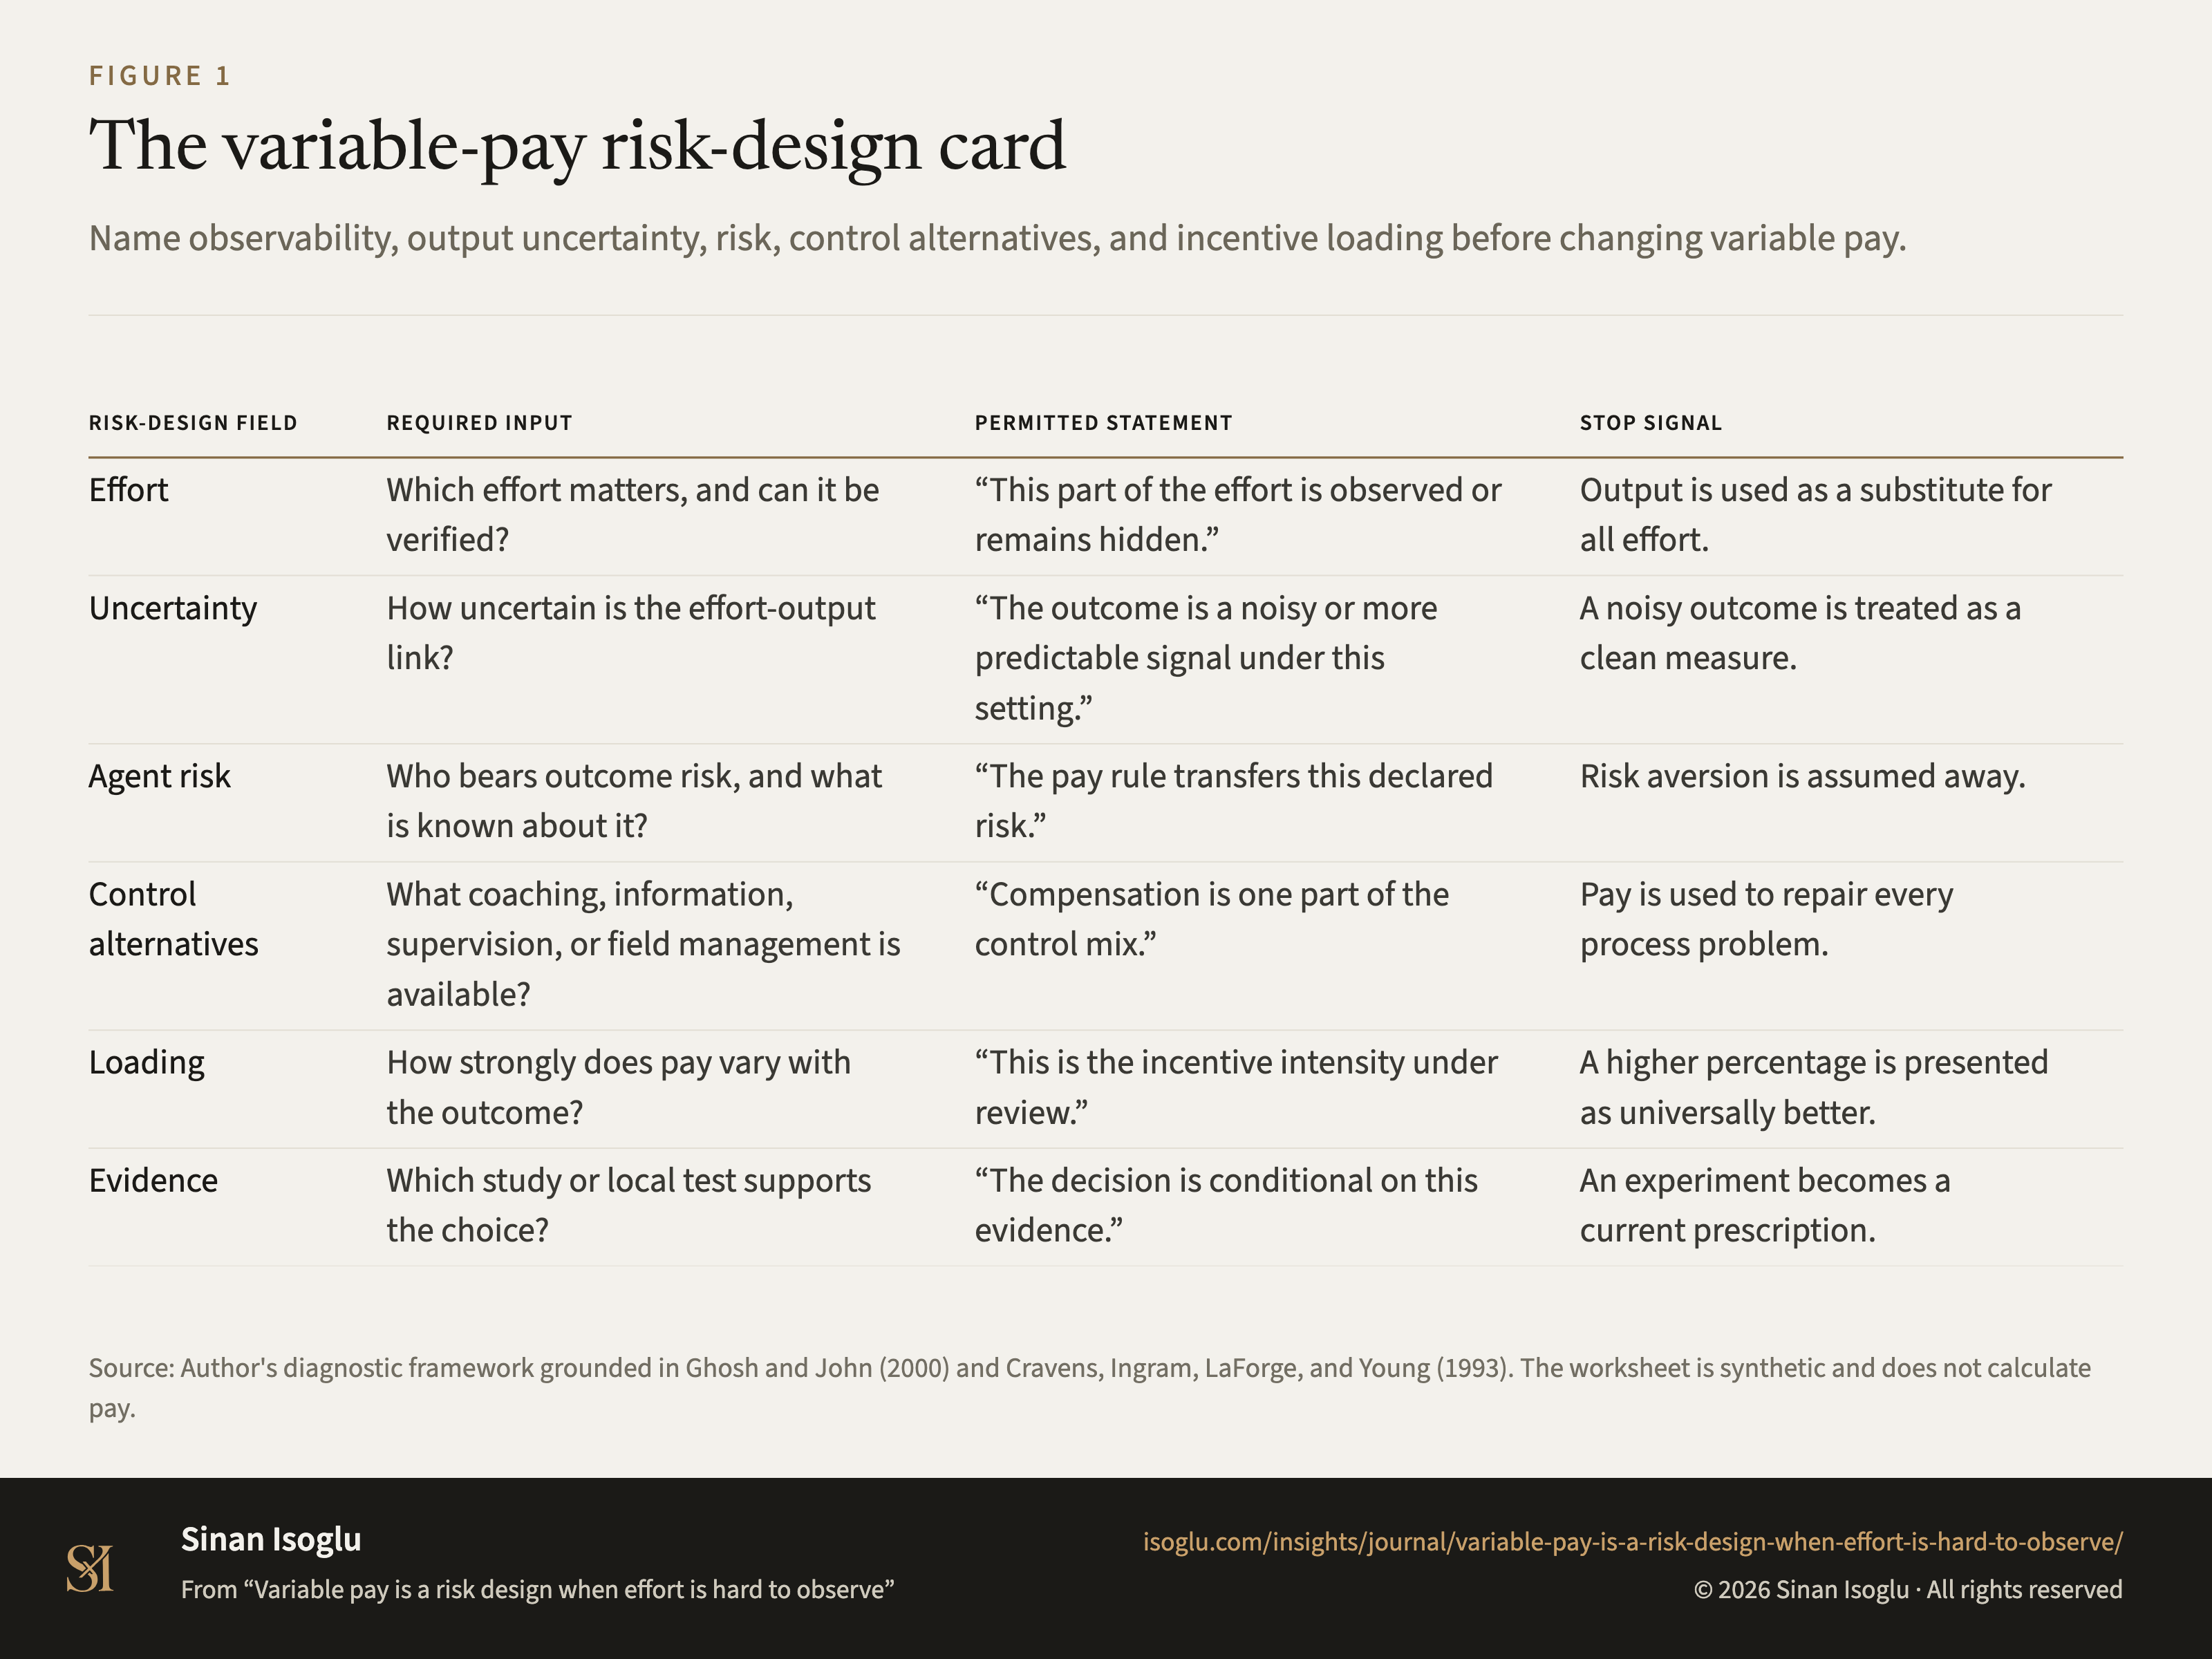
Figure 1Figure
The variable-pay risk-design card
Variable pay is a risk design when effort is hard to observe
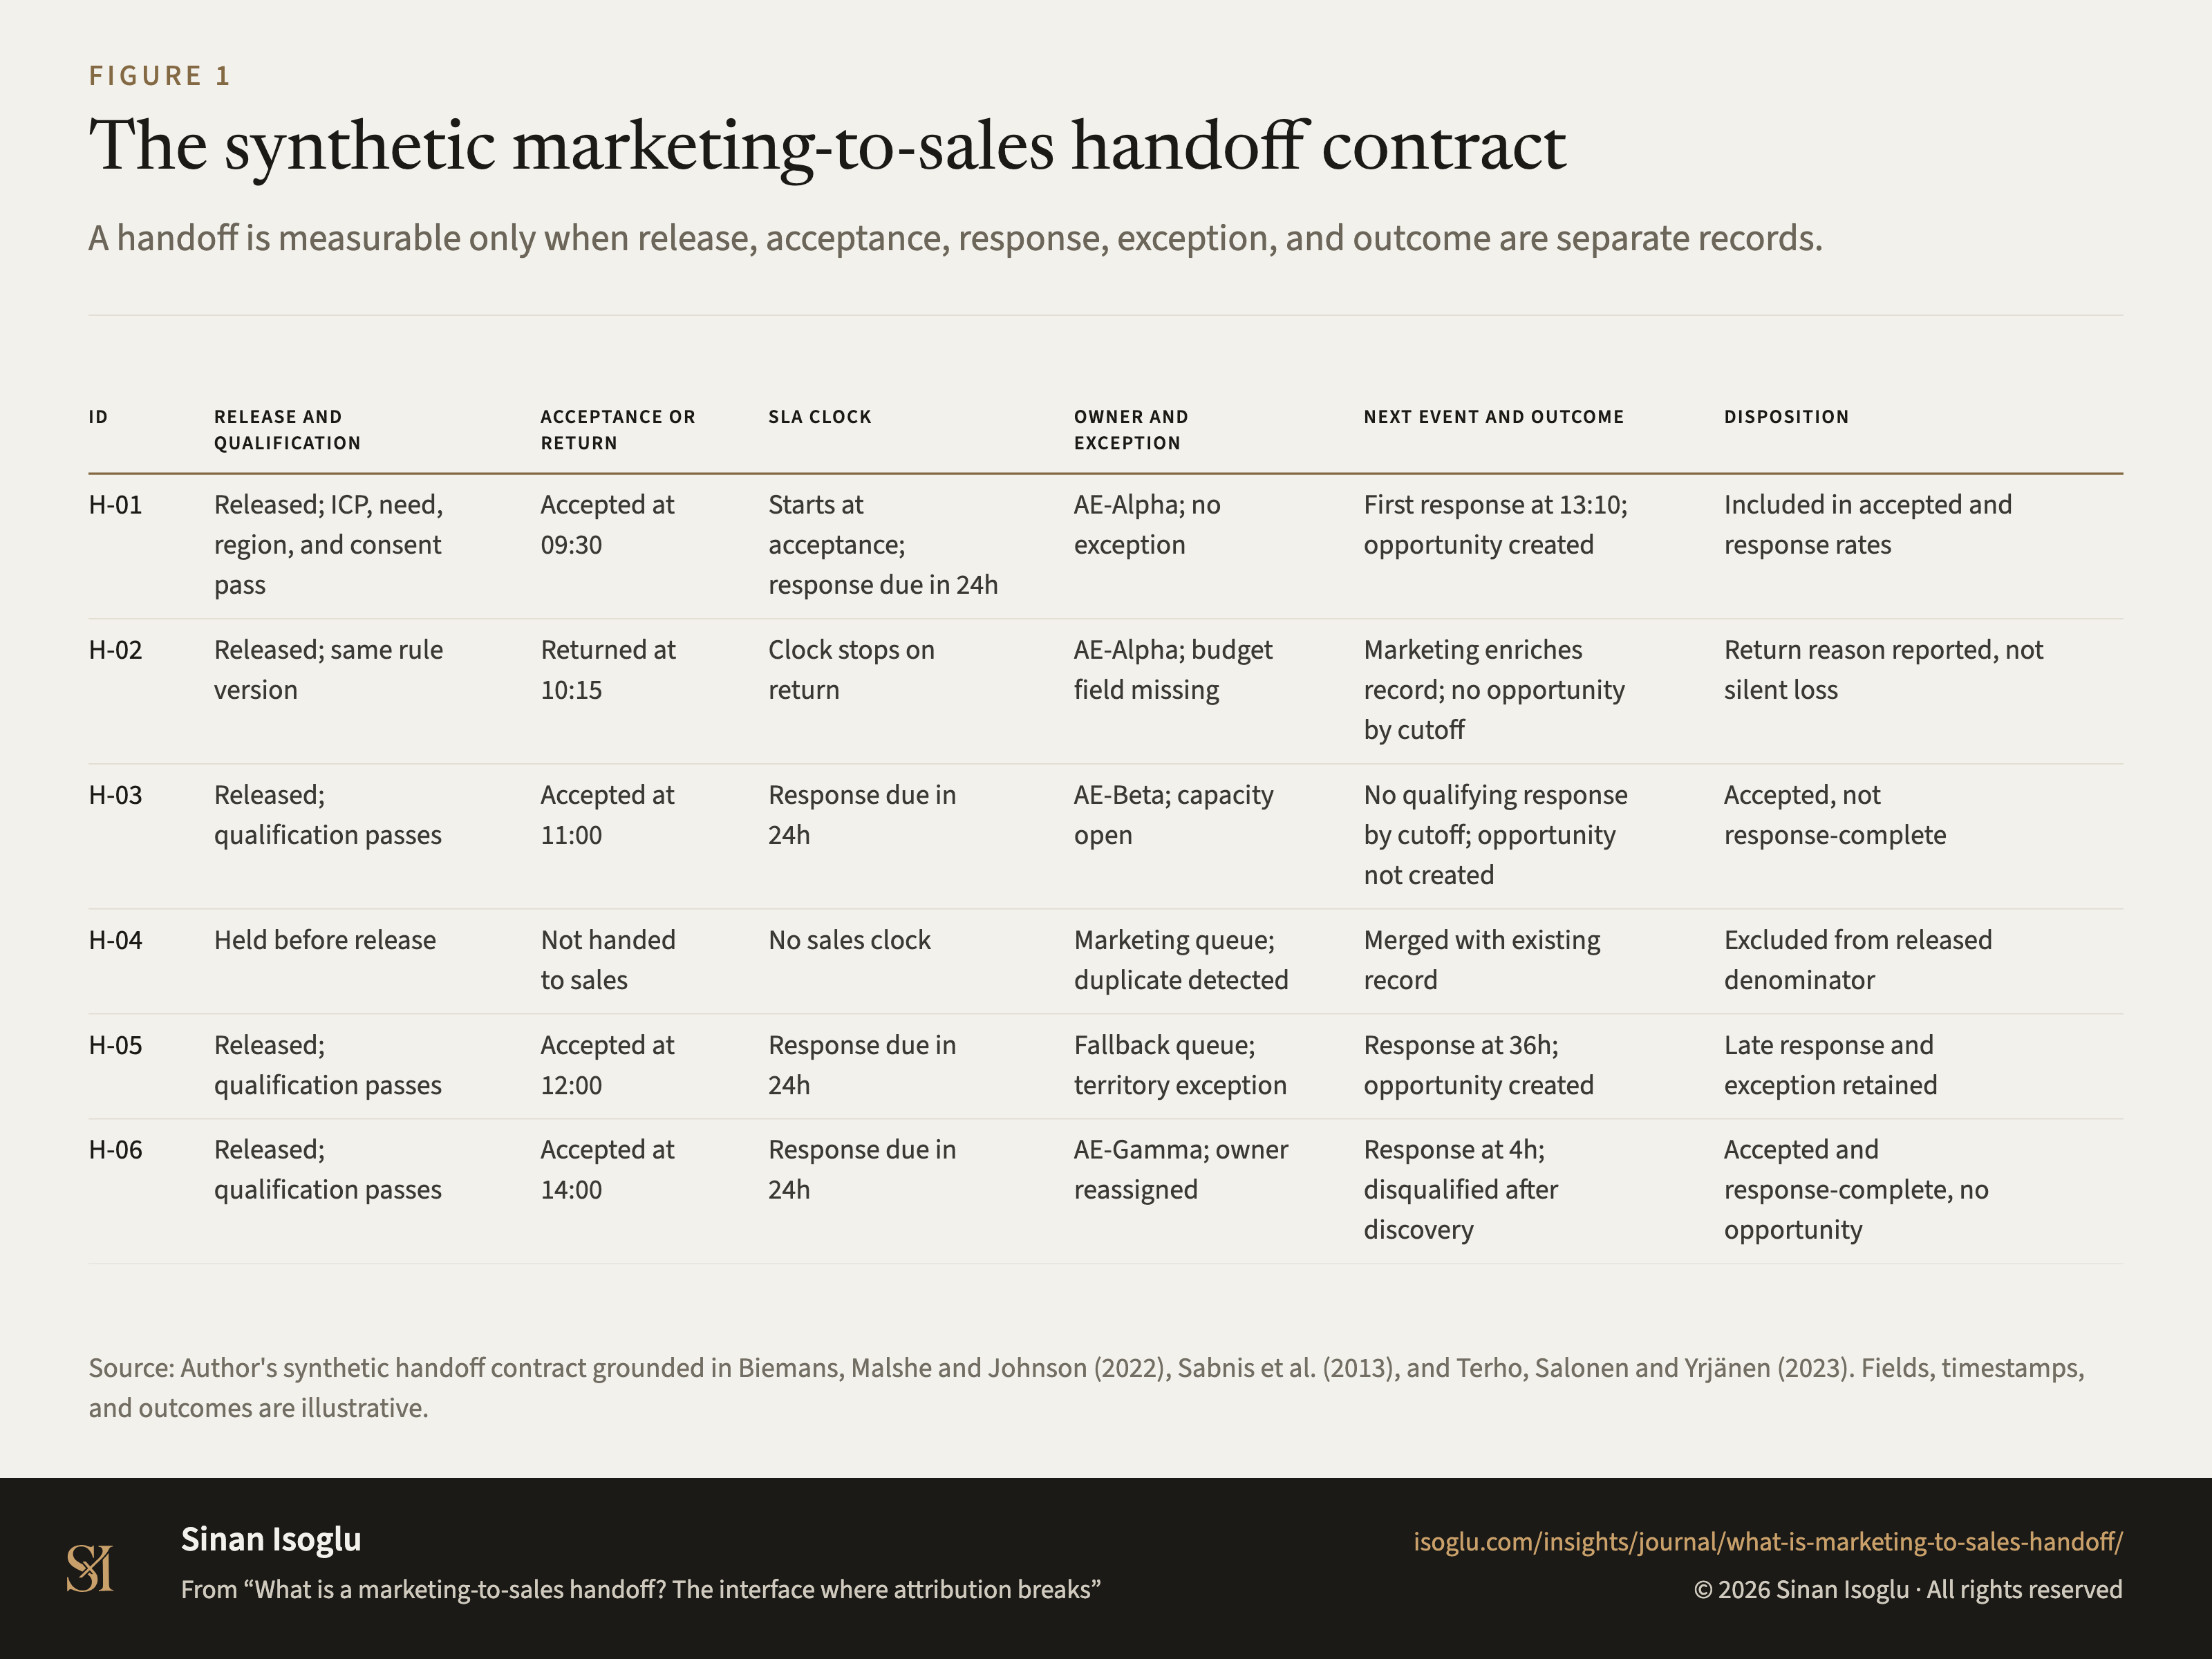
Figure 1Figure
The synthetic marketing-to-sales handoff contract
What is a marketing-to-sales handoff? The interface where attribution breaks
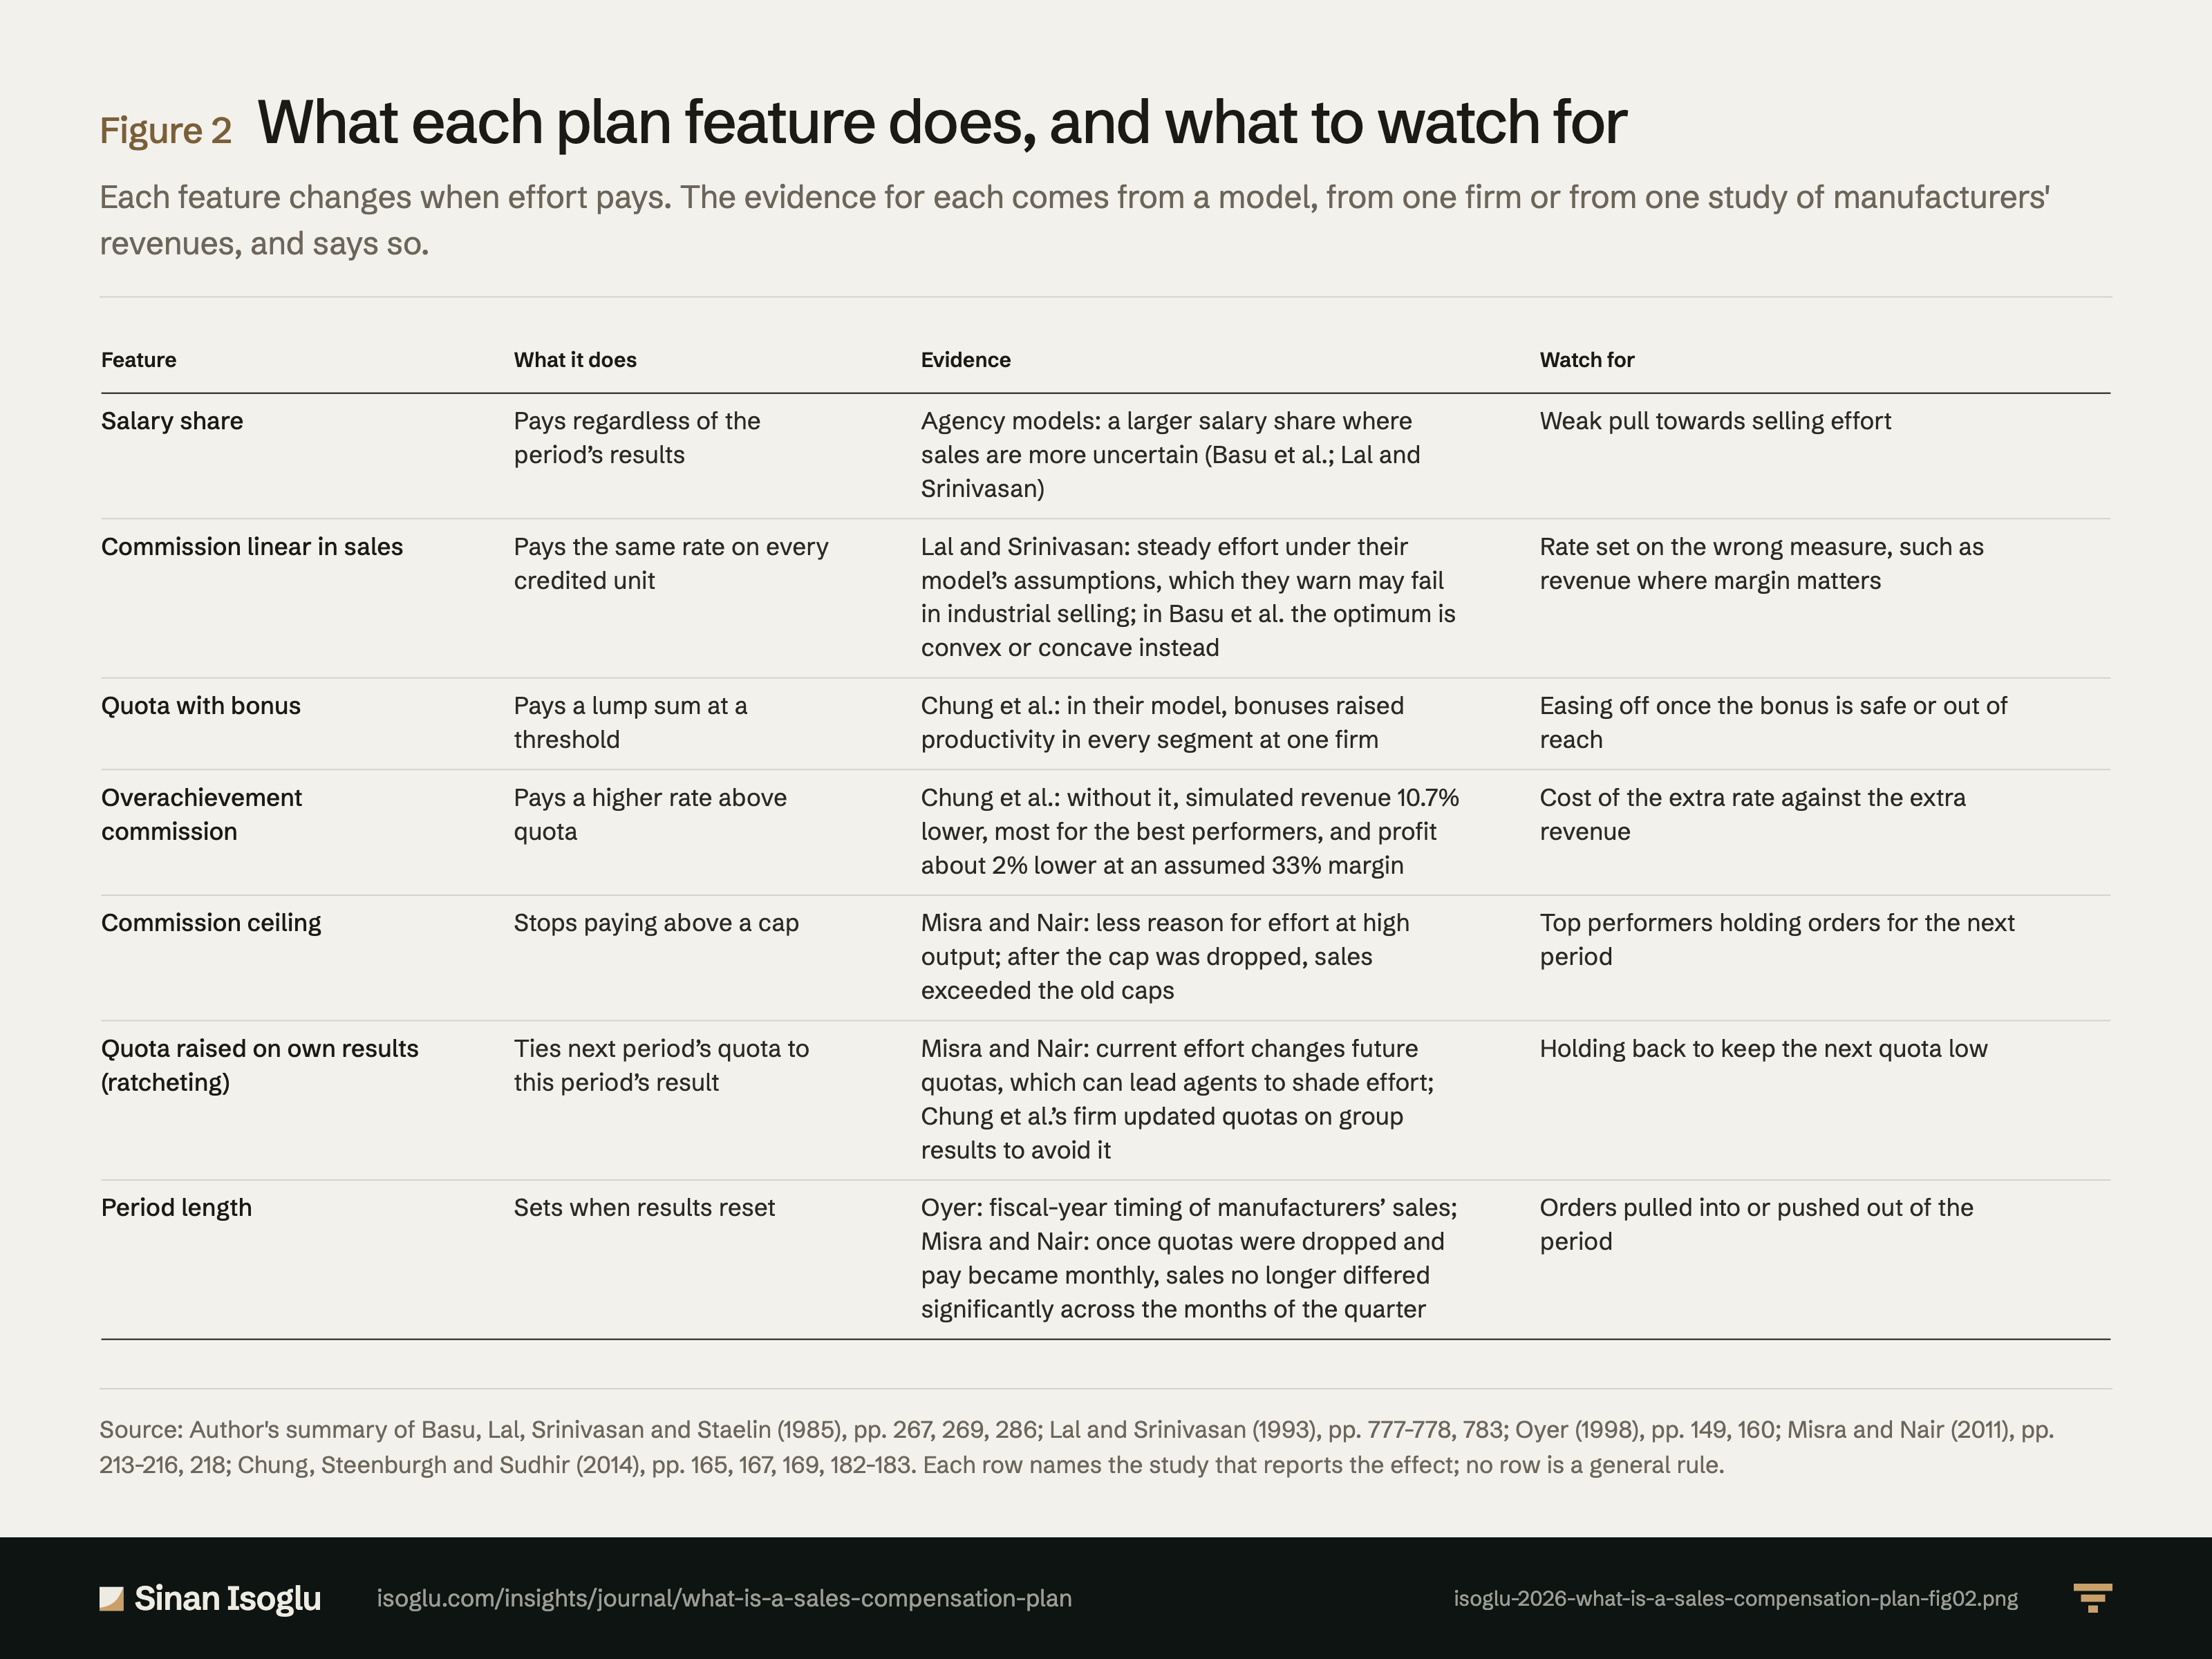
Figure 2Figure
What each plan feature does, and what to watch for
What is a sales compensation plan?
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.