← Every exhibit
Table 1From “Promised synergies need a ledger”
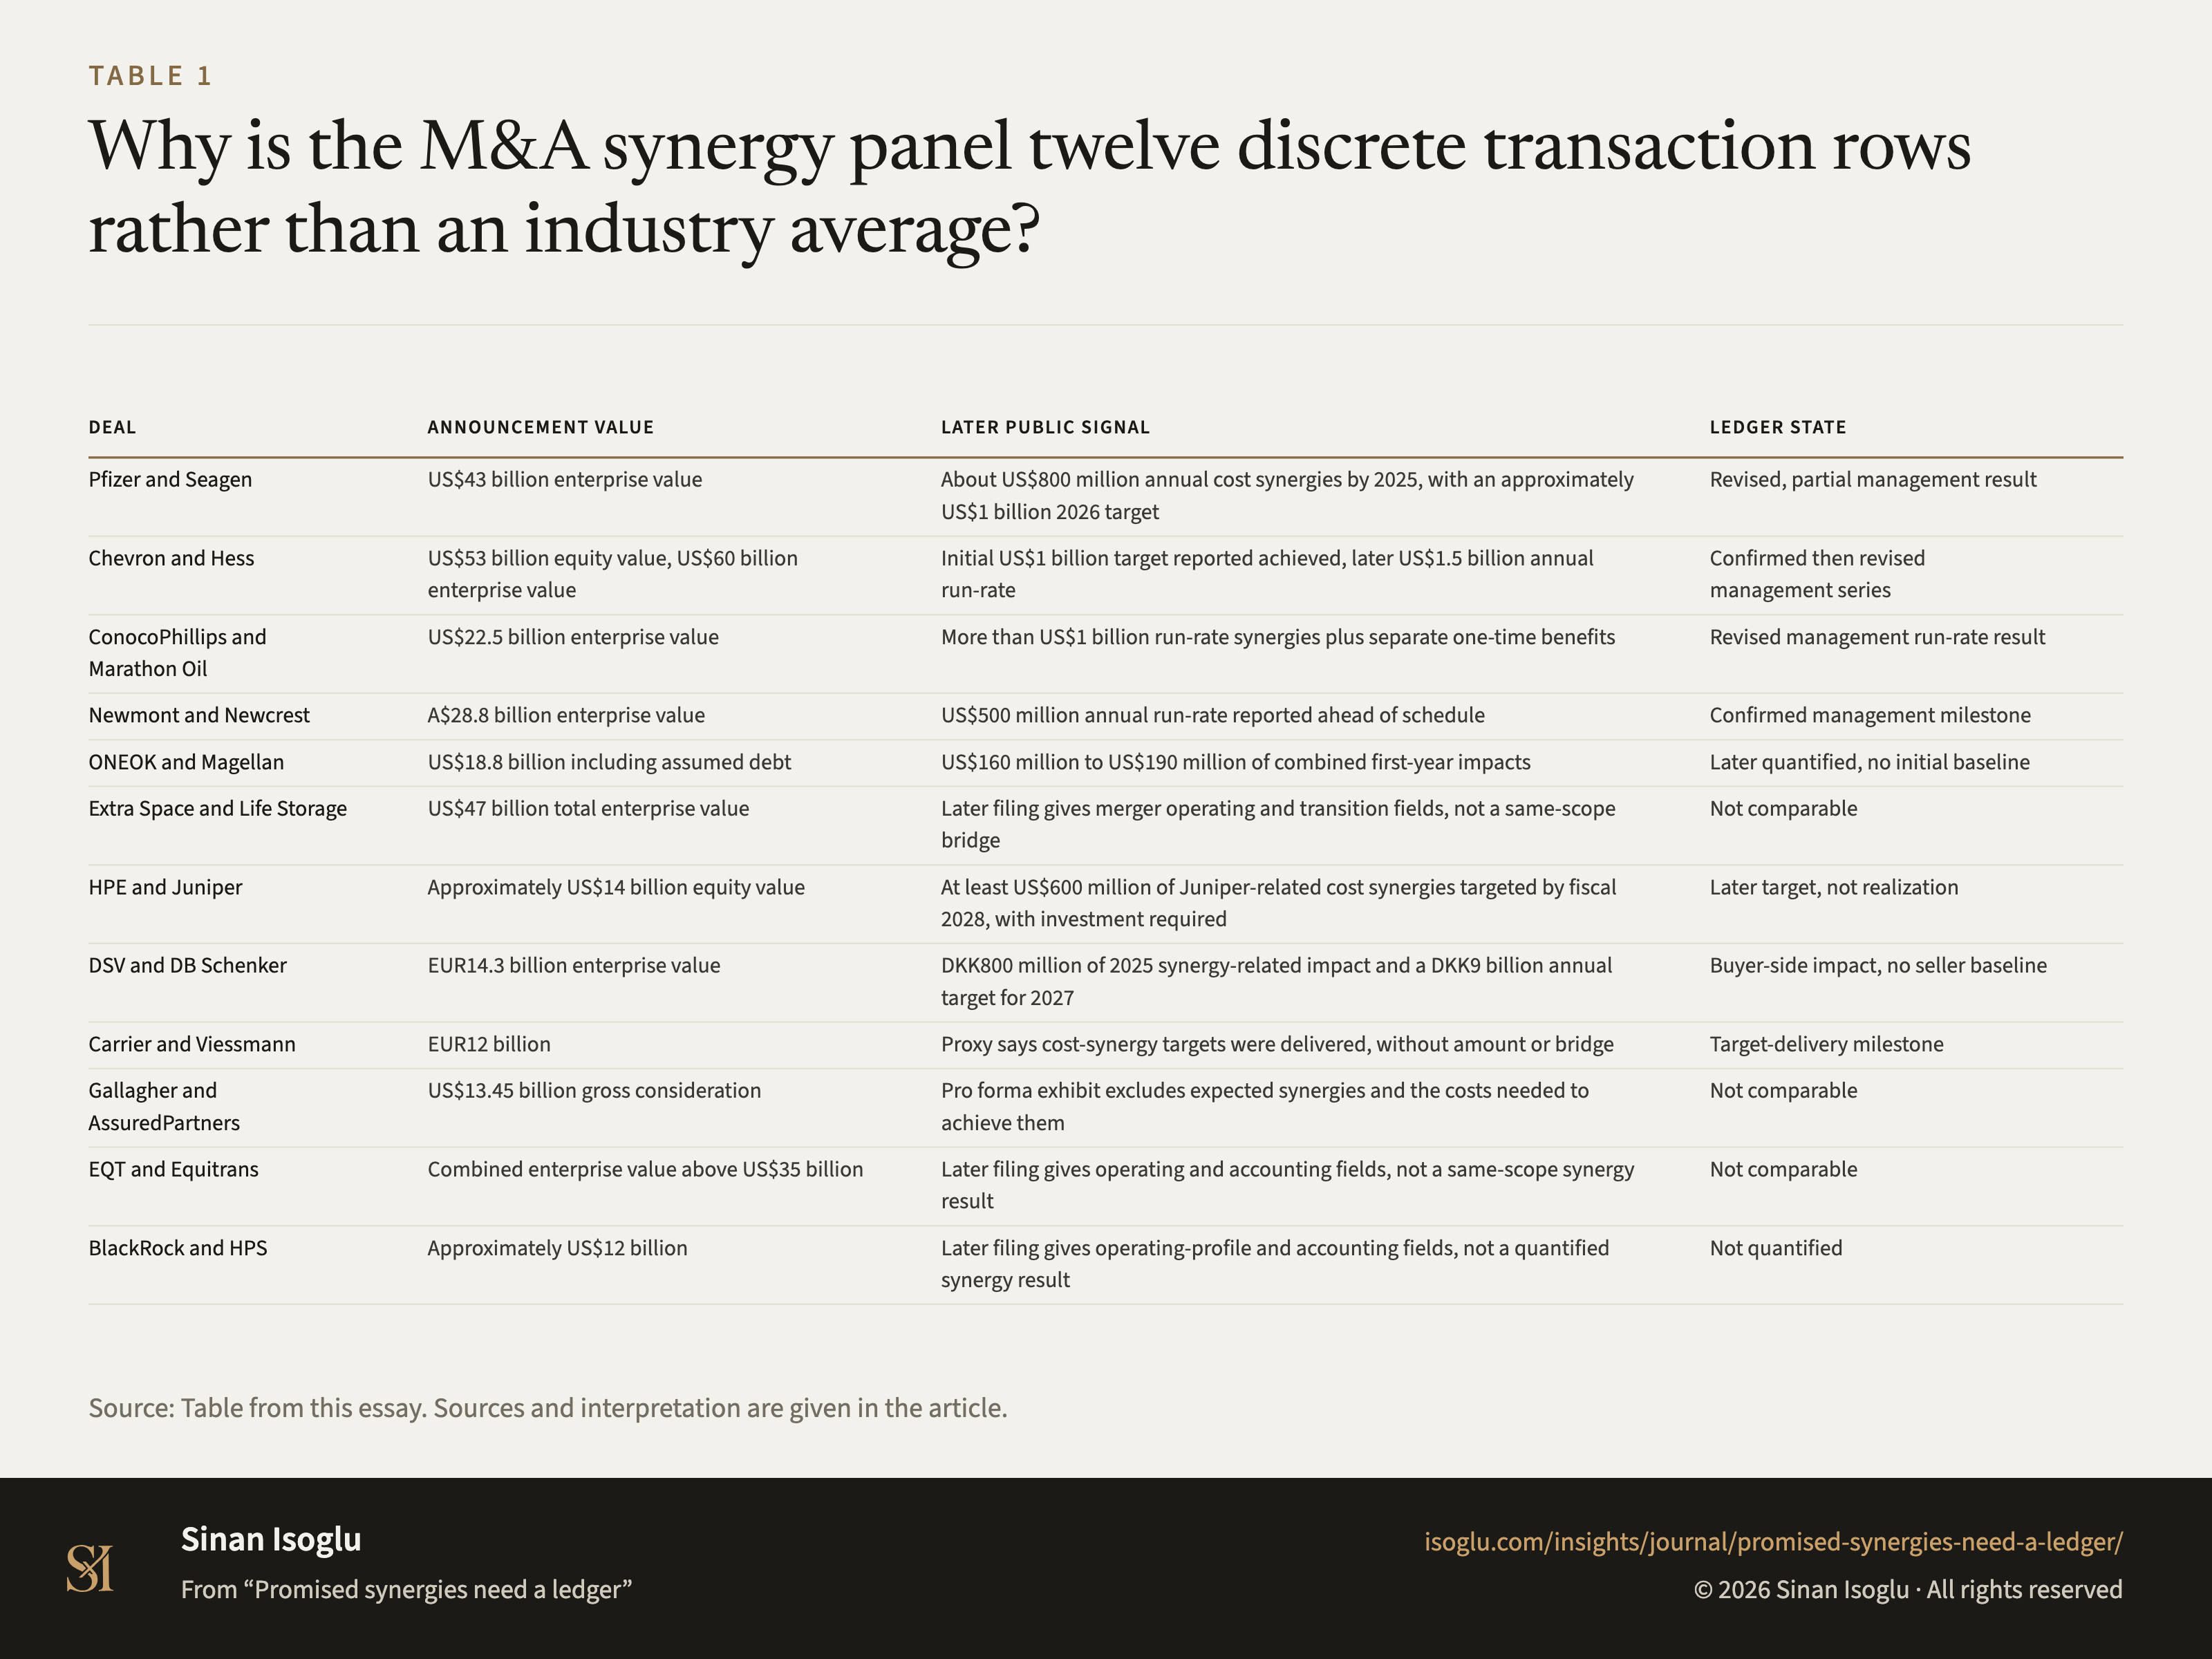
Why is the M&A synergy panel twelve discrete transaction rows rather than an industry average?
Table 1Why is the M&A synergy panel twelve discrete transaction rows rather than an industry average?
| Deal | Announcement value | Later public signal | Ledger state |
|---|---|---|---|
| Pfizer and Seagen | US\$43 billion enterprise value | About US\$800 million annual cost synergies by 2025, with an approximately US\$1 billion 2026 target | Revised, partial management result |
| Chevron and Hess | US\$53 billion equity value, US\$60 billion enterprise value | Initial US\$1 billion target reported achieved, later US\$1.5 billion annual run-rate | Confirmed then revised management series |
| ConocoPhillips and Marathon Oil | US\$22.5 billion enterprise value | More than US\$1 billion run-rate synergies plus separate one-time benefits | Revised management run-rate result |
| Newmont and Newcrest | A\$28.8 billion enterprise value | US\$500 million annual run-rate reported ahead of schedule | Confirmed management milestone |
| ONEOK and Magellan | US\$18.8 billion including assumed debt | US\$160 million to US\$190 million of combined first-year impacts | Later quantified, no initial baseline |
| Extra Space and Life Storage | US\$47 billion total enterprise value | Later filing gives merger operating and transition fields, not a same-scope bridge | Not comparable |
| HPE and Juniper | Approximately US\$14 billion equity value | At least US\$600 million of Juniper-related cost synergies targeted by fiscal 2028, with investment required | Later target, not realization |
| DSV and DB Schenker | EUR14.3 billion enterprise value | DKK800 million of 2025 synergy-related impact and a DKK9 billion annual target for 2027 | Buyer-side impact, no seller baseline |
| Carrier and Viessmann | EUR12 billion | Proxy says cost-synergy targets were delivered, without amount or bridge | Target-delivery milestone |
| Gallagher and AssuredPartners | US\$13.45 billion gross consideration | Pro forma exhibit excludes expected synergies and the costs needed to achieve them | Not comparable |
| EQT and Equitrans | Combined enterprise value above US\$35 billion | Later filing gives operating and accounting fields, not a same-scope synergy result | Not comparable |
| BlackRock and HPS | Approximately US\$12 billion | Later filing gives operating-profile and accounting fields, not a quantified synergy result | Not quantified |
Swipe or scroll horizontally if the table is wider than your screen.
Source: Table from this essay. Sources and interpretation are given in the article.
PNG4:3, 1600 × 1200, with the title, the source line and the attribution set in the image isoglu-2026-promised-synergies-need-a-ledger-fig01.png
From the essay
Growth that compounds
Promised synergies need a ledger
A deal promise is not a result. Track its unit, baseline, timing, and later statement before calling a synergy realized.
Read the essayThis exhibit belongs to an essay: the numbers live here, the argument lives there.
Cite or embed
Related exhibits
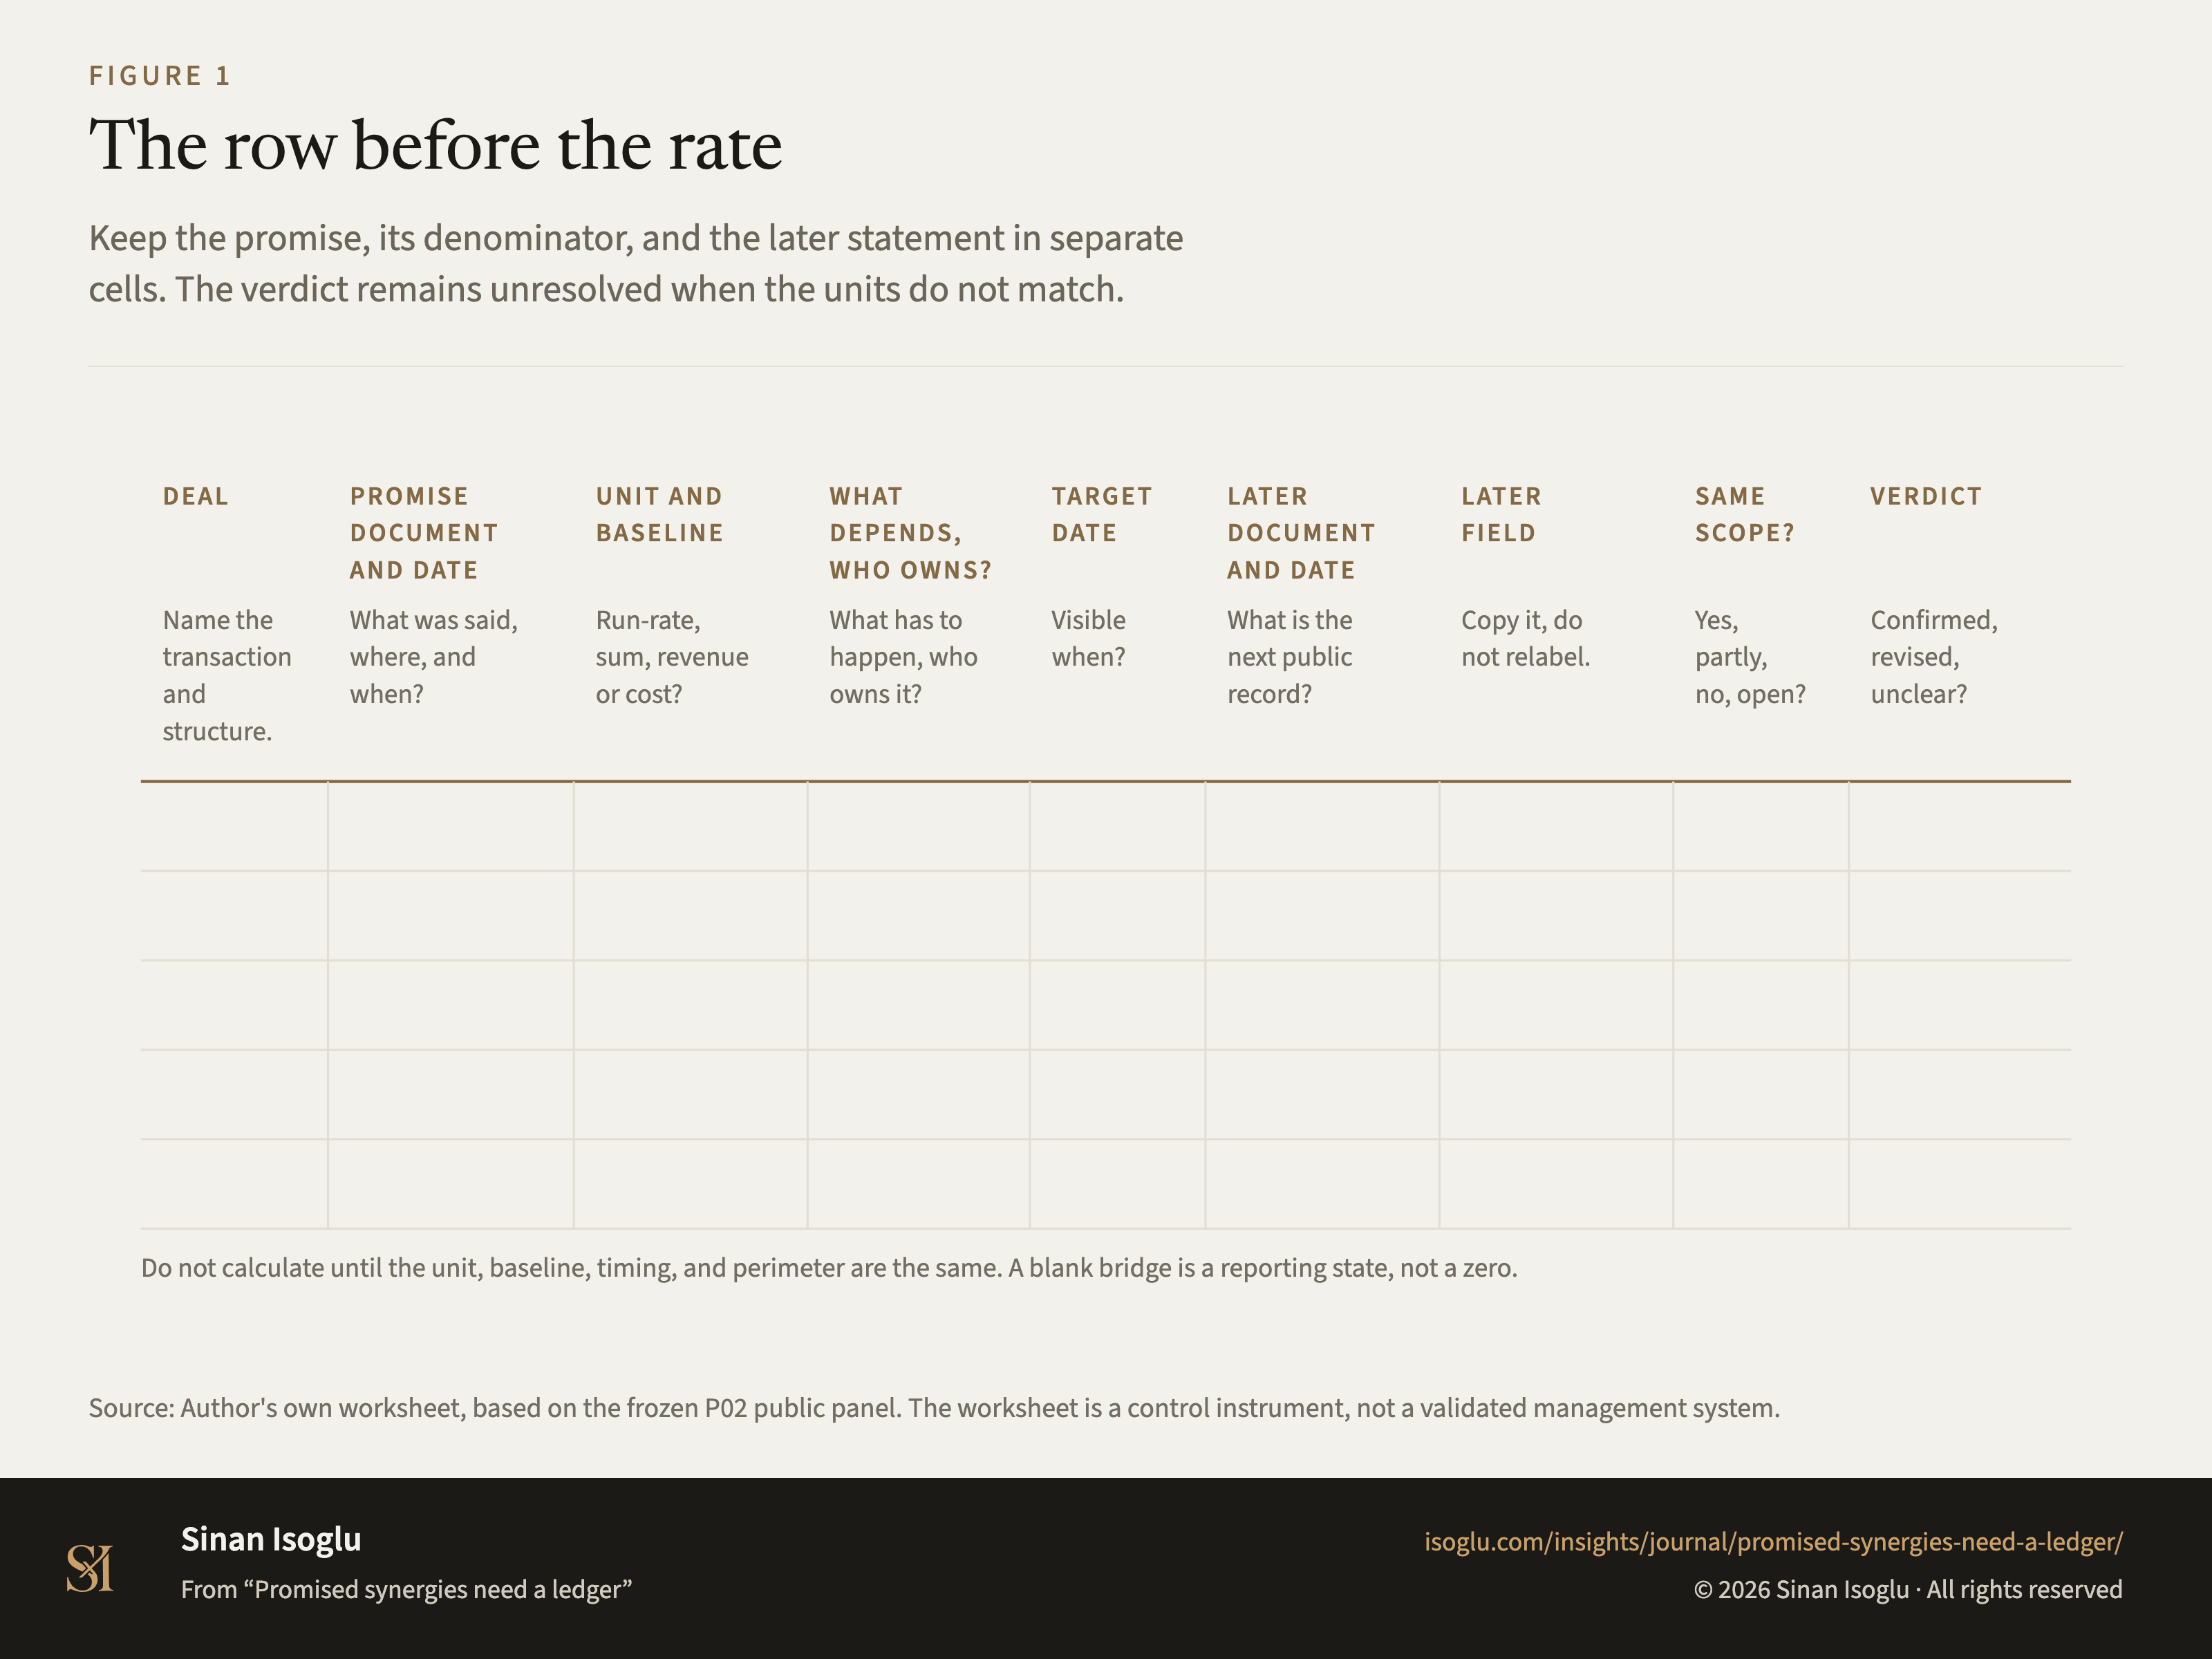
Figure 1Figure
The row before the rate
Promised synergies need a ledger
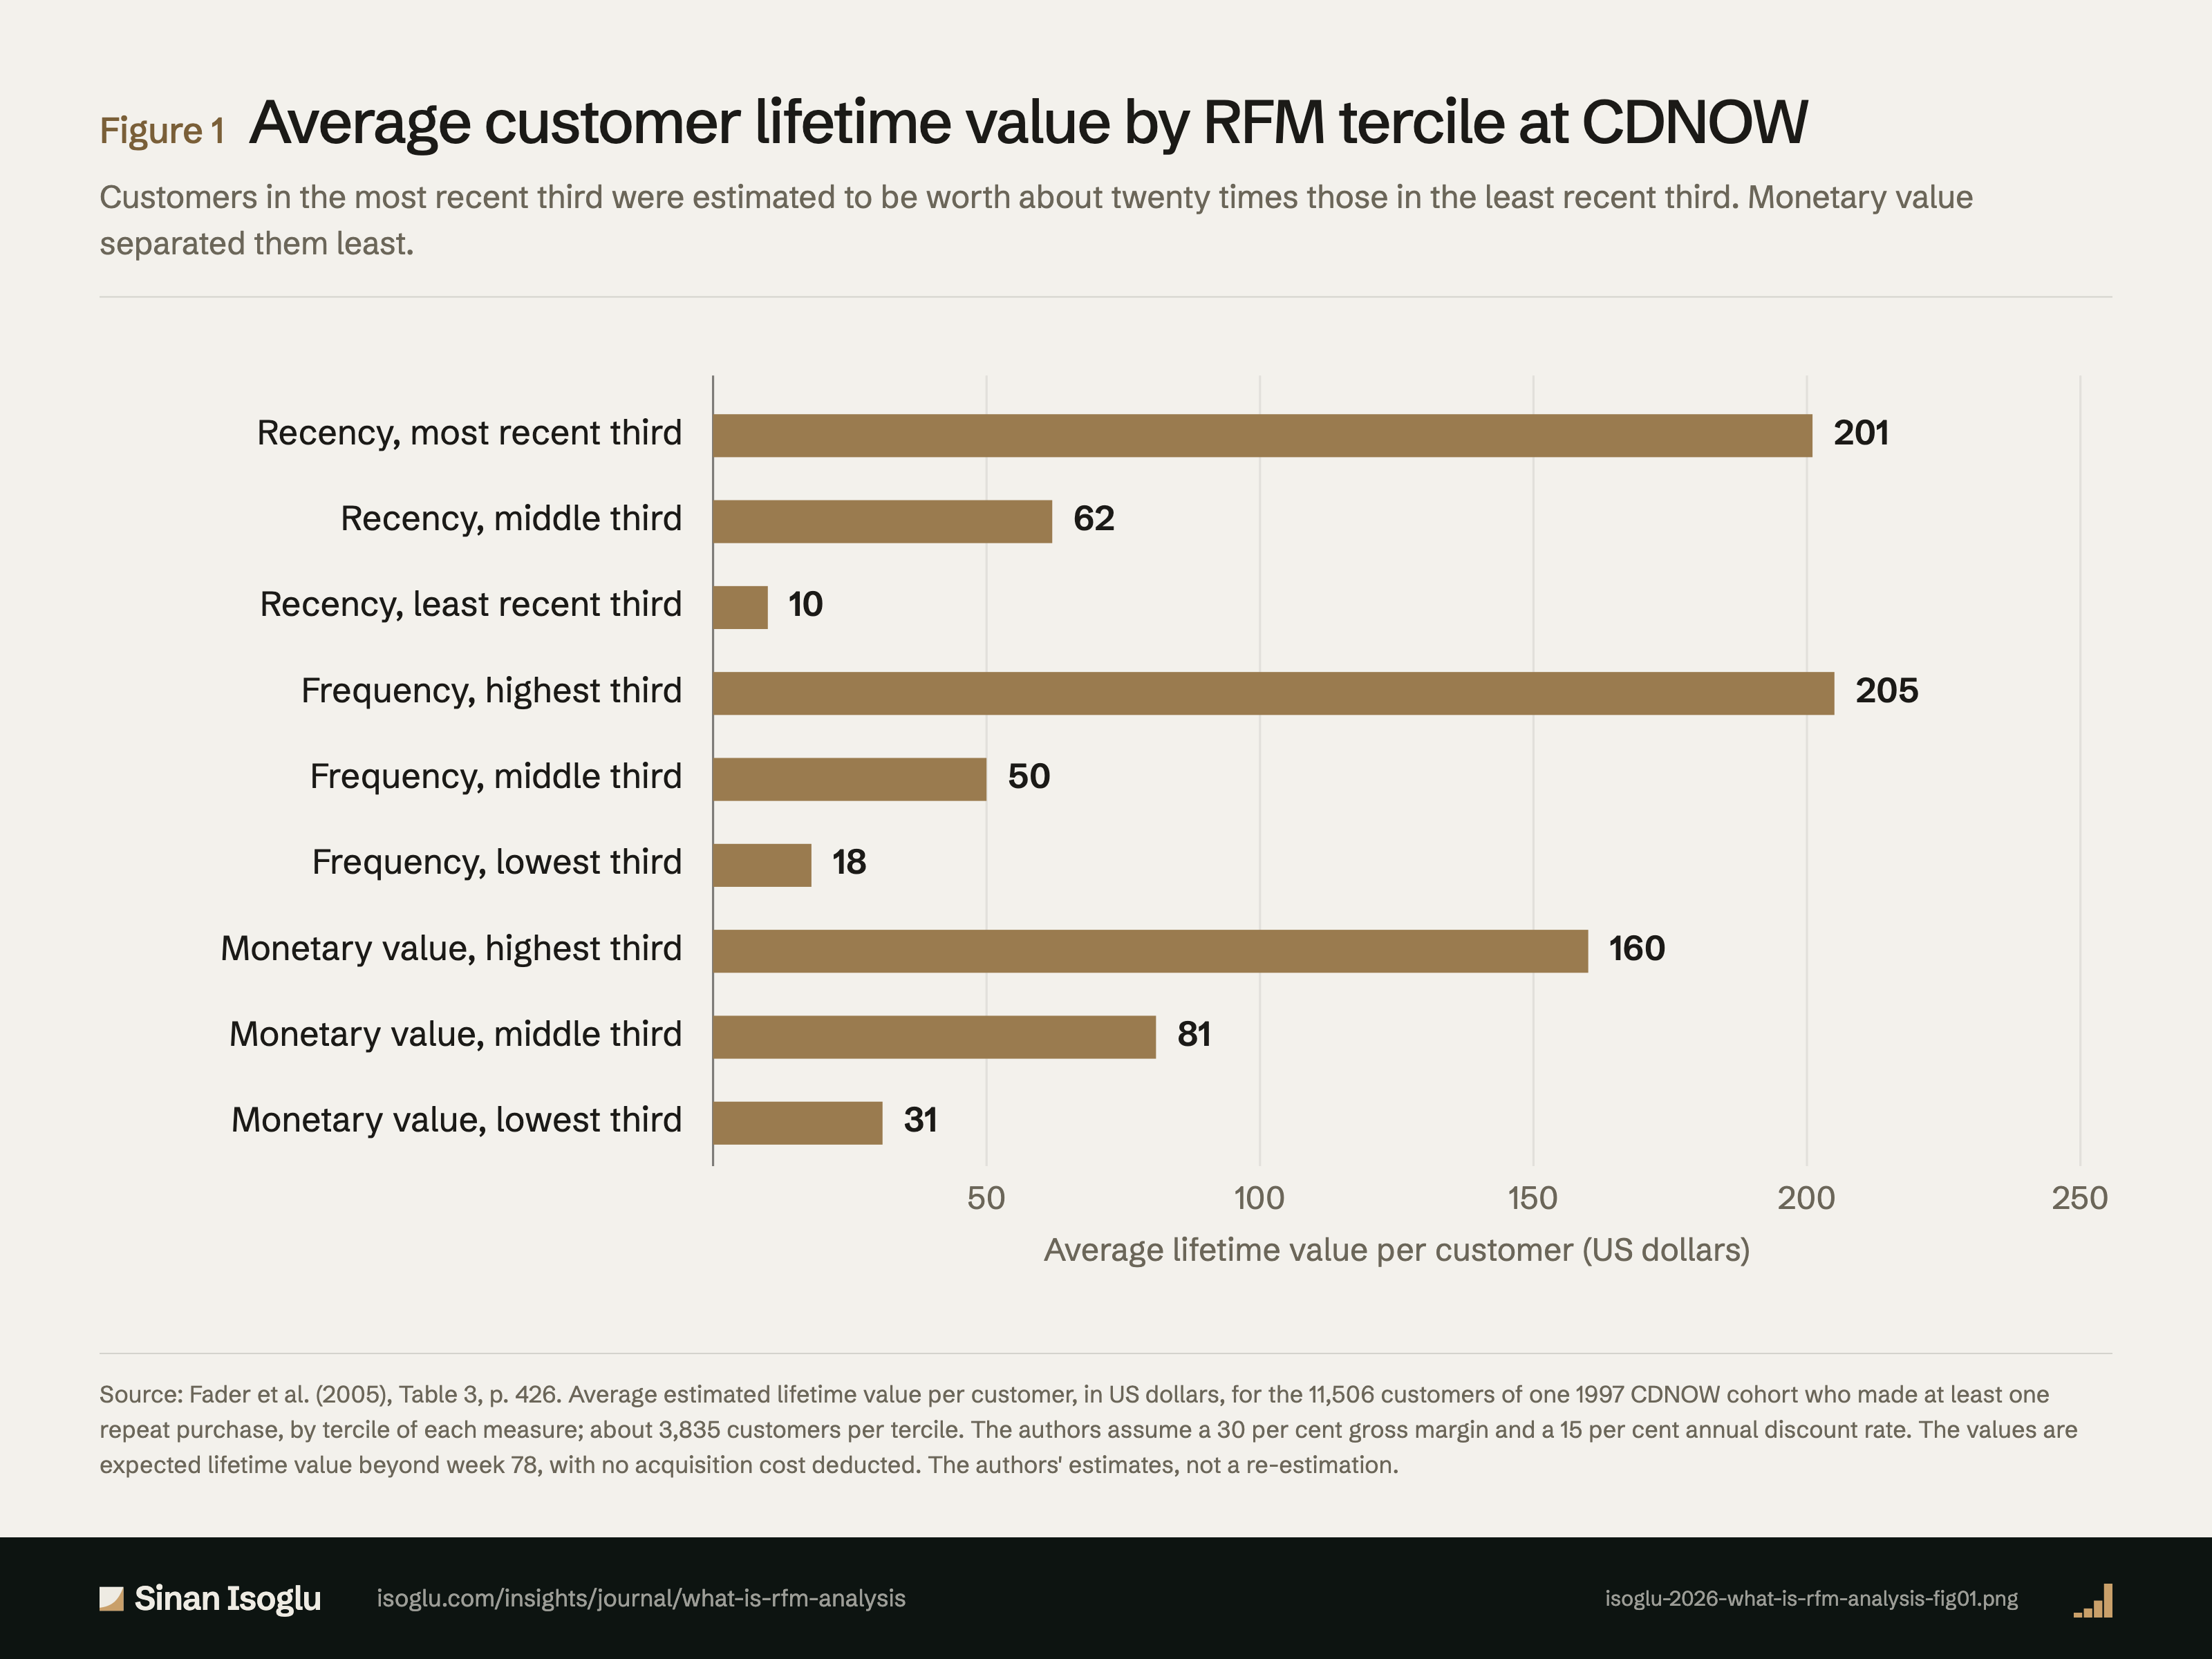
Figure 1Figure
Average customer lifetime value by RFM tercile at CDNOW
What is RFM analysis?
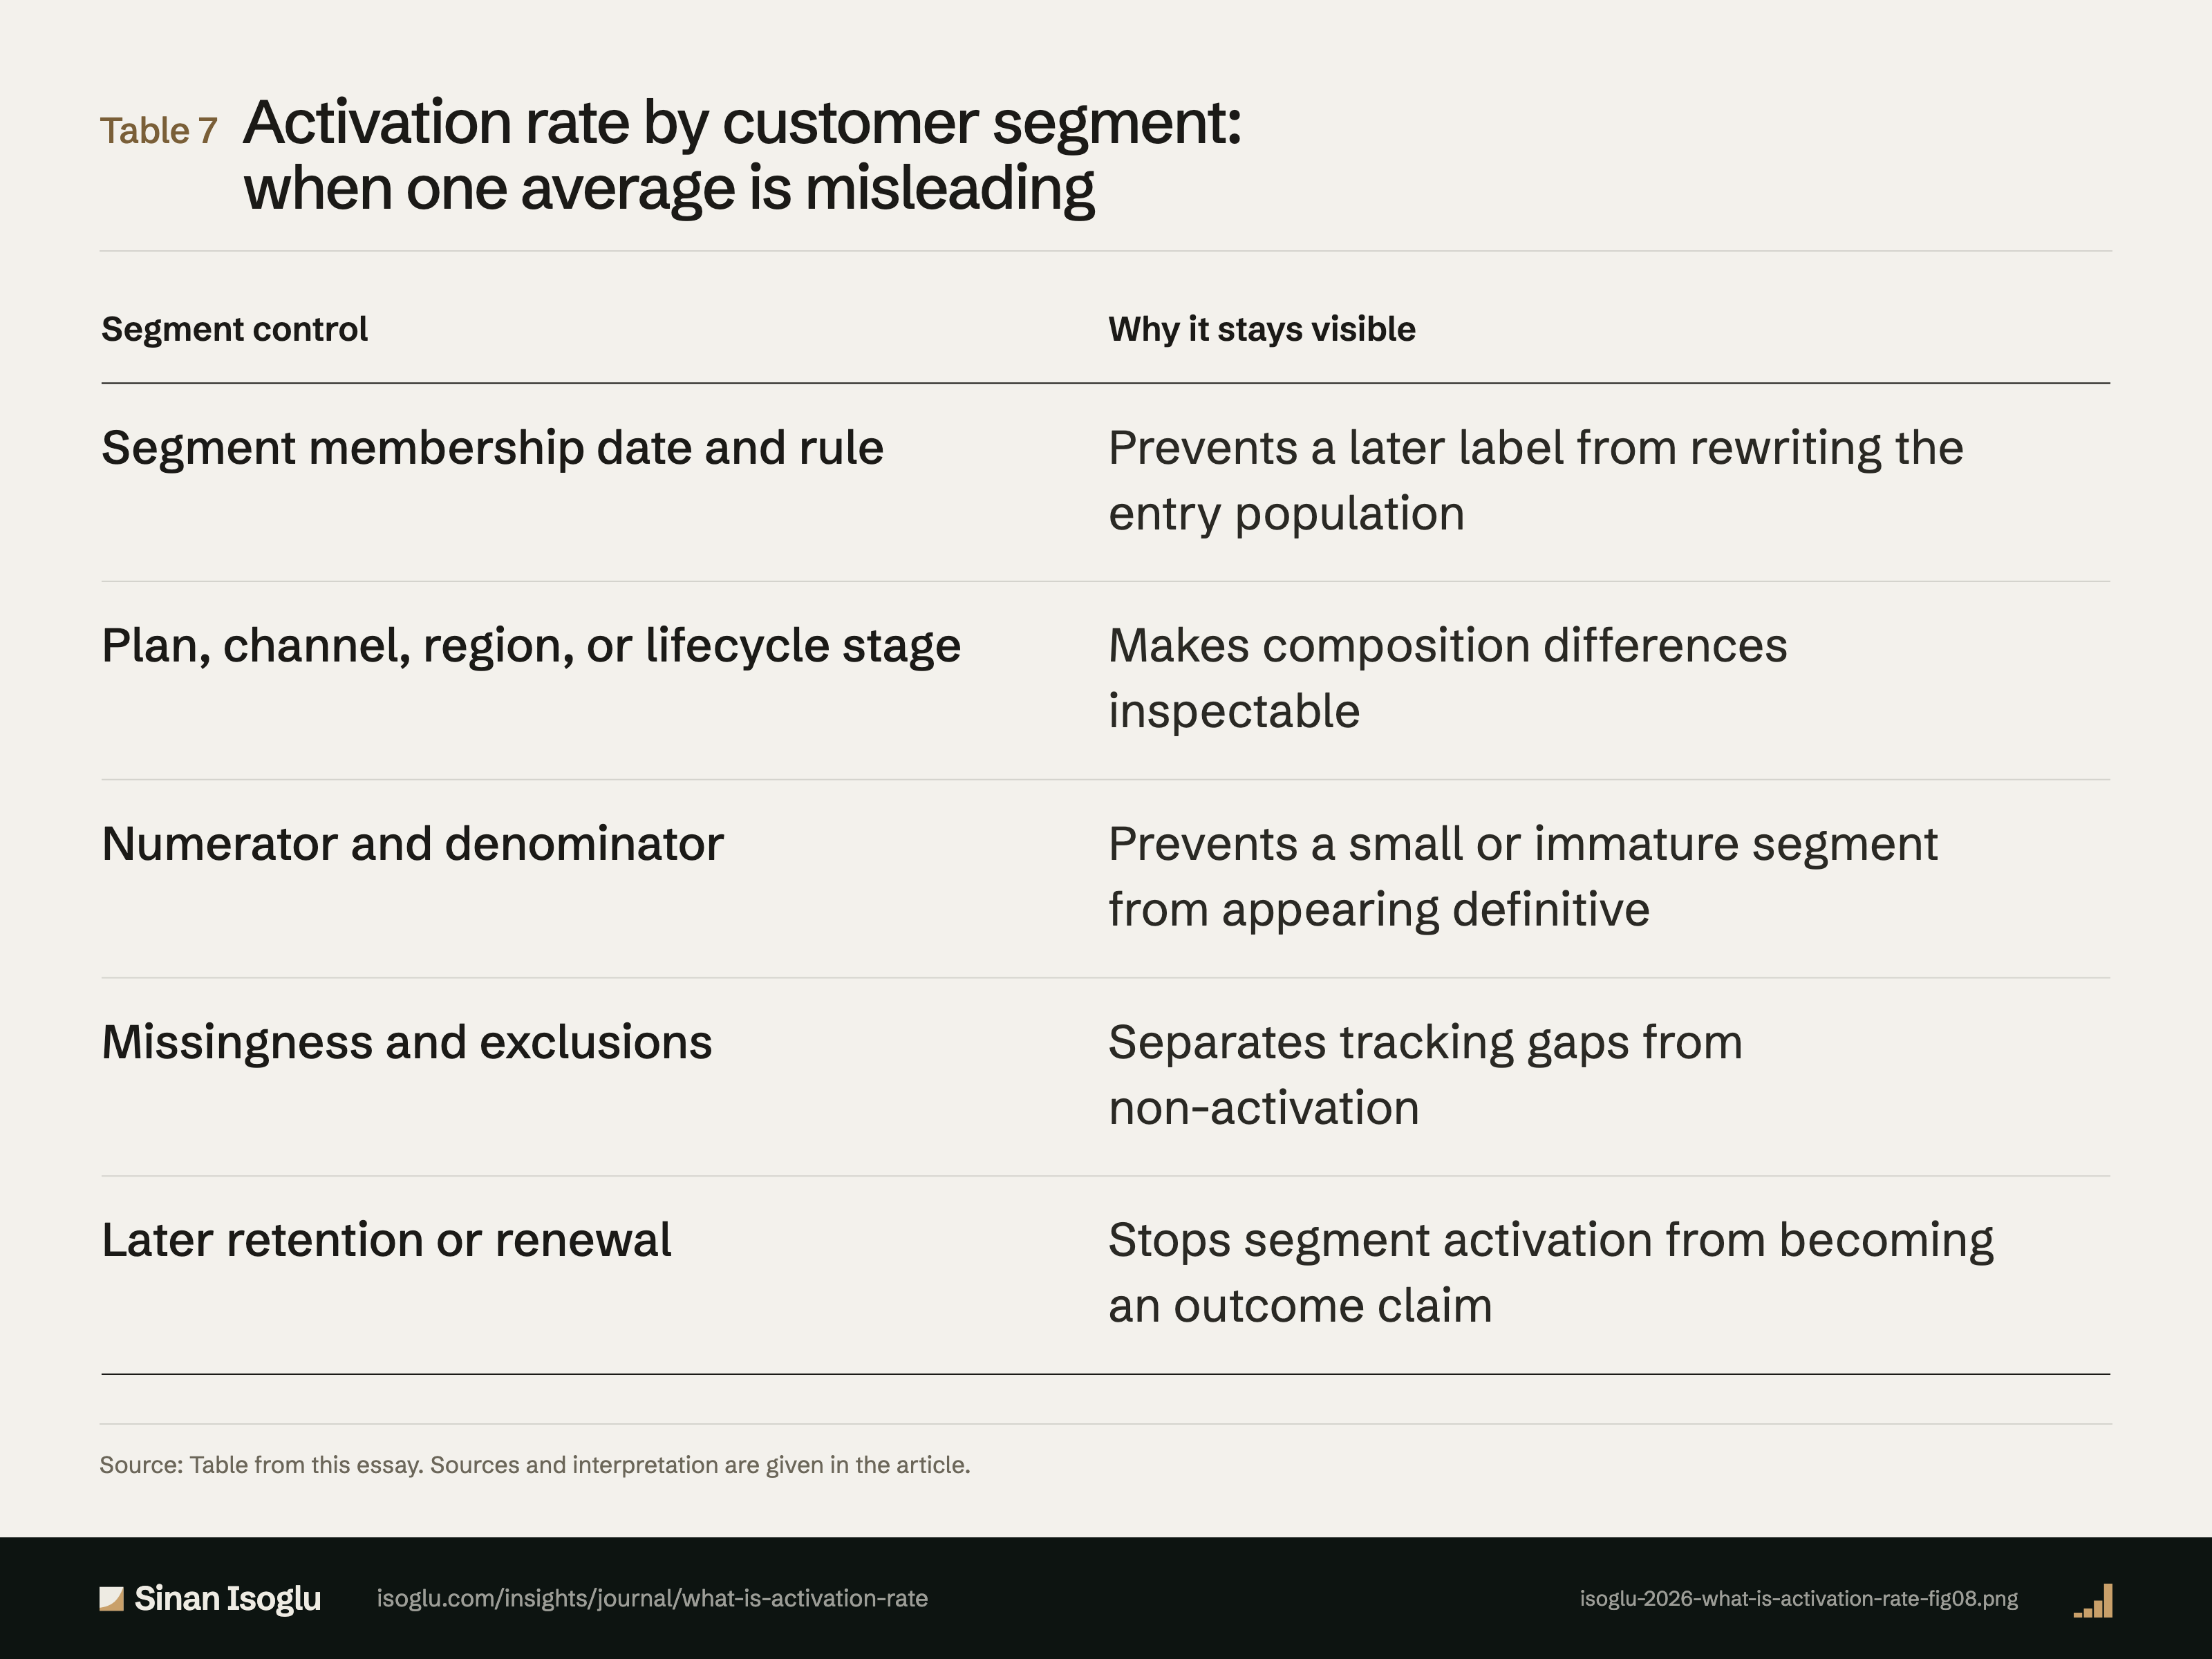
Table 7Table
Activation rate by customer segment: when one average is misleading
What is activation rate? The first value event must be observable
Contact
Bring the question you're working on.
Research, a guest lecture, or a commercial question.